China TSV Technology Market Size & Growth Rate
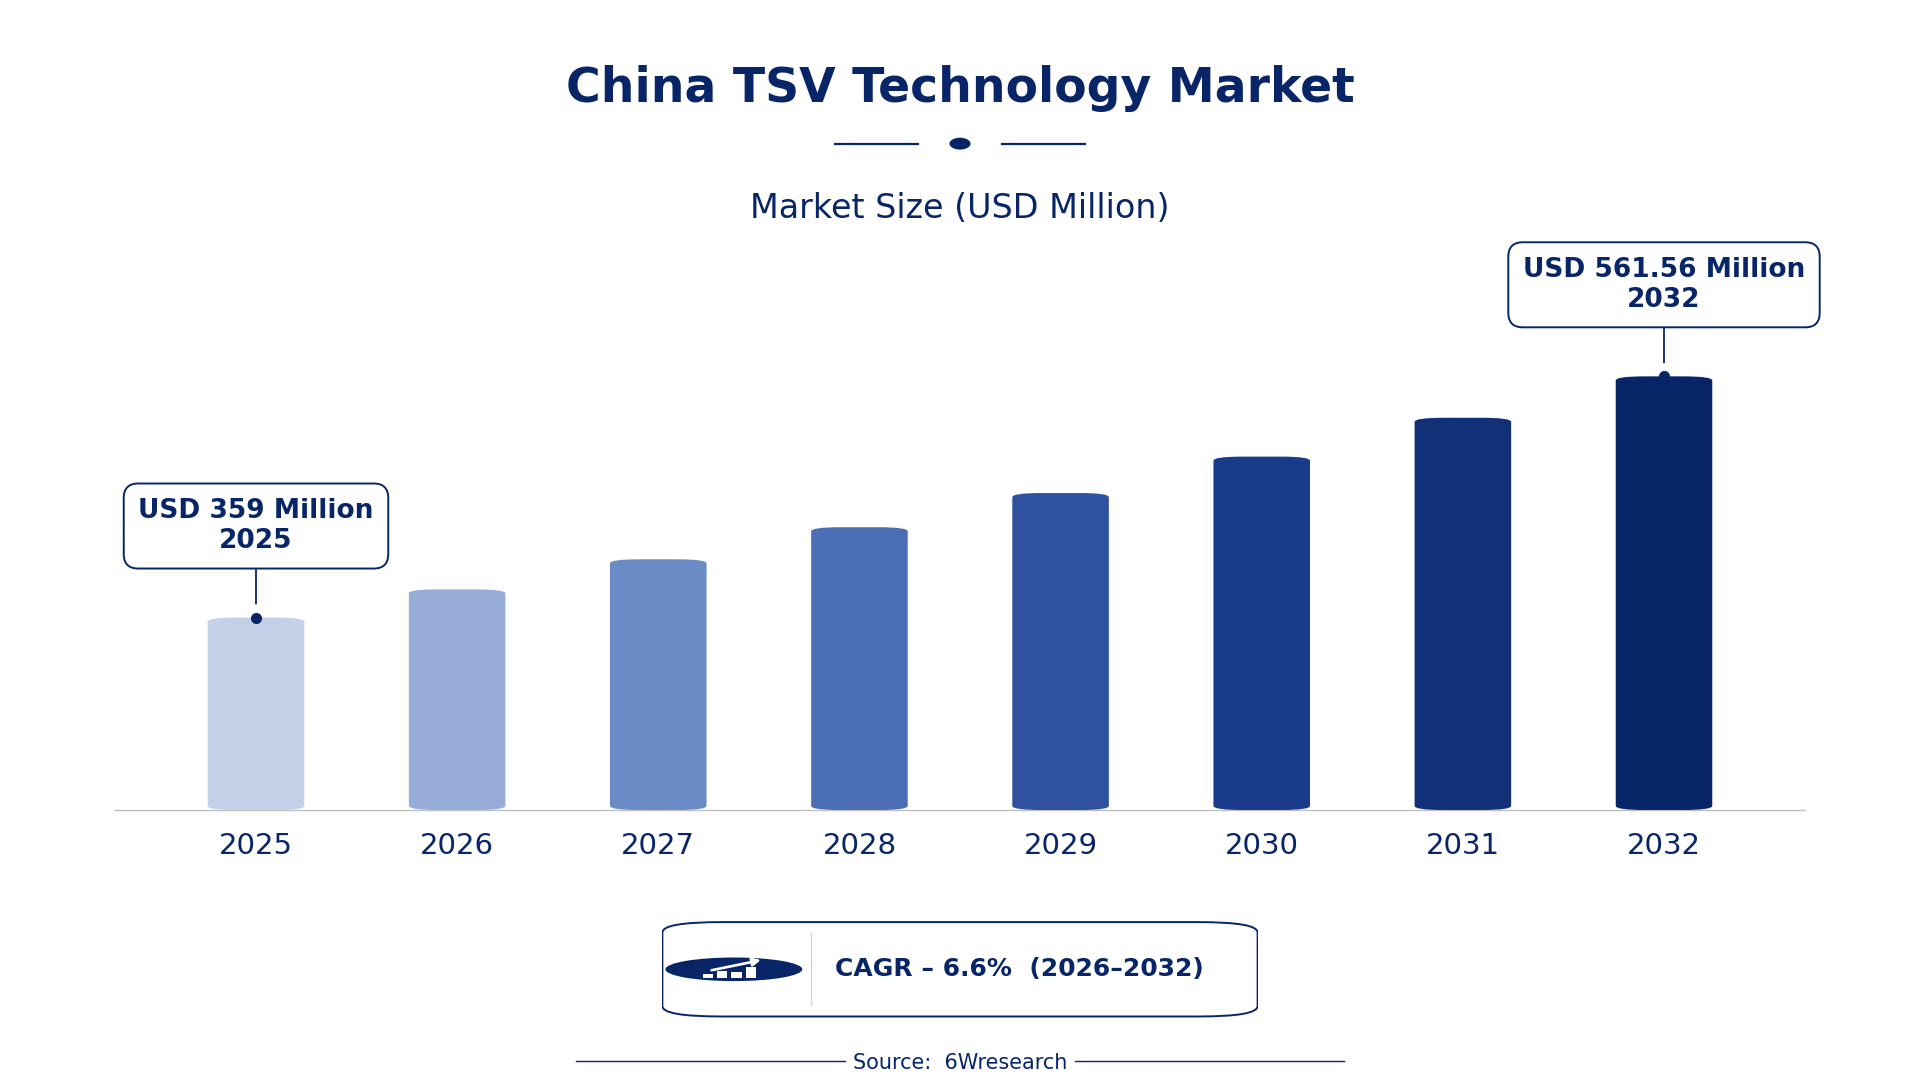
According to 6Wresearch internal database and industry insights, the China TSV Technology Market was valued at USD 359.0 million in 2025 and is projected to reach USD 561.56 million by 2032, growing at a CAGR of approximately 6.6% during 2026–2032.
China TSV Technology Market Highlights
| Report Metric | Details |
| Report Name | China TSV Technology Market |
| Market Size 2025 | USD 359.0 million |
| Market Size 2032 | USD 561.56 million |
| Absolute Growth 2025–2032 | USD 202.56 million |
| CAGR 2026–2032 | 6.6% |
| Peak Annual Growth | 8.8% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading TSV Type, 2025 | Via-First (48% share) |
| Leading Integration Level, 2025 | 3D IC Packaging (40% share) |
| Leading Use Case, 2025 | Memory Chips (48% share) |
| Leading End User, 2025 | Chip Manufacturers (43% share) |
| Fastest-Growing TSV Type | Via-Middle (8.4% CAGR) |
| Fastest-Growing Integration Level | Heterogeneous Integration (8.1% CAGR) |
| Fastest-Growing Use Case | Mobile Processors (8.8% CAGR) |
| Fastest-Growing End User | Electronics OEMs (9.0% CAGR) |
| Growing Sector | semiconductor manufacturing |
| Key End Users | Chip Manufacturers, Electronics OEMs, Semiconductor Foundries, IC Designers |
China TSV Technology Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
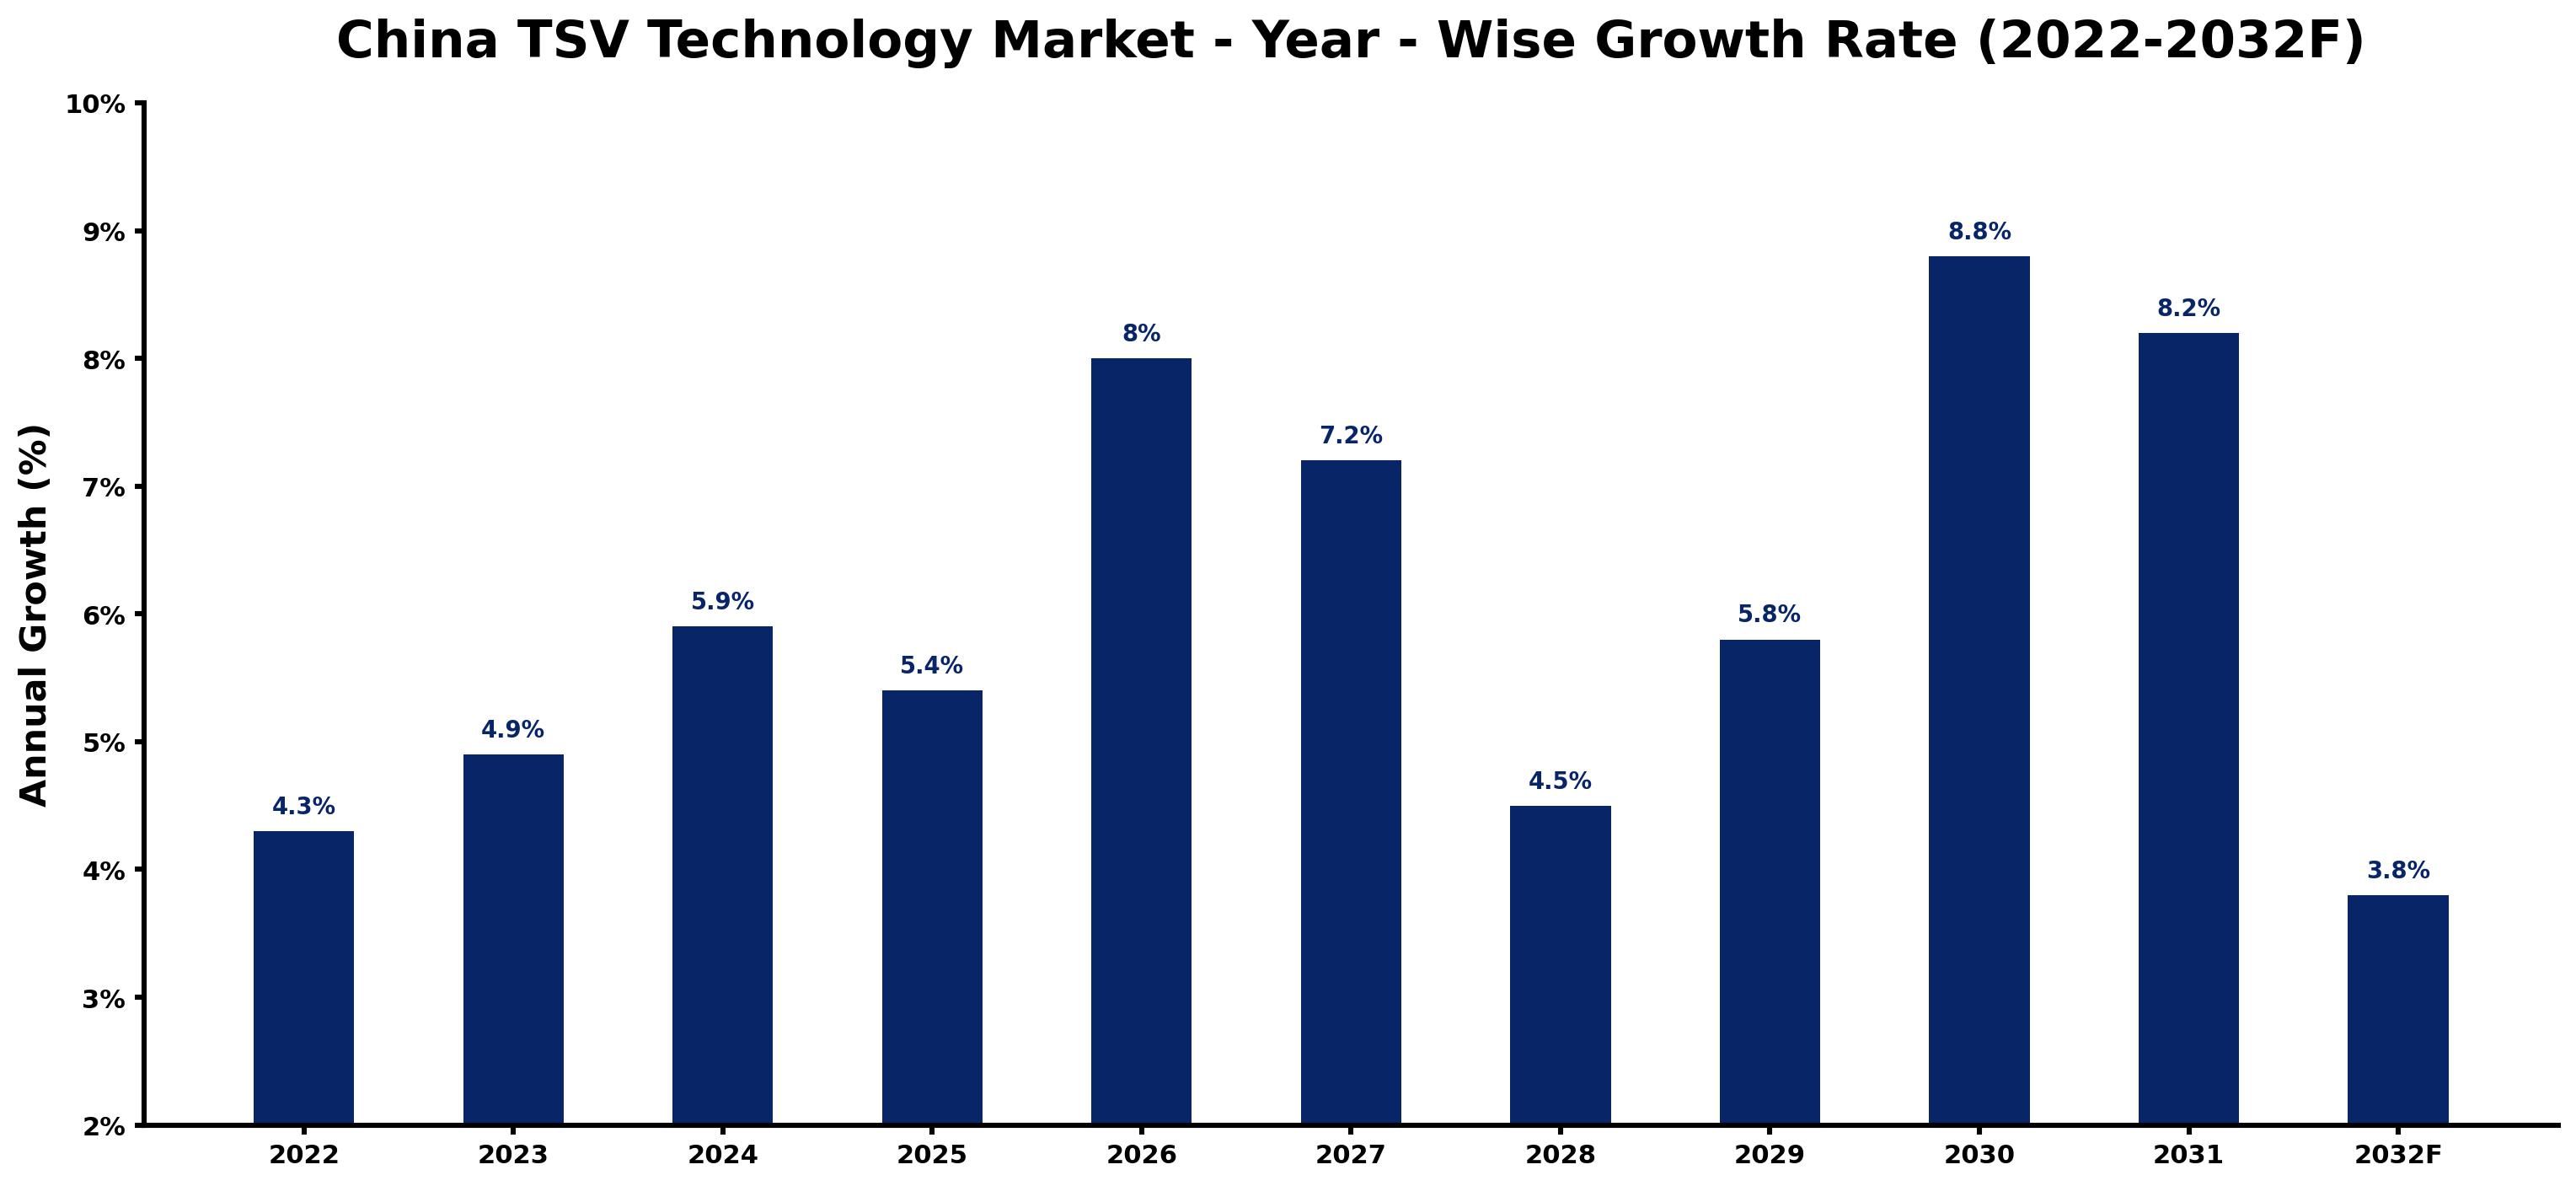
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.3 | The semiconductor industry produced approximately 1 trillion RMB worth of chips, indicating strong demand. |
| 2023 | 4.9 | A 20% increase in semiconductor investment accelerated growth in TSV technology applications. |
| 2024 | 5.9 | The adoption of TSV technology in over 60% of electronics OEM products drove further growth. |
| 2025 | 5.4 | The market experienced a slowdown as growth rates moderated after previous peaks. |
| 2026 | 8.0 | The National Semiconductor Innovation Strategy is expected to boost investment in advanced technologies. |
| 2027 | 7.2 | Investment in semiconductor R&D initiatives is projected to support ongoing growth in TSV applications. |
| 2028 | 4.5 | Demand from consumer electronics is likely to sustain market growth. |
| 2029 | 5.8 | A 15% annual growth in TSV applications through 2025 is expected to drive demand. |
| 2030 | 8.8 | The peak annual growth is projected as the semiconductor market reaches new heights. |
| 2031 | 8.2 | The market is anticipated to slow as growth rates normalise after the peak. |
| 2032 | 3.8 | The market will continue to grow, albeit at a slower pace, driven by the National Semiconductor Innovation Strategy. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China TSV Technology Market Synopsis
TSV Technology in China refers to Through-Silicon Via technology, a method for creating vertical interconnections between silicon chip layers. This technology improves the performance and density of integrated circuits, particularly in 3D IC packaging and high-performance computing. The China TSV Technology Market is expanding due to substantial investments in semiconductor manufacturing, with the industry generating approximately 1 trillion RMB worth of chips in 2022. The National Semiconductor Innovation Strategy and rising domestic demand for consumer electronics are key drivers of this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for high-performance computing applications | Driver | High | High-Performance Computing |
| Investment in semiconductor manufacturing facilities | Driver | High | Chip Manufacturers |
| Increasing focus on advanced packaging technologies | Opportunity | High | 3D IC Packaging |
| Rising demand for memory chips in consumer electronics | Opportunity | High | Memory Chips |
| High costs associated with TSV technology implementation | Restraint | Medium | Via-First |
| Challenges in meeting national standards for semiconductor manufacturing | Restraint | Medium | Heterogeneous Integration |
| Supply chain disruptions affecting semiconductor materials | Challenge | High | Advanced Interconnect |
| Delays in regulatory approvals for new semiconductor technologies | Challenge | Medium | Logic + Memory Stacking |
Evaluation of Drivers in China TSV Technology Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in semiconductor manufacturing facilities | Chip Manufacturers | The Ministry of Industry and Information Technology reported a 20% increase in semiconductor investment in 2022, leading to higher demand for TSV technology. |
| Growing adoption of TSV technology in electronics OEM products | Electronics OEMs | Over 60% of Chinese electronics OEMs reported using TSV technology in 2022, driving demand for advanced interconnection solutions. |
| Rising demand for high-performance computing solutions | High-Performance Computing | The semiconductor industry produced approximately 1 trillion RMB worth of chips in 2022, indicating strong demand for high-performance applications. |
| Expansion of 3D IC packaging technologies | 3D IC Packaging | The Semiconductor Industry Association of China estimates a 15% annual growth in TSV applications through 2025, boosting demand. |
| Focus on innovative semiconductor technologies | AI Accelerators | The 2023 'China Semiconductor Investment Fund' aims to support innovative semiconductor technologies, increasing TSV technology adoption. |
Market growth in China for TSV Technology rests on increasing demand from chip manufacturers, electronics OEMs, and high-performance computing sectors. The semiconductor industry produced approximately 1 trillion RMB worth of chips in 2022, boosting demand for TSV technology. Over 60% of electronics OEMs reported using TSV technology in their products, which improves connectivity in advanced applications. The Semiconductor Industry Association of China estimates a 15% annual growth in TSV applications through 2025, driven by the expansion of 3D IC packaging technologies. The 2023 'China Semiconductor Investment Fund' supports semiconductor technologies, encouraging further adoption of TSV solutions.
Evaluation of Restraints in China TSV Technology Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with TSV technology implementation | Via-First | The need for advanced materials and processes increases production costs, impacting profitability for manufacturers. |
| Challenges in meeting national standards for semiconductor manufacturing | Heterogeneous Integration | Strict regulations require extensive testing and certification, delaying product launches and increasing compliance costs. |
| Limited availability of skilled workforce in semiconductor manufacturing | Advanced Interconnect | A shortage of qualified professionals hampers production capabilities, affecting supply for TSV technology. |
| Supply chain disruptions affecting semiconductor materials | Logic + Memory Stacking | Global supply chain issues have led to material shortages, delaying production schedules for TSV-enabled chips. |
| Market competition from alternative interconnection technologies | 3D IC Packaging | Emerging technologies may divert investment away from TSV solutions, impacting market share. |
China TSV Technology Market Challenges
The China TSV Technology market faces considerable technological challenges, particularly in the adoption of advanced manufacturing processes. Many semiconductor foundries encounter difficulties with TSV integration, which can delay production timelines by up to six months for manufacturers. Local producers must allocate around 15% of their annual budgets to remain competitive against global firms, straining financial resources. Buyers often struggle to source high-quality TSV components, resulting in product launch delays that can hinder their market competitiveness. Supply chain disruptions, especially regarding raw materials, can lead to revenue losses of approximately 20% for producers, compounding these issues.
Trends in the China TSV Technology Market
Below mentioned are some of the trends shaping the China TSV Technology Market growth.
- Shift towards Advanced Packaging Technologies: Chip manufacturers are increasingly adopting advanced packaging technologies to improve performance. In 2022, over 60% of electronics OEMs reported using TSV technology, reflecting this trend.
- Growing Demand for AI Accelerators: The push for AI applications is driving demand for TSV technology in hardware design. The Semiconductor Industry Association of China estimates a 15% annual growth in TSV applications through 2025.
- Emphasis on Semiconductor Self-Sufficiency: The 'Made in China 2025' plan prioritises self-sufficiency in semiconductor production. The Chinese government aims for a 30% increase in domestic semiconductor production by 2025.
- Growth in Mobile Processors: Mobile processors are experiencing substantial growth, with an estimated CAGR of 8.8% through 2032. The Beijing region is a hub for IC design firms utilising TSV technology.
Investment Opportunities in the China TSV Technology Market
Some of the investment opportunities in the China TSV Technology Market are mentioned below.
- Investment in Semiconductor R&D Initiatives: The National Development and Reform Commission has allocated significant funds for semiconductor R&D initiatives, supporting innovation. This presents an opportunity for suppliers to engage with local chip manufacturers.
- Expansion of 3D IC Packaging Facilities: With a 40% market share in 2025, 3D IC packaging is a key area for investment. Chip manufacturers in the Guangdong province are heavily investing in TSV technology.
- Collaboration with Electronics OEMs: The increasing use of TSV technology among over 60% of electronics OEMs presents a timely opportunity for partnerships. Engaging in joint ventures can facilitate market entry.
- Focus on Heterogeneous Integration: Heterogeneous integration is projected to grow at a CAGR of 8.1% through 2032. Collaborating with IC designers in the Beijing region can improve market presence.
Government Initiatives in the China TSV Technology Market
The 'China Semiconductor Investment Fund', launched in 2023, allocates financial resources to support semiconductor technologies. This fund aims to improve R&D capabilities and strengthen the competitiveness of domestic manufacturers. The Electronics Industry Association of China also plays a role in promoting TSV technology adoption among manufacturers, facilitating collaboration and knowledge sharing. Additionally, the 'National Semiconductor Innovation Strategy' was introduced to enhance the semiconductor sector's capabilities, with a focus on advanced technologies and innovation.
The National Development and Reform Commission has allocated significant funds for semiconductor R&D initiatives, which support local manufacturers. The agency focuses on enhancing innovation within the semiconductor sector, ensuring that domestic producers can compete effectively in the global market. The Ministry of Industry and Information Technology oversees the implementation of policies that facilitate investment and growth in the semiconductor industry, ensuring that manufacturers can access necessary resources and support.
Future Insight of the China TSV Technology Market
The China TSV Technology market is projected to evolve significantly by 2032, driven by initiatives like the "National Semiconductor Innovation Strategy" and increased R&D funding. The Ministry of Industry and Information Technology anticipates a 30% rise in domestic semiconductor production, bolstering local supply chains. As more electronics OEMs adopt TSV technology, collaboration among manufacturers is expected to grow. The establishment of national standards will improve operational efficiency, enabling quicker time-to-market for new semiconductor products.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By TSV Type – Via-First Dominated, Via-Middle Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, with a 48% revenue share in 2025, Via-First was the largest tsv type category. The Via-First segment commands the largest share as it is crucial for establishing connections in the initial layers of 3D integrated circuits. This foundational role is underscored by the significant usage reported among over 60% of Chinese electronics OEMs, reflecting its essential nature in semiconductor applications. Over 2026–2032, Via-Middle is expected to post the fastest growth, at a CAGR of 8.4%. The Via-Middle segment is rapidly growing due to its role in facilitating communication between stacked chip layers, a demand that is increasing with advancements in semiconductor designs. The estimated 15% annual growth in TSV applications highlights the rising importance of this technology in the market. Suppliers should enhance their offerings in Via-Middle technologies to meet the growing demand for efficient inter-layer communication.
By Integration Level – 3D IC Packaging Dominated, Heterogeneous Integration Expected to Grow Fastest
In 2025, 3D IC Packaging led the integration level split with a 40% share. 3D IC Packaging leads the market share as it serves as a primary application area for TSV technology, essential for improving the density and performance of integrated circuits. The prominence of the Shanghai region in semiconductor manufacturing supports the widespread adoption of this integration level. The quickest growth will come from Heterogeneous Integration, forecast to expand at a CAGR of 8.1% between 2026 and 2032. Heterogeneous Integration is experiencing rapid growth as it allows for the combination of various chip technologies, which is increasingly sought after in modern electronics. Ongoing investments in semiconductor R&D initiatives are likely to further accelerate this trend. Buyers should consider partnerships with suppliers who excel in Heterogeneous Integration to leverage the benefits of diverse chip technologies.
By Use Case – Memory Chips Dominated, Mobile Processors Expected to Grow Fastest
Memory Chips took a 48% share of use case in 2025, more than any other category. Memory Chips dominate the market share as they represent a significant application area for TSV technology, vital for enhancing memory performance in electronics. The robust demand for consumer electronics in China, driven by its large population, solidifies this segment's strong position. Mobile Processors are projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Mobile Processors are witnessing the fastest growth due to their essential role in high-performance mobile computing, which is increasingly critical in today's technology landscape. The push for advanced mobile devices drives manufacturers to adopt TSV technology for improved efficiency. Suppliers must align their strategies to meet the increasing demand for TSV-enabled Mobile Processors to capture emerging market opportunities.
By End User – Chip Manufacturers Dominated, Electronics OEMs Expected to Grow Fastest
Chip Manufacturers held a 43% share of the China TSV Technology Market by end user in 2025. Chip Manufacturers hold the largest share as they are the primary users of TSV technology in semiconductor production, directly influencing market dynamics. The concentration of over 100 semiconductor foundries in China highlights the importance of this user group in the industry. Electronics OEMs are set to record the highest CAGR in this split, 9.0% over 2026–2032. Electronics OEMs are experiencing the fastest growth as they increasingly incorporate TSV technology into their product designs, driven by the need for enhanced performance in consumer electronics. Support from industry associations for TSV adoption is likely to fuel this trend. Suppliers should focus on developing tailored solutions for Electronics OEMs to capitalise on the growing integration of TSV technology in product design.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China TSV Technology Market Outlook
- Market Size of China TSV Technology Market, 2025
- Forecast of China TSV Technology Market, 2032
- Historical Data and Forecast of China TSV Technology Revenues & Volume for the Period 2022 - 2032F
- China TSV Technology Market Trend Evolution
- China TSV Technology Market Drivers and Challenges
- China TSV Technology Price Trends
- China TSV Technology Porter's Five Forces
- China TSV Technology Industry Life Cycle
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By TSV Type for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Via-First for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Via-Middle for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Via-Last for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By High Aspect Ratio TSV for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Integration Level for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By 3D IC Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Heterogeneous Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Logic + Memory Stacking for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Advanced Interconnect for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Use Case for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Memory Chips for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Mobile Processors for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By High-Performance Computing for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By AI Accelerators for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Chip Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Electronics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By Semiconductor Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China TSV Technology Market Revenues & Volume By IC Designers for the Period 2022 - 2032F
- China TSV Technology Import Export Trade Statistics
- Market Opportunity Assessment By TSV Type
- Market Opportunity Assessment By Integration Level
- Market Opportunity Assessment By Use Case
- Market Opportunity Assessment By End User
- China TSV Technology Top Companies Market Share
- China TSV Technology Competitive Benchmarking By Technical and Operational Parameters
- China TSV Technology Company Profiles
- China TSV Technology Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By TSV Type
- Via-First
- Via-Middle
- Via-Last
- High Aspect Ratio TSV
By Integration Level
- 3D IC Packaging
- Heterogeneous Integration
- Logic + Memory Stacking
- Advanced Interconnect
By Use Case
- Memory Chips
- Mobile Processors
- High-Performance Computing
- AI Accelerators
By End User
- Chip Manufacturers
- Electronics OEMs
- Semiconductor Foundries
- IC Designers































