China Underbody Insulation Market Size & Growth Rate
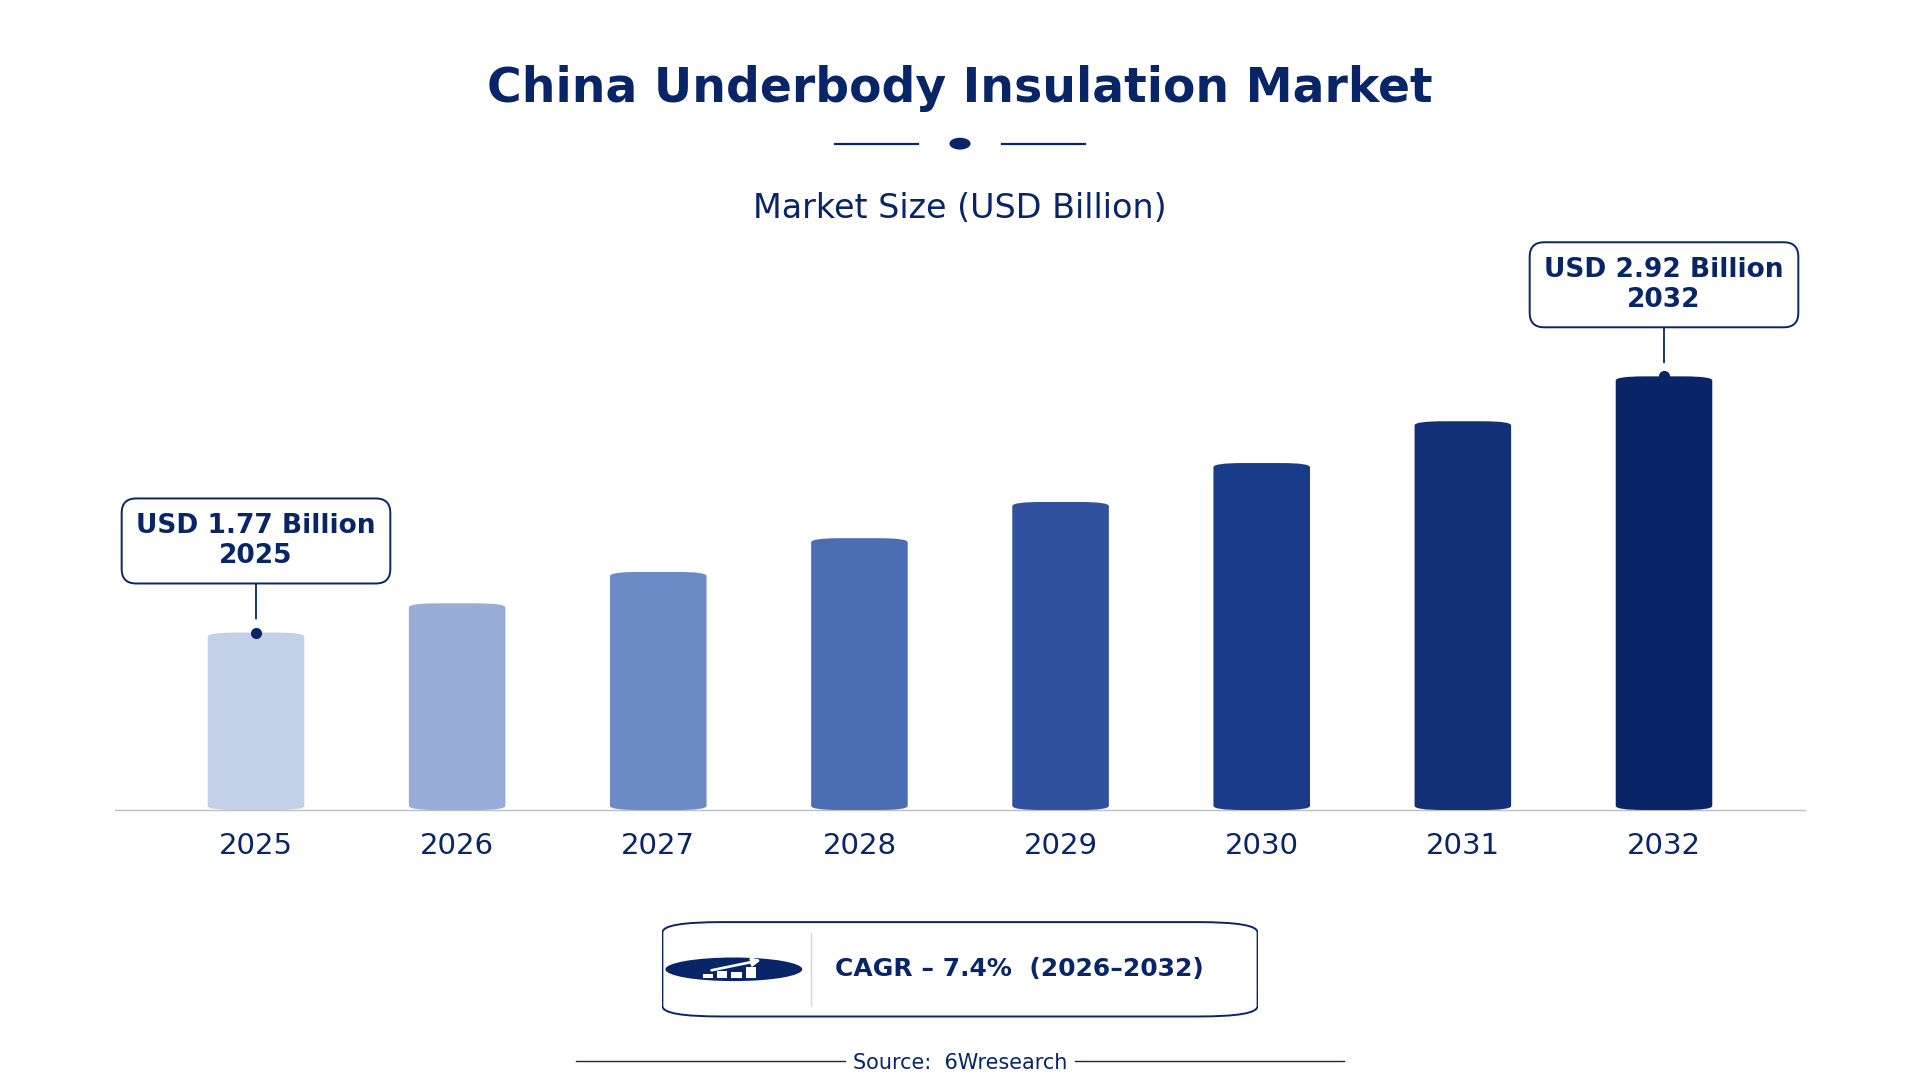
According to 6Wresearch internal database and industry insights, the China Underbody Insulation Market was valued at USD 1.77 billion in 2025 and is projected to reach USD 2.92 billion by 2032, growing at a CAGR of approximately 7.4% during 2026–2032.
China Underbody Insulation Market Highlights
| Report Metric | Details |
| Report Name | China Underbody Insulation Market |
| Market Size 2025 | USD 1.77 billion |
| Market Size 2032 | USD 2.92 billion |
| Absolute Growth 2025–2032 | USD 1.15 billion |
| CAGR 2026–2032 | 7.4% |
| Peak Annual Growth | 9.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Insulation Type, 2025 | Sound Deadening Mats (46% share) |
| Leading Material Used, 2025 | Polyurethane Foam (36% share) |
| Leading Vehicle Segment, 2025 | Passenger Cars (50% share) |
| Leading End User, 2025 | OEMs (41% share) |
| Fastest-Growing Insulation Type | Spray-On Coatings (10.1% CAGR) |
| Fastest-Growing Vehicle Segment | EVs (9.6% CAGR) |
| Fastest-Growing End User | Electric Vehicle Makers (9.2% CAGR) |
| Growing Sector | Electric Vehicle Makers |
| Key End Users | OEMs, Electric Vehicle Makers, Auto Assemblers, Auto Workshops |
China Underbody Insulation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
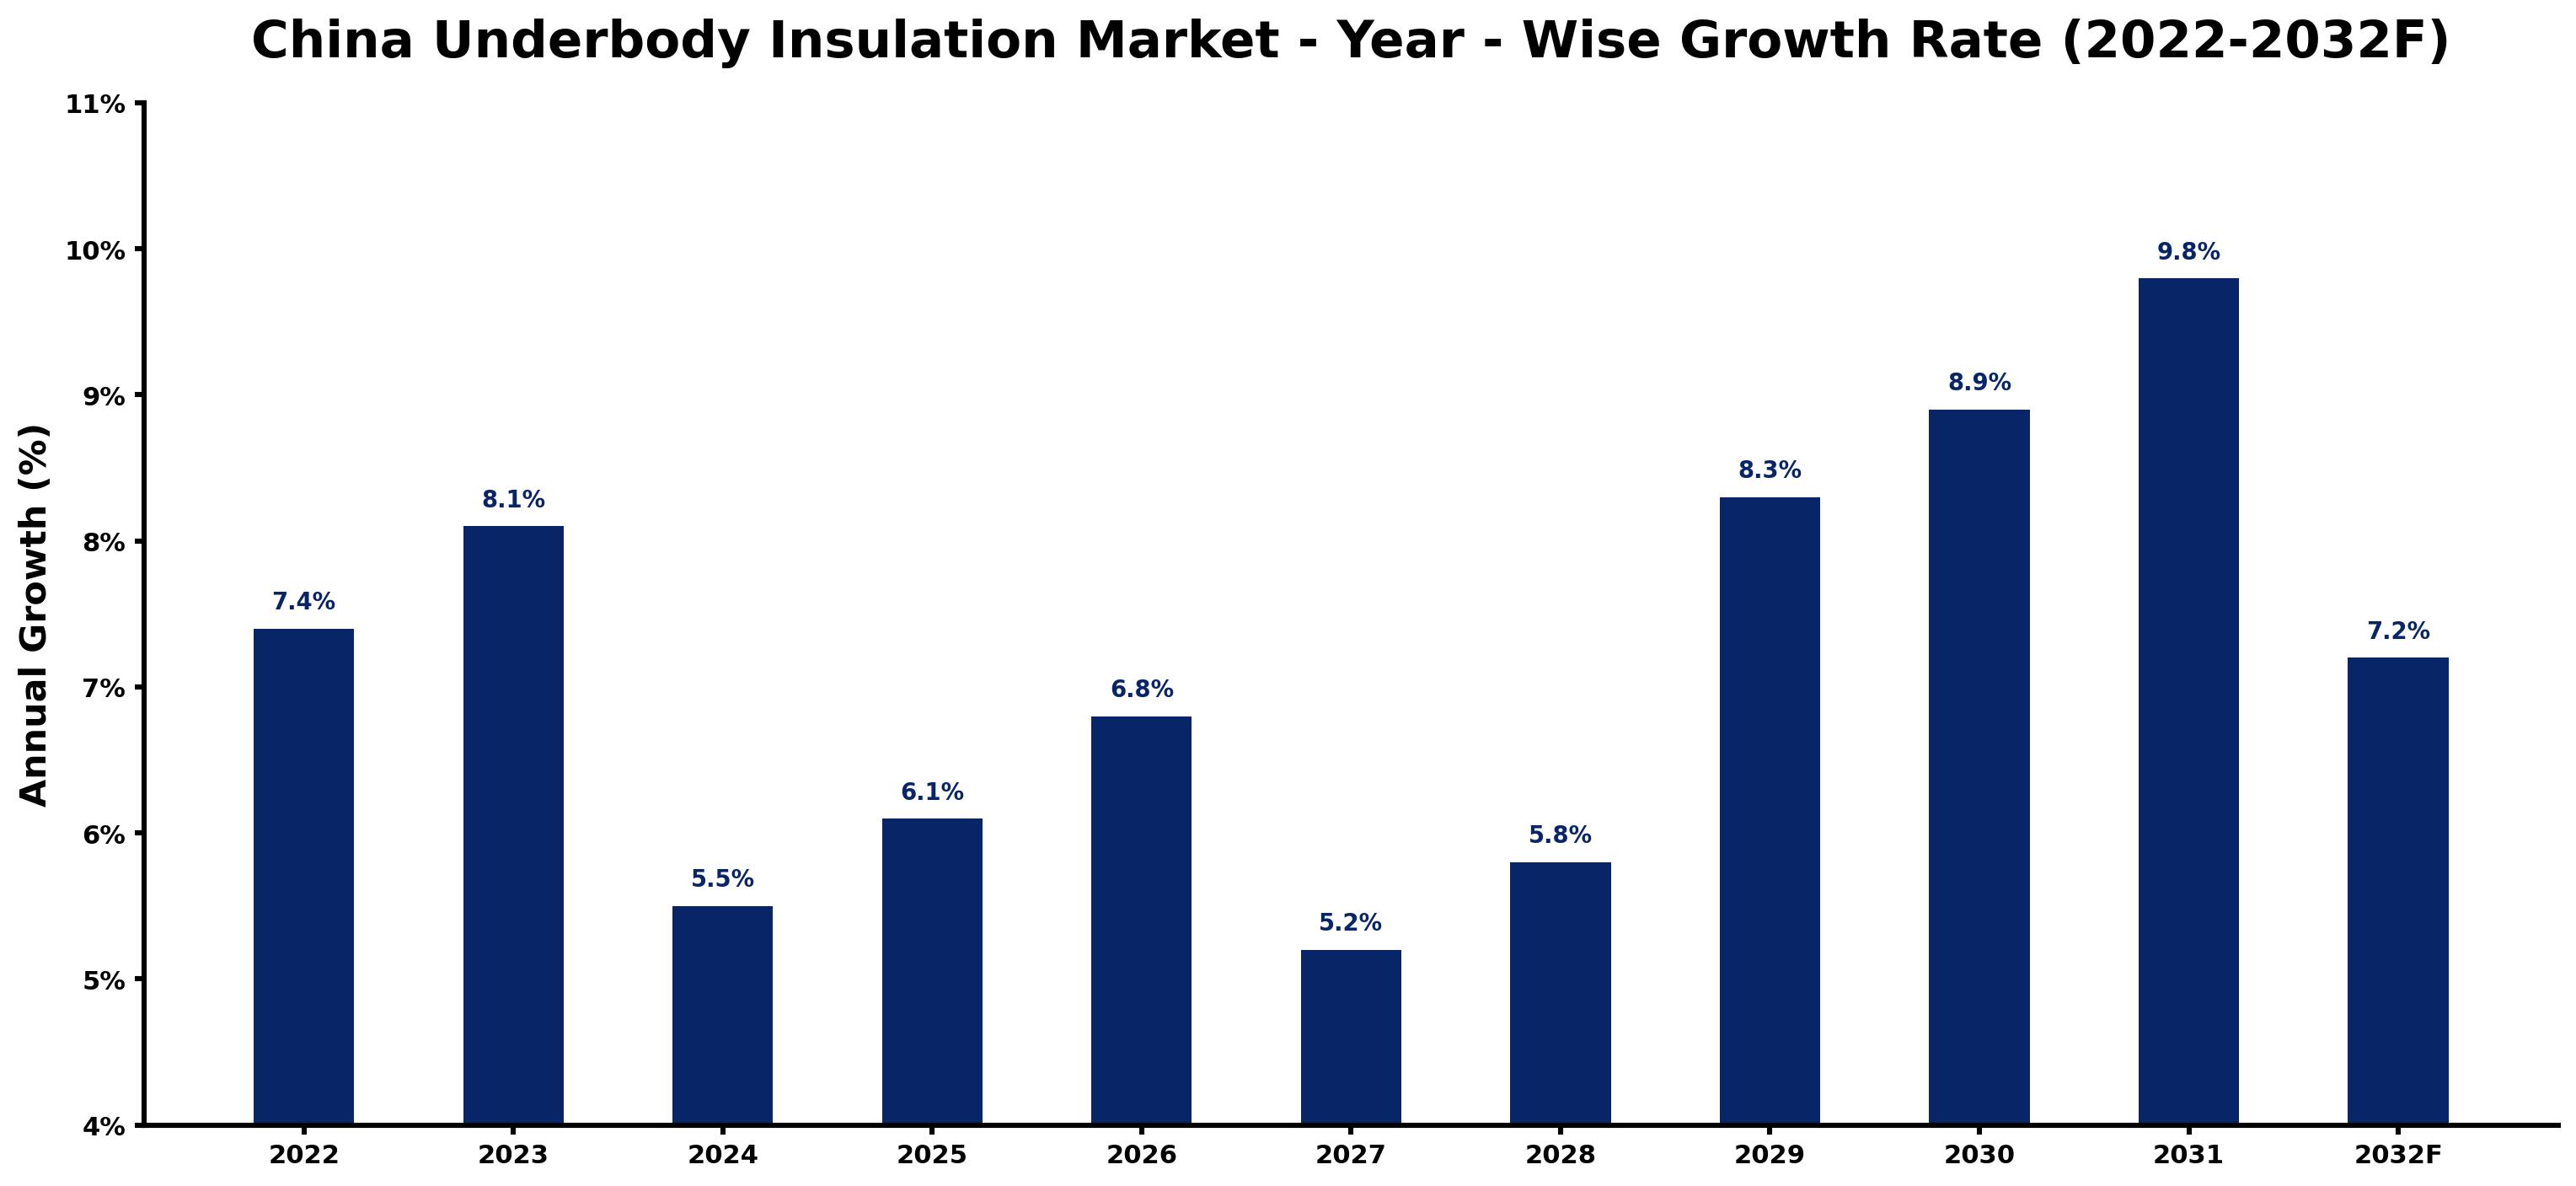
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.4 | The market showed solid growth due to strong vehicle production figures in China. |
| 2023 | 8.1 | Increased demand for insulation materials coincided with rising vehicle manufacturing rates. |
| 2024 | 5.5 | Growth slowed as manufacturers adjusted to supply chain constraints and market conditions. |
| 2025 | 6.1 | A rebound in production and assembly activities spurred renewed interest in insulation solutions. |
| 2026 | 6.8 | The market experienced a slight increase as electric vehicle manufacturing gained momentum. |
| 2027 | 5.2 | Growth slowed due to a temporary saturation in the insulation materials market. |
| 2028 | 5.8 | Demand improved as manufacturers focused on enhancing vehicle comfort and efficiency. |
| 2029 | 8.3 | A surge in electric vehicle sales drove further demand for underbody insulation materials. |
| 2030 | 8.9 | Continued growth was supported by rising consumer preferences for quieter vehicles. |
| 2031 | 9.8 | The market peaked as the automotive industry embraced advanced insulation technologies. |
| 2032 | 7.2 | Growth slowed as the market stabilised after reaching a peak in insulation adoption. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Underbody Insulation Market Synopsis
Underbody insulation in China refers to materials used in vehicles to reduce noise and thermal transfer. Commonly made from polyurethane foam and butyl rubber, these materials improve passenger comfort and protect vehicle components. The China Underbody Insulation Market is growing due to strong domestic vehicle production, particularly in the electric vehicle segment, which is expected to account for 20% of sales by 2025. The Yangtze River Delta serves as a major automotive manufacturing hub, driving demand for insulation solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising electric vehicle production drives demand for insulation materials. | Driver | High | Electric Vehicle Makers |
| Increased focus on passenger comfort leads to higher insulation material usage. | Driver | High | Passenger Cars |
| The automotive aftermarket is valued at over $100 billion, creating opportunities for insulation suppliers. | Opportunity | High | Auto Workshops |
| Growing investments in automotive manufacturing facilities present new market entry points. | Opportunity | Medium | Light Commercial Vehicles |
| Supply chain disruptions can delay material availability for manufacturers. | Restraint | High | Sound Deadening Mats |
| Stringent environmental regulations may increase production costs for insulation materials. | Restraint | Medium | Sound Deadening Mats |
| The China Underbody Insulation Market faces challenges from fluctuating raw material prices. | Challenge | High | Sound Deadening Mats |
| Competition from alternative insulation materials may limit market growth. | Challenge | Medium | Sound Deadening Mats |
Evaluation of Drivers in China Underbody Insulation Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles creates demand for advanced insulation solutions. | Electric Vehicle Makers | The average annual growth rate of EV sales is projected at 30% until 2025, leading to higher insulation material purchases. |
| Growing consumer demand for quieter vehicles drives insulation material adoption. | Passenger Cars | The installed base of passenger cars in China reached 300 million in 2022, increasing the need for noise reduction. |
| The automotive sector's contribution of 10% to China's GDP supports investment in insulation technologies. | OEMs | Investments exceeding $200 billion in the automotive industry support demand for quality insulation materials. |
| The automotive aftermarket's valuation at over $100 billion encourages retrofitting and insulation upgrades. | Auto Workshops | With many vehicles on the road, workshops are increasingly sourcing insulation materials for repairs. |
| The 'New Energy Vehicle Industry Development Plan' promotes insulation material usage in EVs. | Electric Vehicle Makers | This government initiative aims for 20% of all vehicle sales to be electric by 2025, boosting insulation demand. |
Growth in the Underbody Insulation market in China comes from rising production of electric vehicles, which is projected to grow at an average annual rate of 30% until 2025. The automotive sector contributes 10% to China's GDP, driving investments in insulation technologies. The installed base of passenger cars reached 300 million in 2022, creating a greater need for noise reduction solutions. The automotive aftermarket, valued at over $100 billion, drives retrofitting and insulation upgrades. This combination of factors will propel the market forward as manufacturers adapt to changing consumer preferences.
Evaluation of Restraints in China Underbody Insulation Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices can impact production costs for insulation materials. | Polyurethane Foam | Volatility in the prices of polyurethane foam and butyl rubber affects manufacturers' margins. |
| Stringent environmental regulations may increase compliance costs for producers. | Sound Deadening Mats | New standards require investment in sustainable production practices, raising overall expenses. |
| Supply chain disruptions can delay material availability for manufacturers. | Sound Deadening Mats | Recent global events have caused delays in sourcing insulation materials. |
| Competition from alternative insulation materials may limit market growth. | Sound Deadening Mats | Innovations in soundproofing technologies present viable alternatives to traditional insulation solutions. |
| Market saturation in certain insulation types may hinder new product introductions. | Sound Deadening Mats | With many established products available, new entrants face challenges in gaining market share. |
China Underbody Insulation Market Challenges
The China Underbody Insulation Market faces a few practical problems, starting with rising material costs that burden vehicle manufacturers. The price of polyurethane foam has surged by 15% over the past year, impacting production budgets for buyers. Suppliers struggle with outdated technology, as many still rely on traditional methods that limit efficiency and prolong production times, causing delays in deliveries to manufacturers. Regulatory compliance poses challenges, with the National Standard GB/T 36239-2018 necessitating costly adjustments for producers, ultimately raising prices for consumers. Supply chain disruptions in key regions like Guangdong have led to sourcing delays, forcing manufacturers to extend lead times by up to three weeks.
Trends in the China Underbody Insulation Market
Buyers and suppliers in the China Underbody Insulation Market are adjusting to the following trends.
- Shift towards Sustainable Insulation Materials: The automotive industry is increasingly adopting sustainable insulation materials to meet environmental standards. The 'Green Vehicle Development Strategy' launched in 2022 aims to improve environmental standards for vehicle manufacturing, with the goal of reducing carbon footprints.
- Increase in Electric Vehicle Production: The rise in electric vehicle production is driving demand for advanced underbody insulation solutions. In 2023, the government set a target of 20% electric vehicle sales by 2025, influencing manufacturers to improve insulation offerings.
- Expansion of Aftermarket Services: The automotive aftermarket is expanding rapidly, creating opportunities for insulation suppliers. Valued at over $100 billion, it encourages retrofitting and upgrades, leading to increased demand for insulation materials.
- Adoption of Smart Vehicle Technologies: The introduction of smart vehicle technologies is influencing insulation material choices. The 'National Intelligent Connected Vehicle Innovation and Development Strategy' introduced in 2023 promotes innovations that require advanced insulation solutions.
Investment Opportunities in the China Underbody Insulation Market
Several openings in the China Underbody Insulation Market merit attention from investors.
- Guangdong Province as a Key Production Hub: Guangdong province is a major automotive production hub, creating opportunities for insulation suppliers. With over 25 million vehicles produced in 2022, suppliers can partner with local manufacturers to meet demand.
- Supply of Polyurethane Foam for Insulation: Polyurethane foam is a leading material for underbody insulation, with a market share of 36%. Suppliers can invest in production facilities to cater to the demand from OEMs and electric vehicle makers.
- Entry through Joint Ventures: Establishing joint ventures with local manufacturers can improve market access. As the automotive industry grows, collaboration with established players will facilitate entry and expansion in the insulation market.
- Timing for Investment in EV Insulation: Now is an opportune time to invest in insulation solutions tailored for electric vehicles. With the average annual growth rate of EV sales projected at 30% until 2025, suppliers can benefit from this trend.
Government Initiatives in the China Underbody Insulation Market
The 'Automotive Industry Mid- and Long-Term Development Plan' issued by the State Council in 2021 promotes sustainable automotive growth. This plan emphasises the need for advanced manufacturing and innovation in the automotive sector, impacting insulation material standards. Additionally, the 'New Energy Vehicle Industry Development Plan' by the Ministry of Industry and Information Technology, launched in 2020, aims for 20% of all vehicle sales to be electric by 2025, influencing insulation material demand. The 'Green Vehicle Development Strategy' launched by the Ministry of Ecology and Environment in 2022 improves environmental standards for vehicle manufacturing, affecting insulation production practices.
The 'Automotive Industry Standardization Work Plan' by the Standardization Administration of China aims to improve safety and quality standards. This initiative, introduced in 2021, ensures that insulation materials meet stringent quality requirements, providing assurance to manufacturers and consumers alike. The Ministry of Industry and Information Technology oversees these standards, facilitating compliance and promoting best practices in the sector. The China Automotive Technology and Research Center also plays a role in setting industry standards and conducting research to support manufacturers.
Future Insight of the China Underbody Insulation Market
By 2032, buyers and suppliers in the China Underbody Insulation Market can anticipate substantial changes driven by various factors. The government’s 'New Energy Vehicle Industry Development Plan' will promote the adoption of modern insulation materials, enhancing overall product performance. Investments exceeding $200 billion in the automotive sector will strengthen production capabilities and efficiency. The average annual growth rate of electric vehicle sales, projected at 30% until 2025, will maintain demand for high-quality insulation solutions, benefiting both manufacturers and suppliers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Insulation Type – Sound Deadening Mats Dominated, Spray-On Coatings Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Sound Deadening Mats held a 46% share of the China Underbody Insulation Market by insulation type in 2025. Sound deadening mats command the largest market share because they effectively minimise noise levels within vehicles, thus enhancing passenger comfort. Their widespread application in significant automotive production areas, such as the Yangtze River Delta, solidifies their leading status in the market. Spray-On Coatings are set to record the highest CAGR in this split, 10.1% over 2026–2032. Spray-on coatings are experiencing rapid growth due to their adaptability for custom insulation applications in various vehicle models. The anticipated rise in electric vehicle sales, expected to reach 20% by 2025, serves as a crucial catalyst for this segment's expansion. This trend indicates that suppliers must focus on developing versatile spray-on coatings to cater to the evolving needs of the underbody insulation market.
By Material Used – Polyurethane Foam Dominated and Is Expected to Record the Fastest Growth
With a 36% revenue share in 2025, Polyurethane Foam was the largest material used category. Polyurethane foam holds the largest market share due to its excellent insulation properties, making it the preferred choice for manufacturers. Its widespread application in over 25 million vehicles produced in China in 2022 underscores its significance in the market. Its lead should widen, with a projected CAGR of 8.5% during 2026–2032, the highest in this split. The continued dominance of polyurethane foam as both the leader and fastest-growing material indicates that its versatility will keep it at the forefront of underbody insulation solutions. As electric vehicle production surges, the demand for this material will likely expand even further. Buyers should prioritise sourcing high-quality polyurethane foam to ensure optimal insulation performance in their vehicles.
By Vehicle Segment – Passenger Cars Dominated, EVs Expected to Grow Fastest
Passenger Cars took a 50% share of vehicle segment in 2025, more than any other category. Passenger cars represent the largest segment for underbody insulation, driven by the substantial installed base of 300 million vehicles in China. This segment's prominence is further supported by the ongoing production of over 25 million vehicles annually. The quickest growth will come from EVs, forecast to expand at a CAGR of 9.6% between 2026 and 2032. The electric vehicle segment is the fastest-growing due to the government's target of 20% EV sales by 2025, reflecting a shift towards sustainable transportation. As more consumers adopt EVs, the demand for effective underbody insulation will rise correspondingly. Suppliers must adapt their offerings to meet the unique insulation needs of the rapidly growing electric vehicle market.
By End User – OEMs Dominated, Electric Vehicle Makers Expected to Grow Fastest
OEMs accounted for a 41% market share by end user in 2025. OEMs represent the largest share of the market as they are the primary users of underbody insulation during vehicle assembly. Their role in producing over 25 million vehicles annually solidifies their leading position in the market. Electric Vehicle Makers are projected to grow fastest, at a CAGR of 9.2% during 2026–2032. Electric vehicle makers are the fastest-growing segment, fuelled by the rising demand for electric vehicles and the necessity for improved passenger comfort. This trend indicates a substantial increase in the need for specialised insulation solutions tailored for EVs. Manufacturers must adapt their product offerings to align with the specific needs of electric vehicle makers to seize emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Underbody Insulation Market Outlook
- Market Size of China Underbody Insulation Market, 2025
- Forecast of China Underbody Insulation Market, 2032
- Historical Data and Forecast of China Underbody Insulation Revenues & Volume for the Period 2022 - 2032F
- China Underbody Insulation Market Trend Evolution
- China Underbody Insulation Market Drivers and Challenges
- China Underbody Insulation Price Trends
- China Underbody Insulation Porter's Five Forces
- China Underbody Insulation Industry Life Cycle
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Insulation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Thermal Pads for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Sound Deadening Mats for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Spray-On Coatings for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Pre-Cut Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Polyurethane Foam for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Butyl Rubber for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Asphalt-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Felt/Fiber Glass for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Light Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By SUVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By EVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Auto Assemblers for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Auto Workshops for the Period 2022 - 2032F
- Historical Data and Forecast of China Underbody Insulation Market Revenues & Volume By Electric Vehicle Makers for the Period 2022 - 2032F
- China Underbody Insulation Import Export Trade Statistics
- Market Opportunity Assessment By Insulation Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Vehicle Segment
- Market Opportunity Assessment By End User
- China Underbody Insulation Top Companies Market Share
- China Underbody Insulation Competitive Benchmarking By Technical and Operational Parameters
- China Underbody Insulation Company Profiles
- China Underbody Insulation Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Insulation Type
- Thermal Pads
- Sound Deadening Mats
- Spray-On Coatings
- Pre-Cut Panels
By Material Used
- Polyurethane Foam
- Butyl Rubber
- Asphalt-Based
- Felt/Fiber Glass
By Vehicle Segment
- Passenger Cars
- Light Commercial Vehicles
- SUVs
- EVs
By End User
- OEMs
- Auto Assemblers
- Auto Workshops
- Electric Vehicle Makers































