China Vehicle Body Materials Market Size & Growth Rate
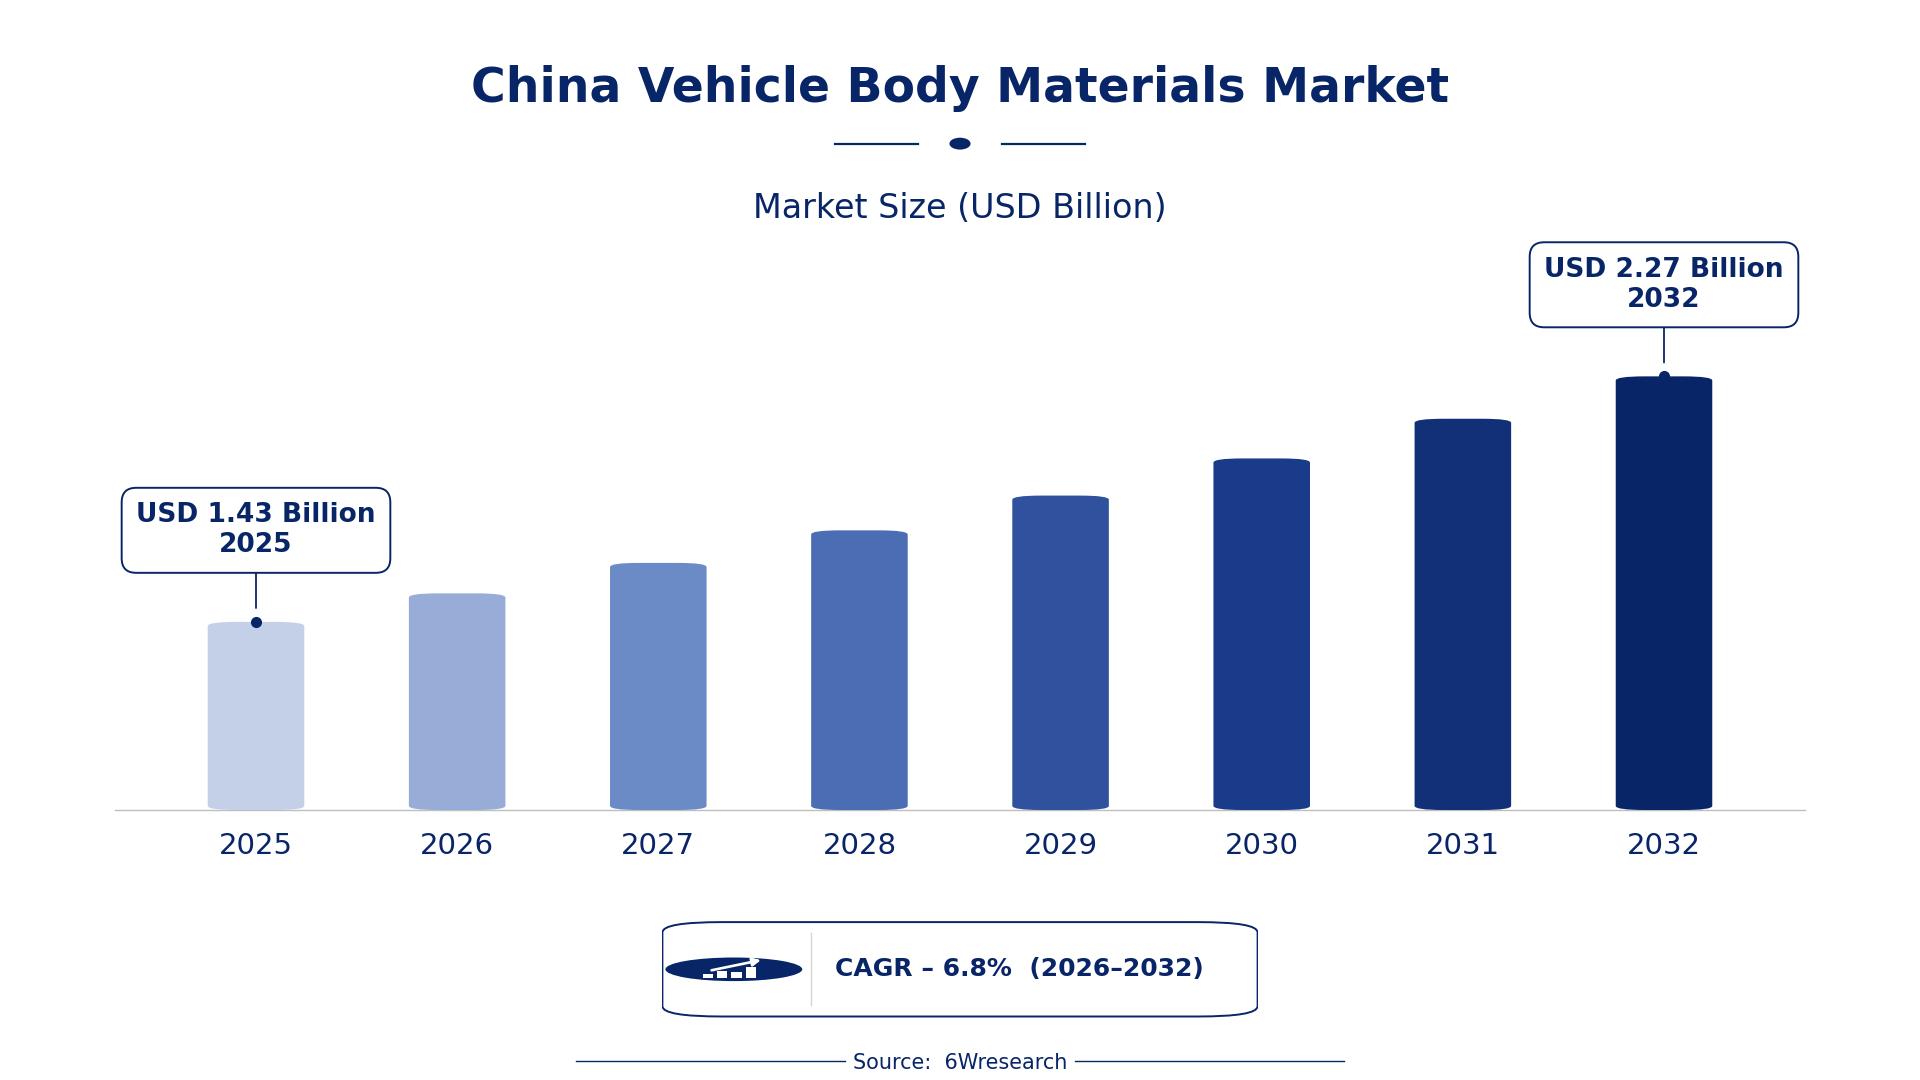
According to 6Wresearch internal database and industry insights, the China Vehicle Body Materials Market was valued at USD 1.43 billion in 2025 and is projected to reach USD 2.27 billion by 2032, growing at a CAGR of approximately 6.8% during 2026–2032.
China Vehicle Body Materials Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Body Materials Market |
| Market Size 2025 | USD 1.43 billion |
| Market Size 2032 | USD 2.27 billion |
| Absolute Growth 2025–2032 | USD 0.84 billion |
| CAGR 2026–2032 | 6.8% |
| Peak Annual Growth | 8.8% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | High Strength Steel (40% share) |
| Leading Composition Type, 2025 | Lightweight (39% share) |
| Leading Application Area, 2025 | Passenger Cars (37% share) |
| Leading End User, 2025 | Auto Part Suppliers (38% share) |
| Fastest-Growing Material Type | Aluminum Alloys (9.4% CAGR) |
| Fastest-Growing Application Area | Electric Vehicles (9.1% CAGR) |
| Fastest-Growing End User | EV OEMs (9.6% CAGR) |
| Growing Sector | Electric Vehicles |
| Key End Users | Auto Part Suppliers, EV OEMs, Component Manufacturers |
China Vehicle Body Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
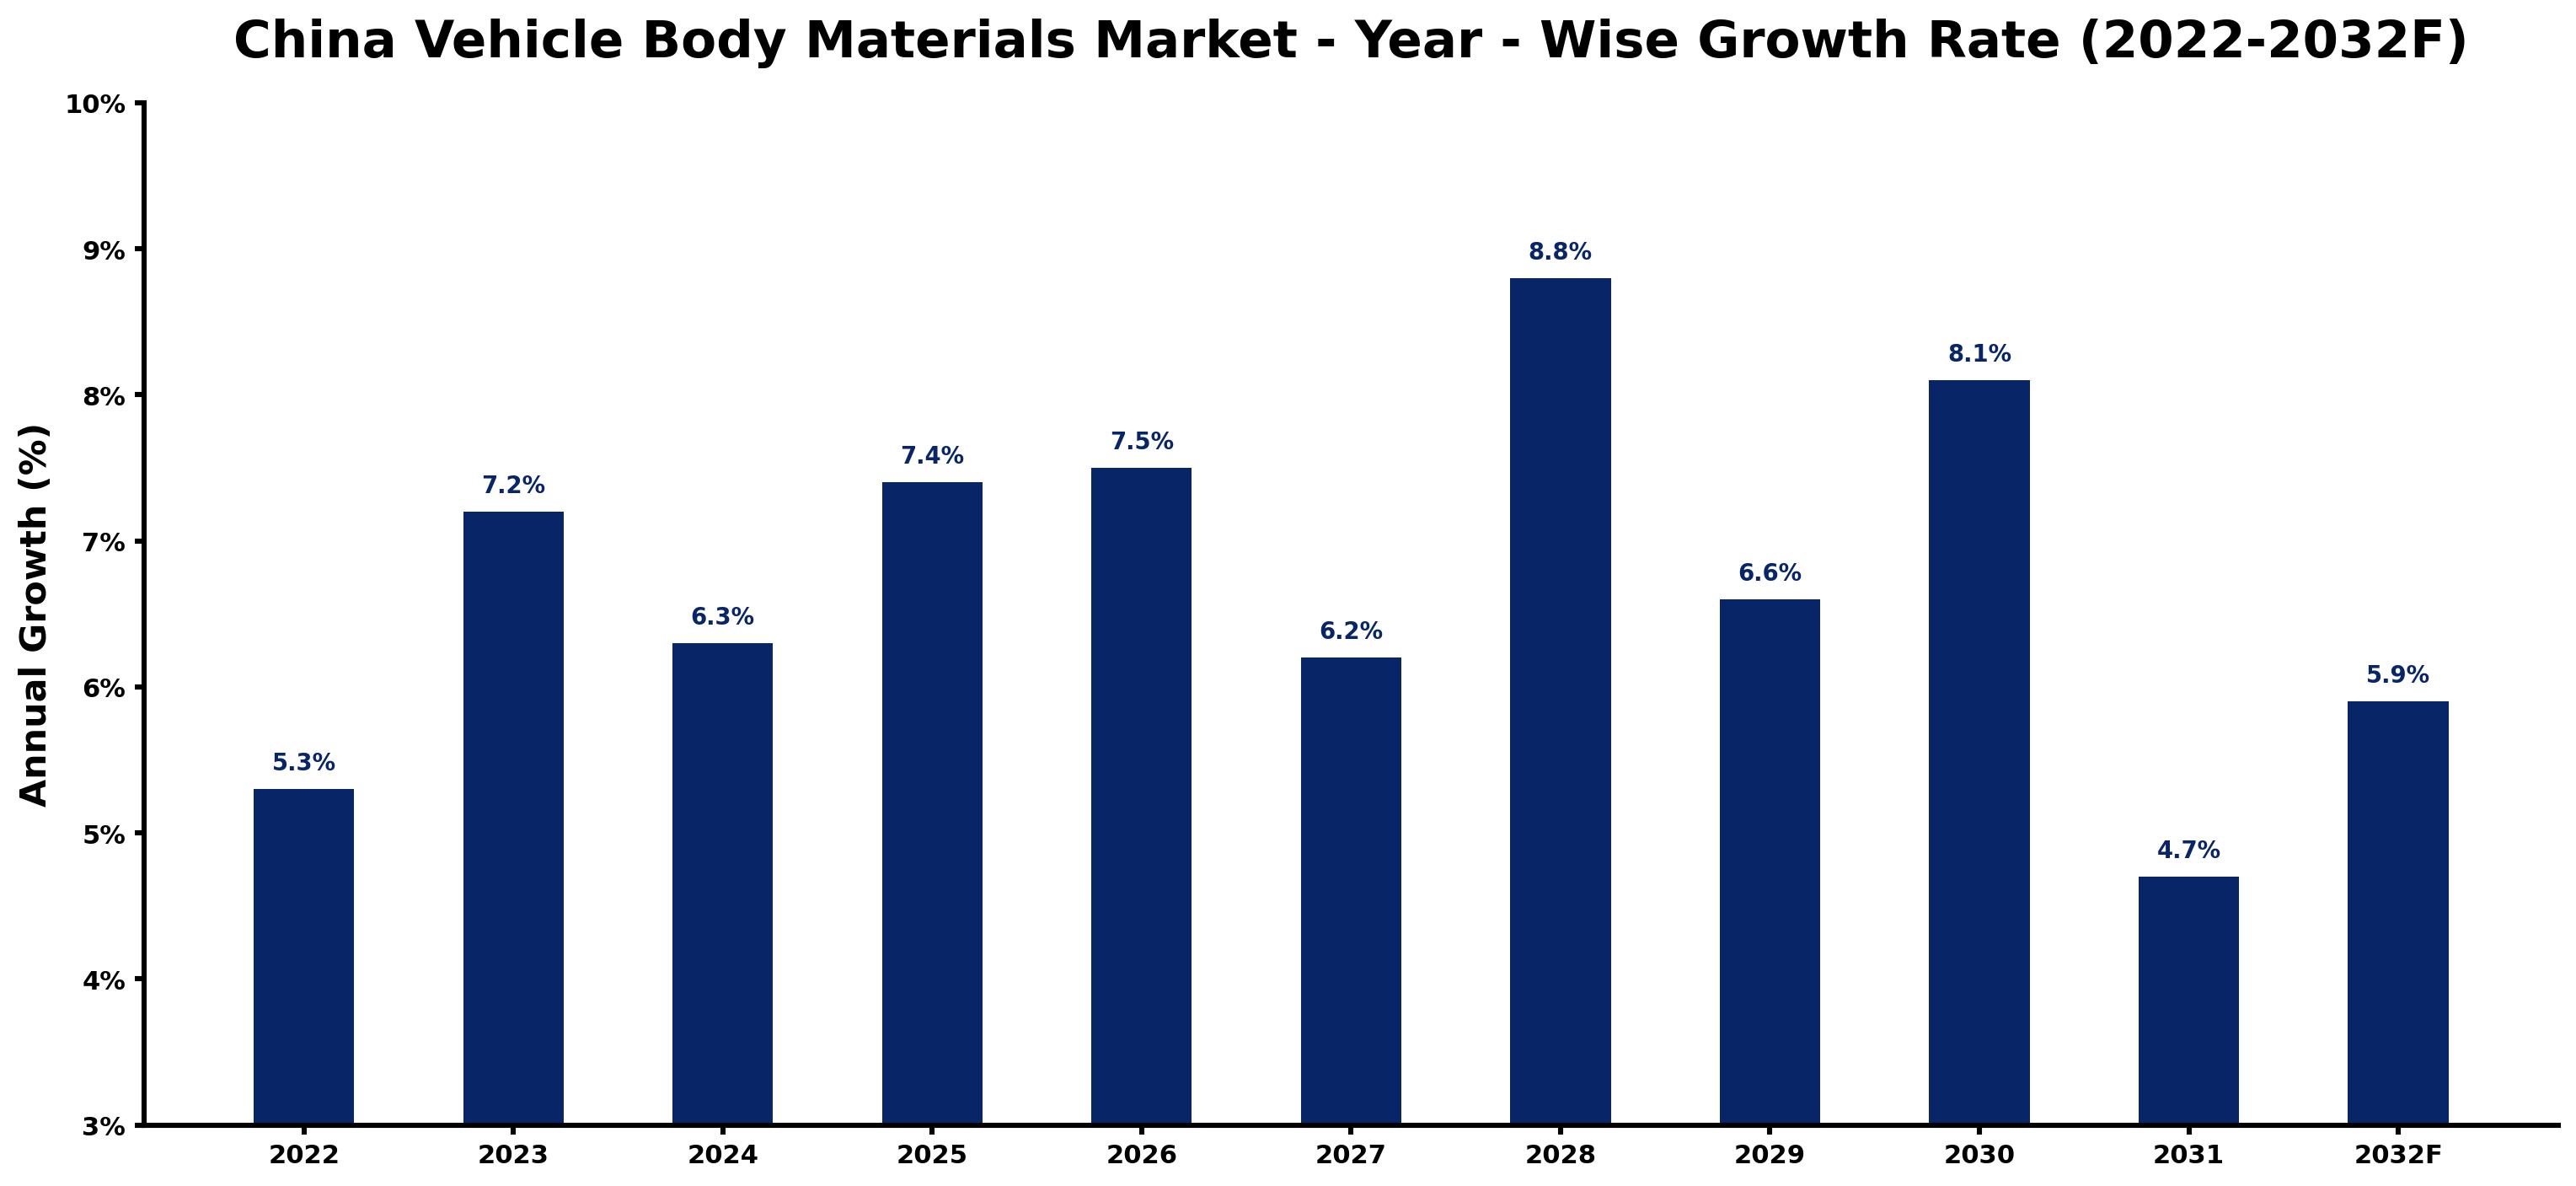
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.3 | The automotive sector employed over 4 million people, driving demand for vehicle body materials. |
| 2023 | 7.2 | Electric vehicles accounted for 20% of new car sales, increasing the need for lightweight materials. |
| 2024 | 6.3 | The growth rate slowed as high strength steel remained dominant in vehicle production. |
| 2025 | 7.4 | Demand surged with the production of over 25 million vehicles, boosting material usage. |
| 2026 | 7.5 | The automotive industry continued to expand, driven by the 'Green Manufacturing Program' encouraging sustainable practices. |
| 2027 | 6.2 | Growth decelerated as the market adjusted to new material standards and regulations. |
| 2028 | 8.8 | The peak growth year saw a rise in electric vehicle production, driving lightweight material demand. |
| 2029 | 6.6 | Demand for aluminum alloys grew as electric vehicle applications expanded, slowing overall growth. |
| 2030 | 8.1 | The market rebounded as new standards for automotive materials were implemented, improving efficiency. |
| 2031 | 4.7 | Growth slowed as the focus shifted to regulatory compliance and sustainable practices. |
| 2032 | 5.9 | Demand for lightweight materials is projected to rise as electric vehicle sales continue to increase. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Body Materials Market Synopsis
Vehicle Body Materials in China encompass metals and composites used in vehicle frames and panels, manufactured through casting, forging, and molding. These materials enhance strength, reduce weight, and improve fuel efficiency. The China Vehicle Body Materials Market is expanding due to strong demand from domestic manufacturers and exports, particularly driven by the production of over 25 million vehicles in 2022. The transition towards electric vehicles is further increasing the demand for lightweight materials, supported by initiatives like 'Green Manufacturing Program' promoting sustainability.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising production of electric vehicles | Driver | High | Aluminum Alloys |
| Increased focus on fuel efficiency | Driver | High | Lightweight |
| Growing demand for sustainable materials | Opportunity | High | Thermoplastic Polymers |
| Expansion of automotive production hubs | Opportunity | Medium | Passenger Cars |
| High costs of advanced materials | Restraint | High | Carbon Fiber Composites |
| Regulatory compliance costs | Restraint | Medium | High Strength Steel |
| Supply chain disruptions | Challenge | High | Aluminum Alloys |
| Technological limitations in material production | Challenge | Medium | Thermoplastic Polymers |
Evaluation of Drivers in China Vehicle Body Materials Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles drives demand for lightweight materials. | Aluminum Alloys | Electric vehicles accounted for 20% of new car sales in 2022, boosting aluminum alloy usage. |
| The push for improved fuel efficiency leads to higher demand for lightweight materials. | Lightweight | Standards from the Ministry of Industry and Information Technology promote lightweight materials. |
| The automotive industry's expansion supports the need for diverse body materials. | High Strength Steel | China produced over 25 million vehicles in 2022, increasing high strength steel usage. |
| Sustainable manufacturing practices are driving the adoption of new materials. | Thermoplastic Polymers | The Green Manufacturing Program encourages the use of sustainable materials in automotive production. |
| The rise of performance vehicles increases the demand for advanced materials. | Carbon Fiber Composites | High-performance applications are becoming more common, driving the need for carbon fiber. |
Market growth in China for Vehicle Body Materials rests on the rising production of electric vehicles, increased focus on fuel efficiency, and the automotive industry's ongoing expansion. In 2022, electric vehicles accounted for 20% of new car sales, boosting aluminum alloy usage. The push for improved fuel efficiency has led to a greater demand for lightweight materials, driven by standards promoting their adoption. The production of over 25 million vehicles in 2022 has also increased the usage of high strength steel. Sustainable practices are driving the adoption of thermoplastic polymers in automotive applications, broadening material diversity.
Evaluation of Restraints in China Vehicle Body Materials Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced materials limit wider adoption. | Carbon Fiber Composites | The production costs for carbon fiber composites are higher than traditional materials. |
| Regulatory compliance costs can burden manufacturers. | High Strength Steel | Compliance with updated regulations increases operational costs for manufacturers. |
| Supply chain disruptions affect material availability. | Aluminum Alloys | Global supply chain issues have led to shortages in aluminum supply, impacting production timelines. |
| Limited production capacity for advanced materials restricts supply. | Thermoplastic Polymers | Manufacturers face challenges in scaling up production of thermoplastic polymers. |
| Technological limitations hinder the development of new materials. | Lightweight | Innovation in lightweight materials is often slow due to technological constraints. |
China Vehicle Body Materials Market Challenges
The China Vehicle Body Materials Market encounters regulatory hurdles that slow the approval process for new materials, costing manufacturers up to six months in time-to-market. Buyers face rising costs as demand for high strength steel, which constitutes around 40% of vehicle body materials, outstrips supply, leading to a 10% increase in production expenses. Supply chain disruptions often arise from reliance on specific regions like Jiangsu, where local production issues can impact material availability for over 4 million automotive workers. Technological advancements in lightweight materials are not keeping pace, limiting innovation and competitiveness for producers in this market.
Trends in the China Vehicle Body Materials Market
Below mentioned are some of the trends shaping the China Vehicle Body Materials Market growth.
- Shift towards Lightweight Materials in Jiangsu: Jiangsu province is experiencing a transition towards lightweight materials in automotive production, driven by the 'Automotive Industry Development Plan (2021-2025)'. This initiative aims to improve vehicle efficiency, with lightweight materials projected to grow by 15% by 2025.
- Growth of Electric Vehicle Applications: The rise of electric vehicles is leading to increased use of aluminum alloys, with a projected growth of 15% by 2025. This trend is reshaping material requirements in the automotive sector.
- Regulatory Changes Promoting Sustainability: New regulations from the Ministry of Ecology and Environment are promoting lightweight materials to improve vehicle efficiency. These changes are expected to drive demand for new materials in the automotive industry.
- Expansion of Manufacturing Standards: The introduction of the National Standard GB/T 15000.1-2018 is improving safety and performance in automotive materials. This standard is expected to influence material selection and usage in vehicle production.
Investment Opportunities in the China Vehicle Body Materials Market
Some of the investment opportunities in the China Vehicle Body Materials Market are mentioned below.
- Investment in Lightweight Materials: With electric vehicles projected to account for 25% of new car sales by 2025, there is an opportunity to invest in lightweight materials. Auto part suppliers are increasingly seeking partnerships to meet this demand.
- Collaboration with Local Manufacturers: Now is an ideal time for foreign companies to establish joint ventures with local manufacturers in Jiangsu province. This approach can facilitate access to the growing automotive market and improve material supply chains.
- Focus on Sustainable Material Production: The Green Manufacturing Program encourages investment in sustainable materials. Component manufacturers are looking to adopt greener practices, creating opportunities for suppliers of eco-friendly materials.
- Development of Advanced Material Technologies: Investment in research and development of advanced materials is essential. The automotive industry is seeking new solutions to improve vehicle performance, particularly in electric vehicle production.
Government Initiatives in the China Vehicle Body Materials Market
The 'Automotive Industry Development Plan (2021-2025)' launched by the Ministry of Industry and Information Technology aims to promote lightweight vehicle materials. This plan encourages manufacturers to adopt new technologies and materials to improve efficiency and reduce emissions. By setting clear targets, the government is facilitating the transition towards more sustainable automotive production. The emphasis on lightweight materials is projected to drive innovation and investment in the sector, benefiting both producers and consumers.
The National Development and Reform Commission initiated the 'Green Manufacturing Program' in 2020, which provides funding for projects that promote sustainable practices in manufacturing. This program supports the development of lightweight materials, encouraging manufacturers to invest in eco-friendly alternatives. The agency also oversees the implementation of standards that ensure compliance with environmental regulations, helping to streamline the approval process for new materials.
Future Insight of the China Vehicle Body Materials Market
The China Vehicle Body Materials Market is set to evolve by 2032, driven by the increasing adoption of aluminum alloys in electric vehicles, projected to grow by 15% by 2025. Standards established by the Ministry of Industry and Information Technology will push manufacturers towards lightweight materials, improving fuel efficiency. The 'Made in China 2025' initiative will encourage advanced manufacturing practices, prompting suppliers to innovate. As electric vehicles accounted for 20% of new car sales in 2022, this trend is expected to significantly elevate demand for modern vehicle body materials.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Material Type – High Strength Steel Dominated, Aluminum Alloys Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, the largest material type category in 2025 was High Strength Steel, with a 40% share of total revenue. High strength steel holds the largest share in the China Vehicle Body Materials Market due to its critical role in providing structural integrity for vehicles. This material is essential for manufacturers aiming to meet safety standards while ensuring durability in their vehicle constructions. The quickest growth will come from Aluminum Alloys, forecast to expand at a CAGR of 9.4% between 2026 and 2032. Aluminum alloys are experiencing rapid growth, particularly in electric vehicle applications, where their lightweight properties are crucial for improving efficiency. The projected 15% increase in this segment by 2025 highlights a significant shift towards these materials in modern vehicle designs. Suppliers should focus on developing aluminum alloys to align with the automotive industry's transition towards lightweight and efficient vehicles.
By Composition Type – Lightweight Dominated and Is Expected to Record the Fastest Growth
Lightweight accounted for a 39% market share by composition type in 2025. Lightweight materials dominate the market share as they are essential for enhancing fuel efficiency in vehicles, a primary concern for manufacturers in China. The emphasis on reducing vehicle weight aligns with national standards that promote the use of advanced materials. Lightweight is also forecast to expand faster than any other category, at a CAGR of 8.4% over 2026–2032. The lightweight segment is also the fastest-growing, driven by the automotive industry's increasing demand for improved fuel efficiency and compliance with regulatory standards. This dual role underscores the importance of lightweight materials in shaping future vehicle designs. Buyers should prioritise lightweight materials to ensure compliance with industry standards and improve overall vehicle performance.
By Application Area – Passenger Cars Dominated, Electric Vehicles Expected to Grow Fastest
In 2025, Passenger Cars led the application area split with a 37% share. Passenger cars account for the largest share of vehicle body materials, serving as the main application area within the automotive sector. The production of over 25 million vehicles in 2022 reflects the strong demand for these materials in this segment. Over 2026–2032, Electric Vehicles are expected to post the fastest growth, at a CAGR of 9.1%. Electric vehicles represent the fastest-growing application area, driven by the need for lightweight materials to enhance efficiency and meet consumer preferences. The 20% share of electric vehicles in new car sales illustrates the increasing momentum of this market trend. Suppliers must adapt their product offerings to cater to the growing demand for materials specifically designed for electric vehicle applications.
By End User – Auto Part Suppliers Dominated, EV OEMs Expected to Grow Fastest
Auto Part Suppliers held a 38% share of the China Vehicle Body Materials Market by end user in 2025. Auto part suppliers hold the largest share in the market as they are key users of vehicle body materials, supplying components to a vast array of manufacturers. Their established relationships with automotive producers ensure consistent demand for these materials. EV OEMs are set to record the highest CAGR in this split, 9.6% over 2026–2032. EV OEMs are the fastest-growing end user segment, reflecting the automotive industry's shift towards electric vehicle production. The focus on sustainability and innovation in this segment is driving rapid changes in material requirements. Suppliers should consider forming strategic partnerships with EV OEMs to capitalise on the growing market for electric vehicle components.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Body Materials Market Outlook
- Market Size of China Vehicle Body Materials Market, 2025
- Forecast of China Vehicle Body Materials Market, 2032
- Historical Data and Forecast of China Vehicle Body Materials Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Body Materials Market Trend Evolution
- China Vehicle Body Materials Market Drivers and Challenges
- China Vehicle Body Materials Price Trends
- China Vehicle Body Materials Porter's Five Forces
- China Vehicle Body Materials Industry Life Cycle
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By High Strength Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Carbon Fiber Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Thermoplastic Polymers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Composition Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Alloyed for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Lightweight for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Reinforced for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Moldable for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Electric Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Sports Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Bumper Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Auto Part Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By EV OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Performance Vehicle Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Materials Market Revenues & Volume By Component Manufacturers for the Period 2022 - 2032F
- China Vehicle Body Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Composition Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Vehicle Body Materials Top Companies Market Share
- China Vehicle Body Materials Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Body Materials Company Profiles
- China Vehicle Body Materials Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Material Type
- High Strength Steel
- Aluminum Alloys
- Carbon Fiber Composites
- Thermoplastic Polymers
By Composition Type
- Alloyed
- Lightweight
- Reinforced
- Moldable
By Application Area
- Passenger Cars
- Electric Vehicles
- Sports Cars
- Bumper Panels
By End User
- Auto Part Suppliers
- EV OEMs
- Performance Vehicle Makers
- Component Manufacturers































