China Vehicle Component Market Size & Growth Rate
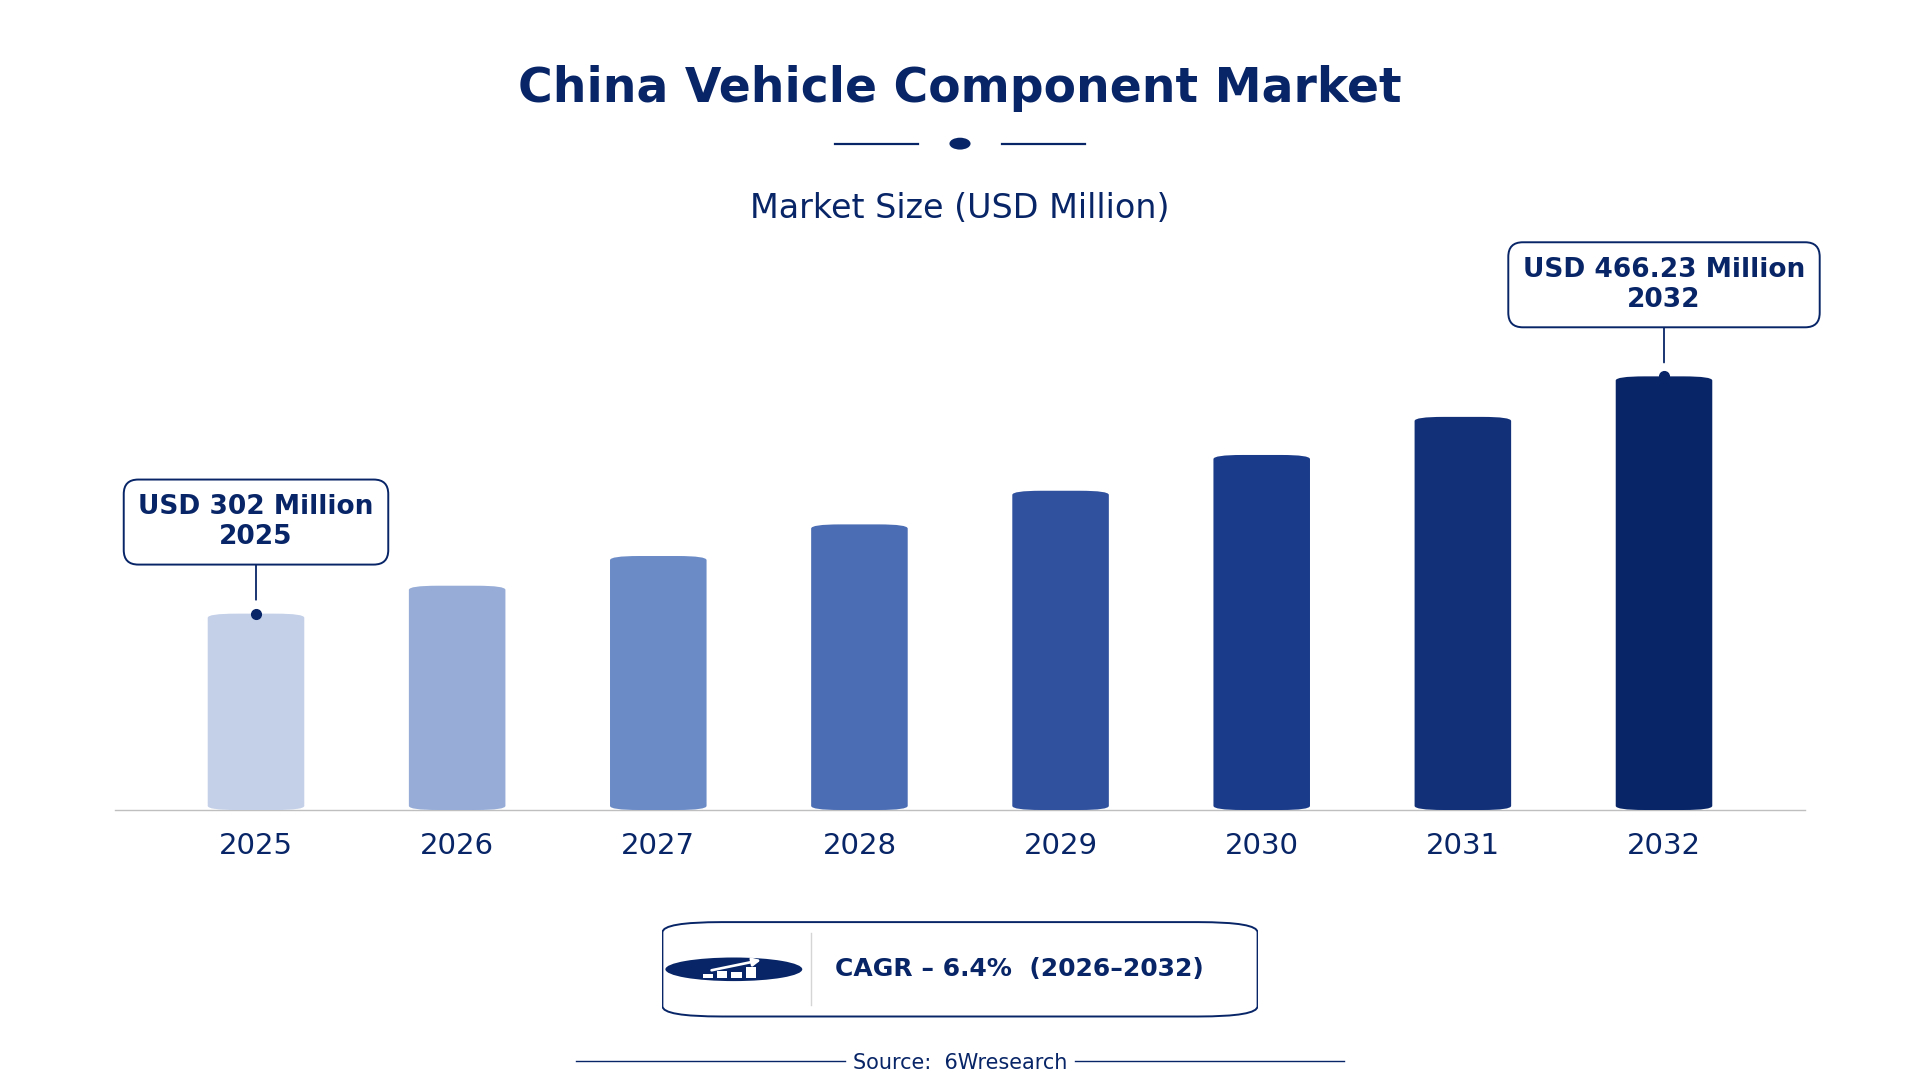
According to 6Wresearch internal database and industry insights, the China Vehicle Component Market was valued at USD 302.0 million in 2025 and is projected to reach USD 466.23 million by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Vehicle Component Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Component Market |
| Market Size 2025 | USD 302.0 million |
| Market Size 2032 | USD 466.23 million |
| Absolute Growth 2025–2032 | USD 164.23 million |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 8.9% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Engine Components (48% share) |
| Leading Application System, 2025 | Powertrain (34% share) |
| Leading Material Type, 2025 | Cast Iron/Steel (50% share) |
| Leading End User, 2025 | Vehicle OEMs (44% share) |
| Fastest-Growing Component Type | Infotainment Modules (8.8% CAGR) |
| Fastest-Growing Application System | Electronics (8.3% CAGR) |
| Fastest-Growing Material Type | Plastics/Electronics (7.4% CAGR) |
| Fastest-Growing End User | Connected Vehicle Providers (7.6% CAGR) |
| Growing Sector | Electronics |
| Key End Users | Powertrain, Chassis, Safety System, Electronics |
China Vehicle Component Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
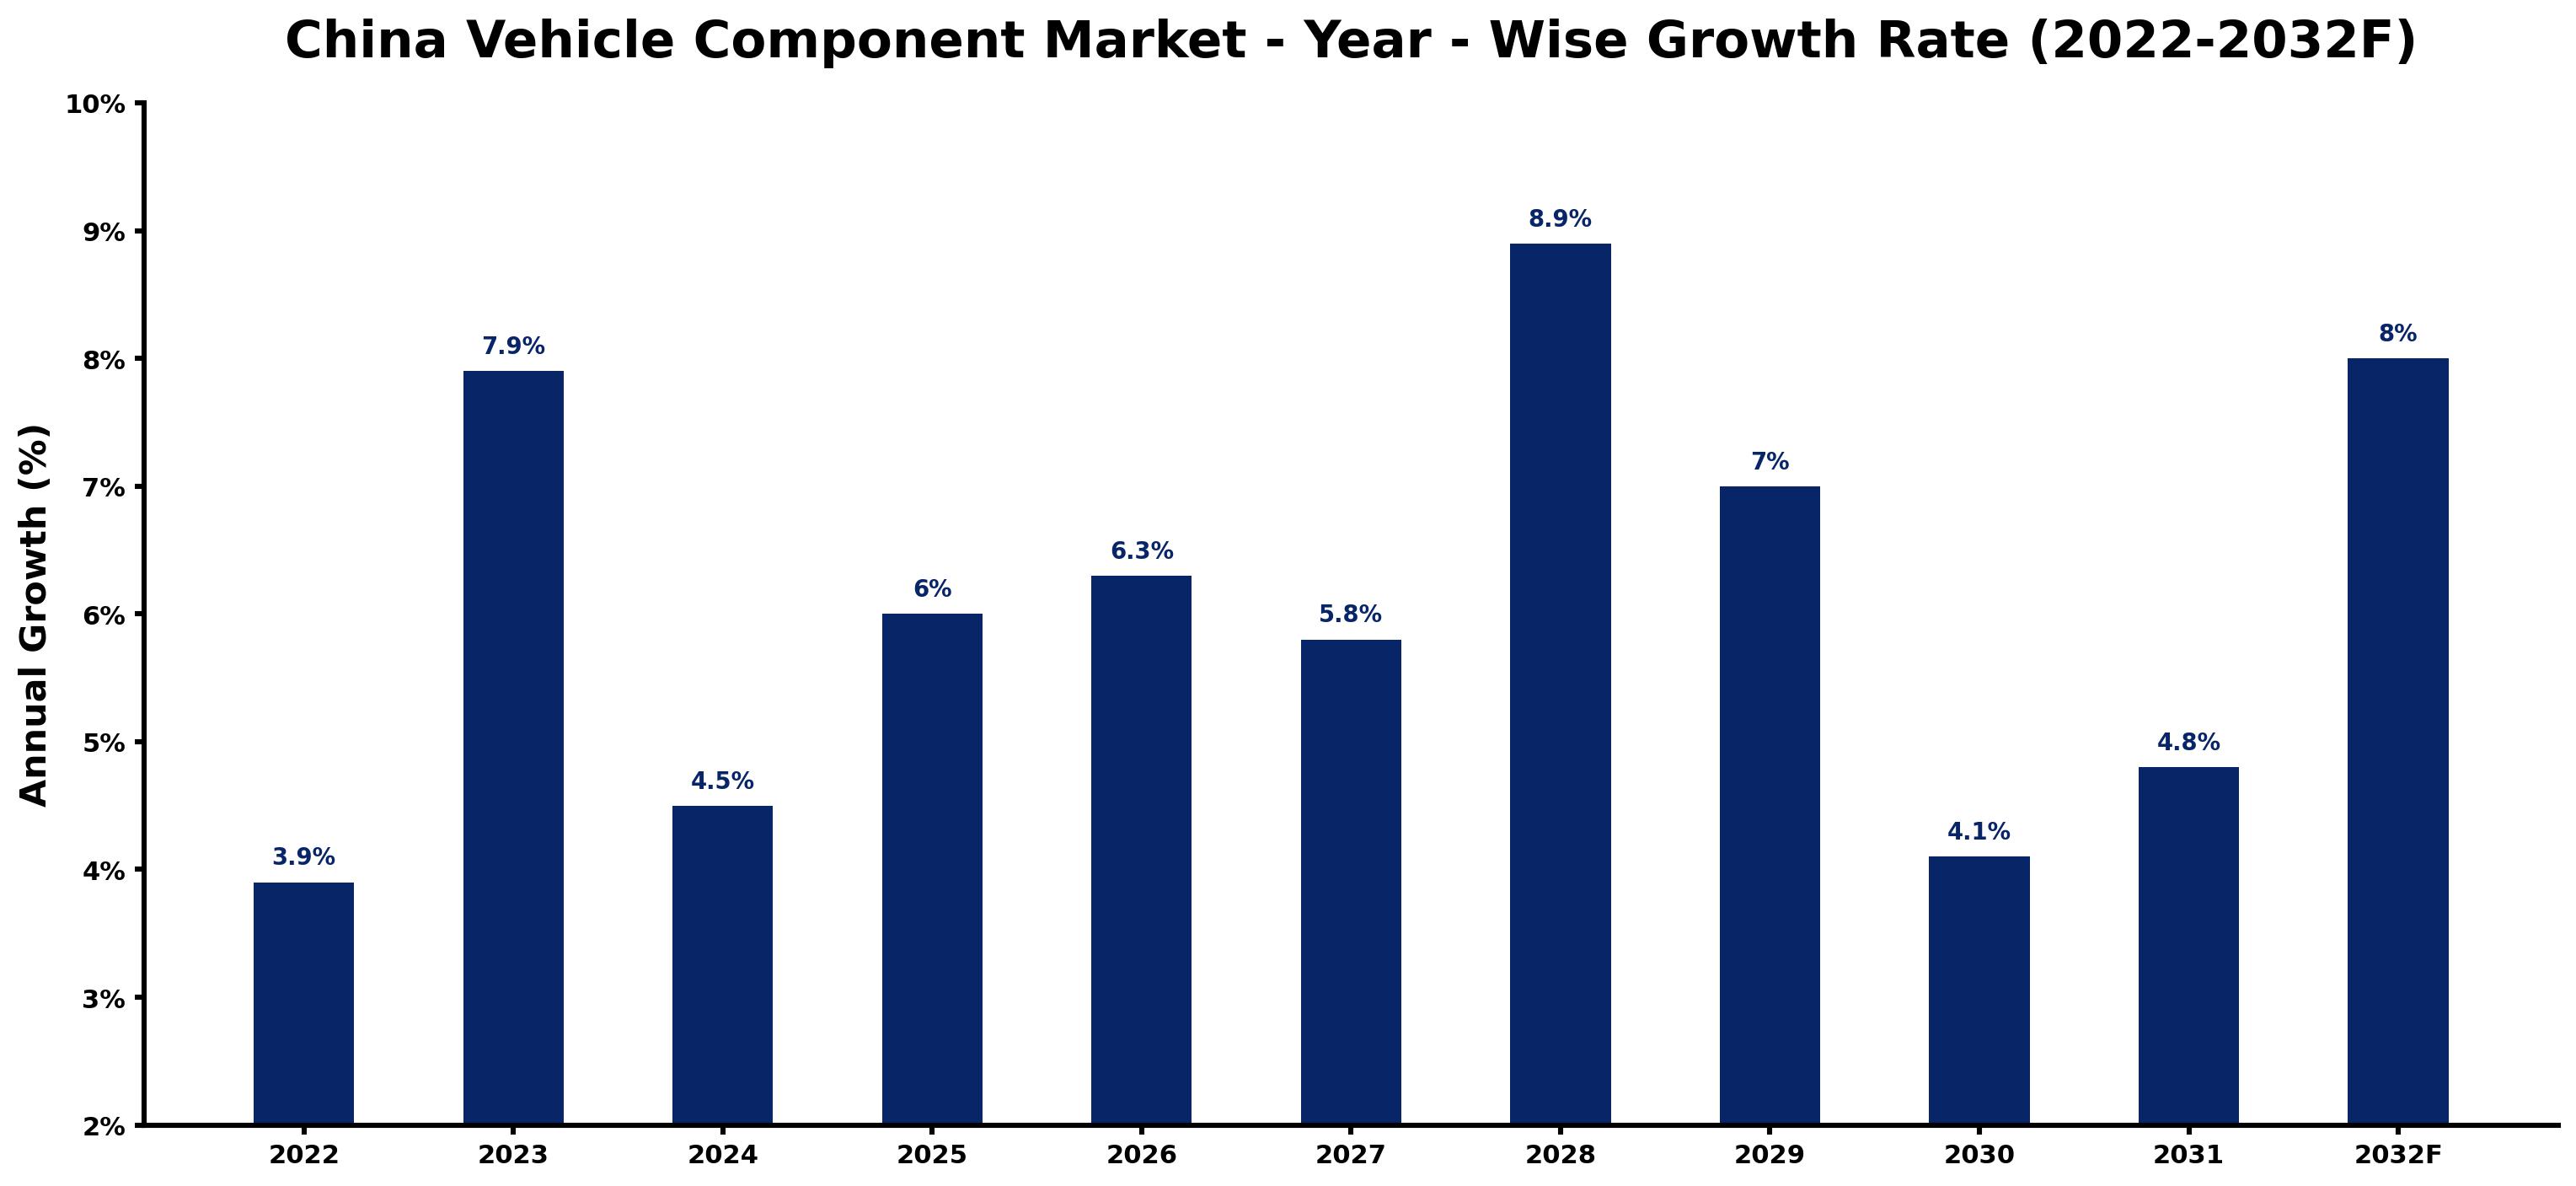
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The automotive sector experienced steady production levels, sustaining demand for components through the 'Automobile Industry Development Plan'. |
| 2023 | 7.9 | Vehicle production surged, driving increased demand for various vehicle components, particularly in the Beijing-Tianjin-Hebei region. |
| 2024 | 4.5 | Demand growth moderated as production faced slight adjustments in response to market conditions and evolving consumer preferences. |
| 2025 | 6.0 | Continued vehicle production growth led to rising requirements for essential components, supported by the 'New Energy Vehicle Industry Development Plan'. |
| 2026 | 6.3 | Technological advancements in vehicles are expected to spur demand for advanced component solutions, particularly in electronics. |
| 2027 | 5.8 | Growth is projected to slow as manufacturers adjust to changing consumer preferences and market conditions in the connected vehicle sector. |
| 2028 | 8.9 | A significant increase in vehicle production will boost demand for key components, especially in the automotive aftermarket. |
| 2029 | 7.0 | Demand growth is expected to decelerate as production levels stabilise after rapid increases in vehicle output. |
| 2030 | 4.1 | Market growth will slow as manufacturers focus on efficiency and cost management while adapting to new standards. |
| 2031 | 4.8 | Increased investment in vehicle production will raise demand for critical components, particularly in the infotainment segment. |
| 2032 | 8.0 | A resurgence in vehicle production is projected to drive component demand significantly, especially for electric vehicles. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Component Market Synopsis
The Vehicle Component Market in China includes essential parts used in vehicle assembly and operation, such as engines, brakes, and electronics. These components are made through processes like casting and forging, enhancing performance and safety. The China Vehicle Component Market is expanding due to rising vehicle production, with around 25 million vehicles produced in 2022. Key demand sources include both OEMs and the aftermarket sector, driven by government initiatives that promote innovation and quality standards in the automotive industry.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising vehicle production and ownership levels drive demand for components. | Driver | High | Engine Components |
| Technological advancements in vehicle systems create opportunities for innovative components. | Driver | High | Electronics |
| The automotive aftermarket is projected to reach a value of 1 trillion yuan by 2025, creating investment opportunities. | Opportunity | High | Aftermarket Retailers |
| Growing demand for connected vehicle technology presents opportunities for suppliers. | Opportunity | High | Connected Vehicle Providers |
| Quality compliance challenges can hinder market entry for new manufacturers. | Restraint | Medium | Brake Assemblies |
| The high cost of advanced materials may restrict production capabilities for some manufacturers. | Restraint | Medium | Suspension Parts |
| Regulatory changes can create uncertainty for manufacturers in the market. | Challenge | Medium | Infotainment Modules |
| Supply chain disruptions can delay component availability for manufacturers. | Challenge | Medium | Powertrain |
Evaluation of Drivers in China Vehicle Component Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production rates boost demand for essential components. | Engine Components | China produced approximately 25 million vehicles in 2022, driving demand for engine components. |
| Technological advancements in vehicle electronics require advanced component solutions. | Electronics | The automotive electronics market in China is projected to grow rapidly, driven by EV adoption and innovation. |
| Rising vehicle ownership levels lead to increased demand for aftermarket parts. | Aftermarket Retailers | China's vehicle ownership reached 300 million units in 2022, increasing aftermarket demand for replacement parts. |
| Government initiatives promote innovation in the automotive sector. | Infotainment Modules | The 'Automobile Industry Development Plan' aims to enhance competitiveness and innovation in 2021. |
| Growing demand for connected vehicle technology drives component innovation. | Connected Vehicle Providers | The connected vehicle market in China was valued at 100 billion yuan in 2022, indicating strong demand. |
Growth in the Vehicle Component market in China comes from rising vehicle production, technological advancements, and increasing vehicle ownership. Approximately 25 million vehicles were produced in 2022, which boosted demand for essential components. The automotive electronics market is expanding as electric vehicle adoption increases, creating further opportunities for suppliers. The connected vehicle market, valued at 100 billion yuan in 2022, indicates strong demand for advanced components.
Evaluation of Restraints in China Vehicle Component Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| A skills shortage limits production capabilities. | Engine Components | The automotive industry employs over 5 million people, yet many lack advanced technical training, affecting production efficiency. |
| Regulatory hurdles can delay product approvals and increase compliance costs. | Electronics | The Ministry of Industry and Information Technology enforces strict automotive standards, complicating the approval process for new components. |
| Technology adoption is lagging, particularly in the connected vehicle sector. | Connected Vehicle Providers | The connected vehicle market was valued at 100 billion yuan in 2022, indicating limited innovation and competitiveness in this area. |
| Fluctuating demand from OEMs creates uncertainty for manufacturers. | Aftermarket Retailers | Variable production schedules force component manufacturers to manage excess inventory, impacting financial stability. |
| High compliance costs can hinder small manufacturers' market entry. | Infotainment Modules | Strict regulations require significant investment in quality control processes, which can be prohibitive for smaller firms. |
China Vehicle Component Market Challenges
The China Vehicle Component Market faces a skills shortage, as over 5 million workers in the automotive sector often lack advanced training, leading to inefficiencies that increase production costs for manufacturers. Regulatory hurdles arise from strict standards set by the Ministry of Industry and Information Technology, causing delays in product approvals and raising compliance costs for suppliers. Technology adoption is slow, especially in the connected vehicle segment, valued at 100 billion yuan, which hampers innovation and competitiveness for buyers. Demand fluctuations from OEMs create uncertainty, forcing component manufacturers to adjust production schedules frequently, which can lead to excess inventory and financial strain.
Trends in the China Vehicle Component Market
Several trends are reshaping the China Vehicle Component Market; the most important are set out below.
- Shift Towards Electric Vehicle Components: Vehicle OEMs are increasingly focusing on electric vehicle components, as highlighted by the 'New Energy Vehicle Industry Development Plan' (2021-2035). This initiative promotes the development of electric vehicle components, with the automotive electronics market expected to grow rapidly, reaching new heights.
- Integration of Smart Technologies in Vehicles: Connected vehicle providers are adopting advanced technologies to enhance functionality. The market for connected vehicles was valued at 100 billion yuan in 2022, indicating a strong shift towards smart components in automotive design.
- Focus on Lightweight Materials: Manufacturers are prioritising lightweight materials like plastics and composites to improve fuel efficiency. The automotive industry is expected to see a rise in the use of plastics and electronics, with a CAGR of 7.4% in the coming years.
- Increased Emphasis on Safety Features: Vehicle OEMs are enhancing safety systems in response to consumer demand. The automotive sector is focusing on integrating advanced safety technologies, supported by the 'Automotive Industry Standardization Work Plan' launched in 2022.
Investment Opportunities in the China Vehicle Component Market
Investors looking at the China Vehicle Component Market should consider the following areas.
- Aftermarket Retailers Seeking Quality Components: Aftermarket retailers are looking for high-quality replacement parts to meet consumer demands. The automotive aftermarket in China is projected to reach a value of 1 trillion yuan by 2025, presenting opportunities for suppliers to provide quality components.
- Investment in Electric Vehicle Components: Suppliers should focus on developing electric vehicle components to align with market trends. The 'New Energy Vehicle Industry Development Plan' (2021-2035) encourages investment in advanced technologies, creating a demand for innovative products.
- Expansion in the Beijing-Tianjin-Hebei Region: The Beijing-Tianjin-Hebei region is a key area for automotive production and component supply. Suppliers can enter this market through partnerships with local manufacturers or by obtaining necessary certifications to meet regional standards.
- Growth in Connected Vehicle Technology: Connected vehicle providers are expanding their offerings to include smart technologies. The connected vehicle market, valued at 100 billion yuan in 2022, presents opportunities for suppliers to innovate and meet increasing consumer demand.
Government Initiatives in the China Vehicle Component Market
The 'Automobile Industry Development Plan' by the National Development and Reform Commission, launched in 2021, aims to boost innovation and competitiveness in the automotive sector. This plan encourages manufacturers to invest in advanced technologies and improve production processes, aligning with national standards. Additionally, the 'New Energy Vehicle Industry Development Plan' (2021-2035) promotes the development of electric vehicle components, further supporting innovation in the sector. These measures enhance the industry's capacity to meet growing demand for modern vehicle components.
The 'Automotive Industry Standardization Work Plan' by the State Administration for Market Regulation, initiated in 2022, focuses on improving component quality standards. This scheme ensures that manufacturers meet regulatory requirements, allowing buyers to ensure the reliability and safety of components. The Ministry of Industry and Information Technology oversees compliance with these standards, helping producers align their products with national expectations. Furthermore, the 'Made in China 2025' initiative supports the adoption of advanced manufacturing technologies, fostering a competitive environment for local manufacturers.
Future Insight of the China Vehicle Component Market
The China Vehicle Component Market is set to evolve by 2032, driven by several key factors. The 'Automobile Industry Development Plan' launched in 2021 will promote innovation and investment in new technologies. Vehicle ownership, which reached 300 million units in 2022, will continue to fuel demand for components, particularly in the automotive electronics sector as electric vehicles become more prevalent. The automotive aftermarket is projected to reach 1 trillion yuan by 2025, offering suppliers new opportunities to cater to changing consumer preferences.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Engine Components Dominated, Infotainment Modules Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Engine Components accounted for a 48% market share by component type in 2025. Engine components lead the China Vehicle Component Market because they are essential for the operation of vehicles. With approximately 25 million vehicles produced in 2022, the demand for reliable engine components is crucial for manufacturers to ensure optimal performance. Over 2026–2032, Infotainment Modules are expected to post the fastest growth, at a CAGR of 8.8%. Infotainment modules are rapidly gaining traction as they become vital to the modern vehicle experience, driven by consumer preferences for advanced technology. The connected vehicle market, valued at 100 billion yuan, significantly propels this growth. Suppliers should prioritise the development of innovative infotainment solutions to cater to the increasing demand in the automotive sector.
By Application System – Powertrain Dominated, Electronics Expected to Grow Fastest
In 2025, Powertrain led the application system split with a 34% share. Powertrain systems command the largest market share as they are fundamental for vehicle propulsion, making them indispensable in vehicle manufacturing. The automotive industry employs over 5 million people, underscoring the importance of powertrain components in this sector. Electronics is set to record the highest CAGR in this split, 8.3% over 2026–2032. Electronics are witnessing the fastest growth, fuelled by the rising integration of technology in vehicles. The expansion of the automotive electronics market is closely linked to the growing adoption of electric vehicles across China. Buyers should focus on sourcing advanced electronic components to improve vehicle functionality and meet evolving consumer expectations.
By Material Type – Cast Iron/Steel Dominated, Plastics/Electronics Expected to Grow Fastest
With a 50% revenue share in 2025, Cast Iron/Steel was the largest material type category. Cast iron and steel dominate the market due to their strength and durability, which are crucial in vehicle construction. These materials play a vital role in ensuring the longevity and reliability of various vehicle components, enhancing overall vehicle performance. Plastics/Electronics is projected to grow fastest, at a CAGR of 7.4% during 2026–2032. Plastics and electronics are experiencing rapid growth as they are widely utilised for lightweight components, essential for improving vehicle efficiency. The automotive industry's shift towards sustainability and performance drives this trend. Suppliers must adapt to the rising demand for lightweight materials to maintain competitiveness in the vehicle component market.
By End User – Vehicle OEMs Dominated, Connected Vehicle Providers Expected to Grow Fastest
The largest end user category in 2025 was Vehicle OEMs, with a 44% share of total revenue. Vehicle OEMs account for the largest share in the market as they are the primary manufacturers responsible for assembling vehicles. The reported increase in automotive production highlights the critical role OEMs play in driving demand for components. The quickest growth will come from Connected Vehicle Providers, forecast to expand at a CAGR of 7.6% between 2026 and 2032. Connected vehicle providers are rapidly growing, reflecting the industry's shift towards technology integration in vehicles. The automotive aftermarket is projected to reach a value of 1 trillion yuan by 2025, emphasising the significance of this segment. Suppliers should align their strategies with the needs of connected vehicle providers to capitalise on expanding market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Component Market Outlook
- Market Size of China Vehicle Component Market, 2025
- Forecast of China Vehicle Component Market, 2032
- Historical Data and Forecast of China Vehicle Component Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Component Market Trend Evolution
- China Vehicle Component Market Drivers and Challenges
- China Vehicle Component Price Trends
- China Vehicle Component Porter's Five Forces
- China Vehicle Component Industry Life Cycle
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Engine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Suspension Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Infotainment Modules for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Brake Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Application System for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Powertrain for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Chassis for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Safety System for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Cast Iron/Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Forged Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Plastics/Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Composite/Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Internal Combustion OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Aftermarket Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Connected Vehicle Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Component Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- China Vehicle Component Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Application System
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By End User
- China Vehicle Component Top Companies Market Share
- China Vehicle Component Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Component Company Profiles
- China Vehicle Component Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Component Type
- Engine Components
- Suspension Parts
- Infotainment Modules
- Brake Assemblies
By Application System
- Powertrain
- Chassis
- Electronics
- Safety System
By Material Type
- Cast Iron/Steel
- Forged Steel
- Plastics/Electronics
- Composite/Metal
By End User
- Internal Combustion OEMs
- Aftermarket Retailers
- Connected Vehicle Providers
- Vehicle OEMs































