China Vehicle Control Components Market Size & Growth Rate
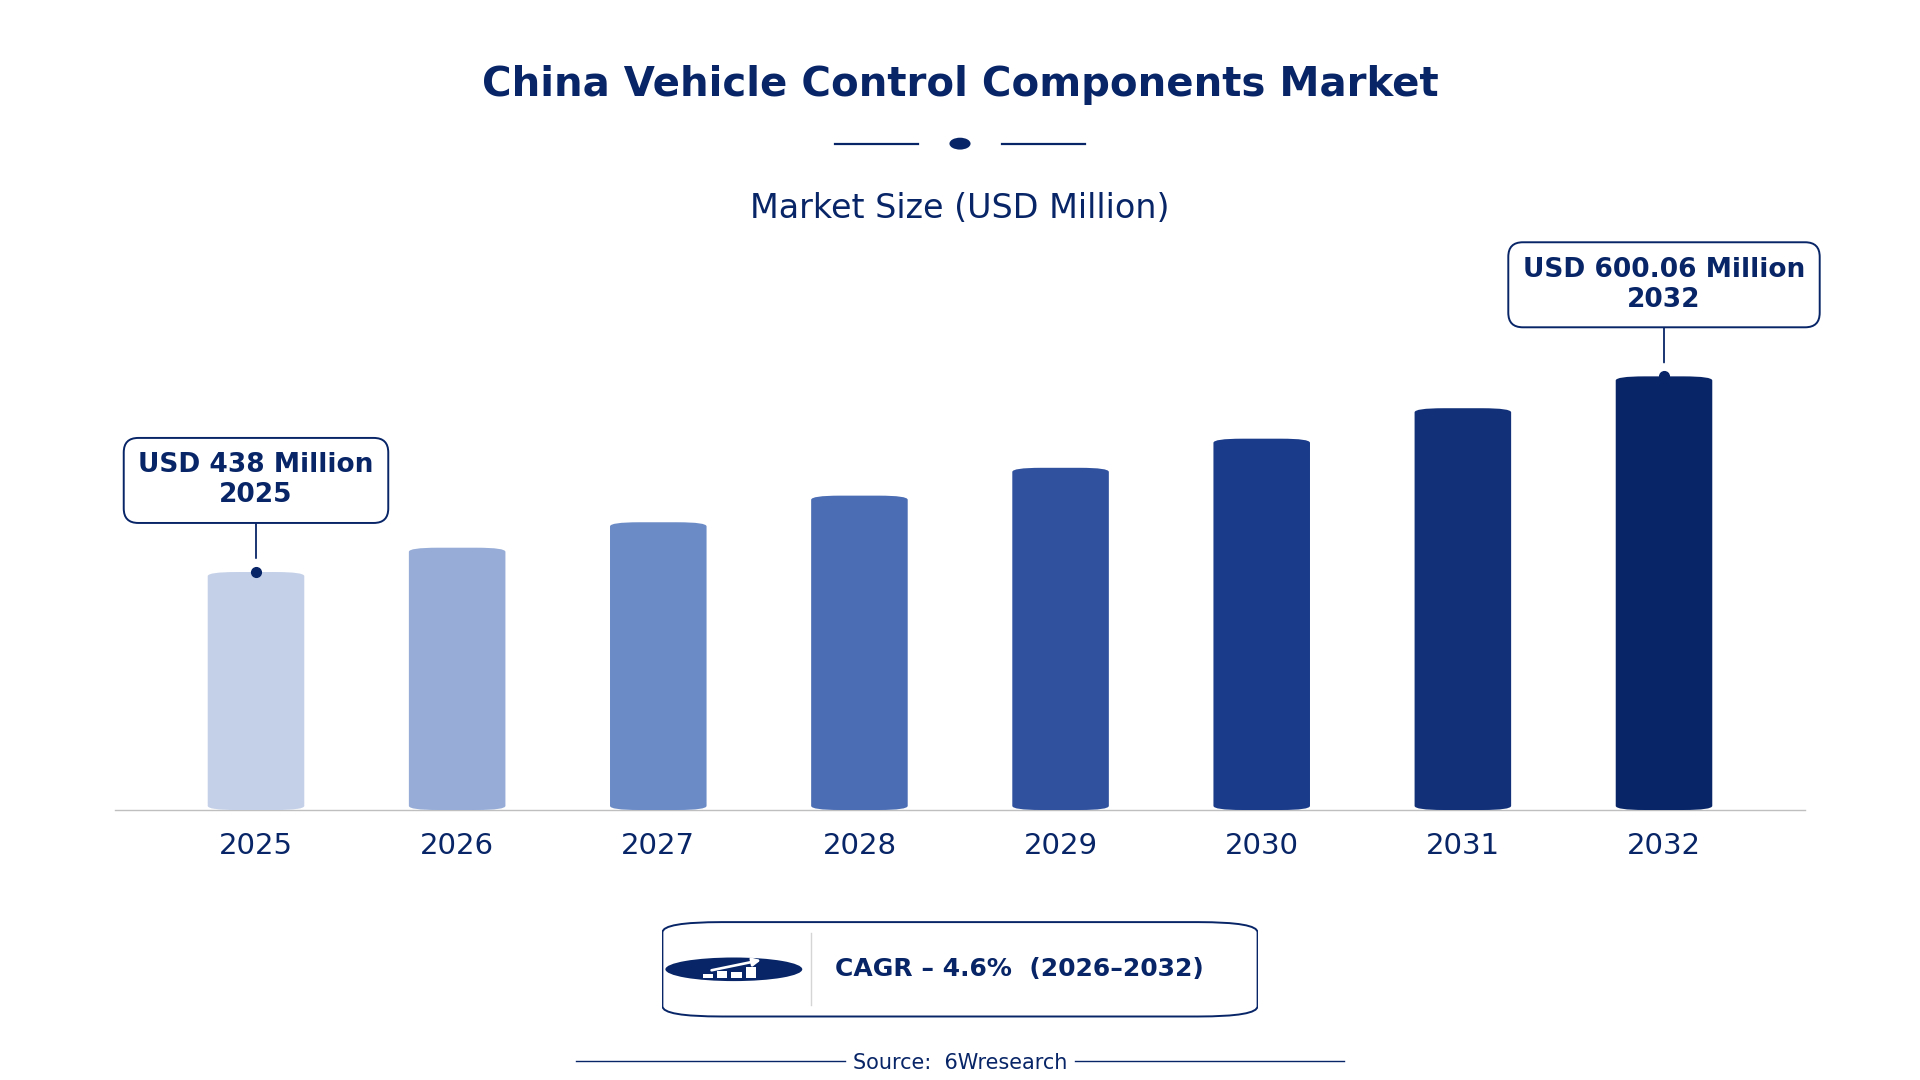
According to 6Wresearch internal database and industry insights, the China Vehicle Control Components Market was valued at USD 438.0 million in 2025 and is projected to reach USD 600.06 million by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
China Vehicle Control Components Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Control Components Market |
| Market Size 2025 | USD 438.0 million |
| Market Size 2032 | USD 600.06 million |
| Absolute Growth 2025–2032 | USD 162.06 million |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.7% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Pedal Assemblies (46% share) |
| Leading Control Function, 2025 | Driver Input (35% share) |
| Leading Integration Area, 2025 | Footwell Area (41% share) |
| Leading End User, 2025 | Automotive OEMs (40% share) |
| Fastest-Growing Component Type | Levers & Actuators (6.3% CAGR) |
| Fastest-Growing Control Function | Mechanic-to-Electronic (6.8% CAGR) |
| Fastest-Growing Integration Area | Transmission Interface (6.7% CAGR) |
| Fastest-Growing End User | Sports & Utility Vehicles (6.6% CAGR) |
| Growing Sector | Automotive OEMs |
| Key End Users | Automotive OEMs, Component Suppliers, Interior Designers |
China Vehicle Control Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
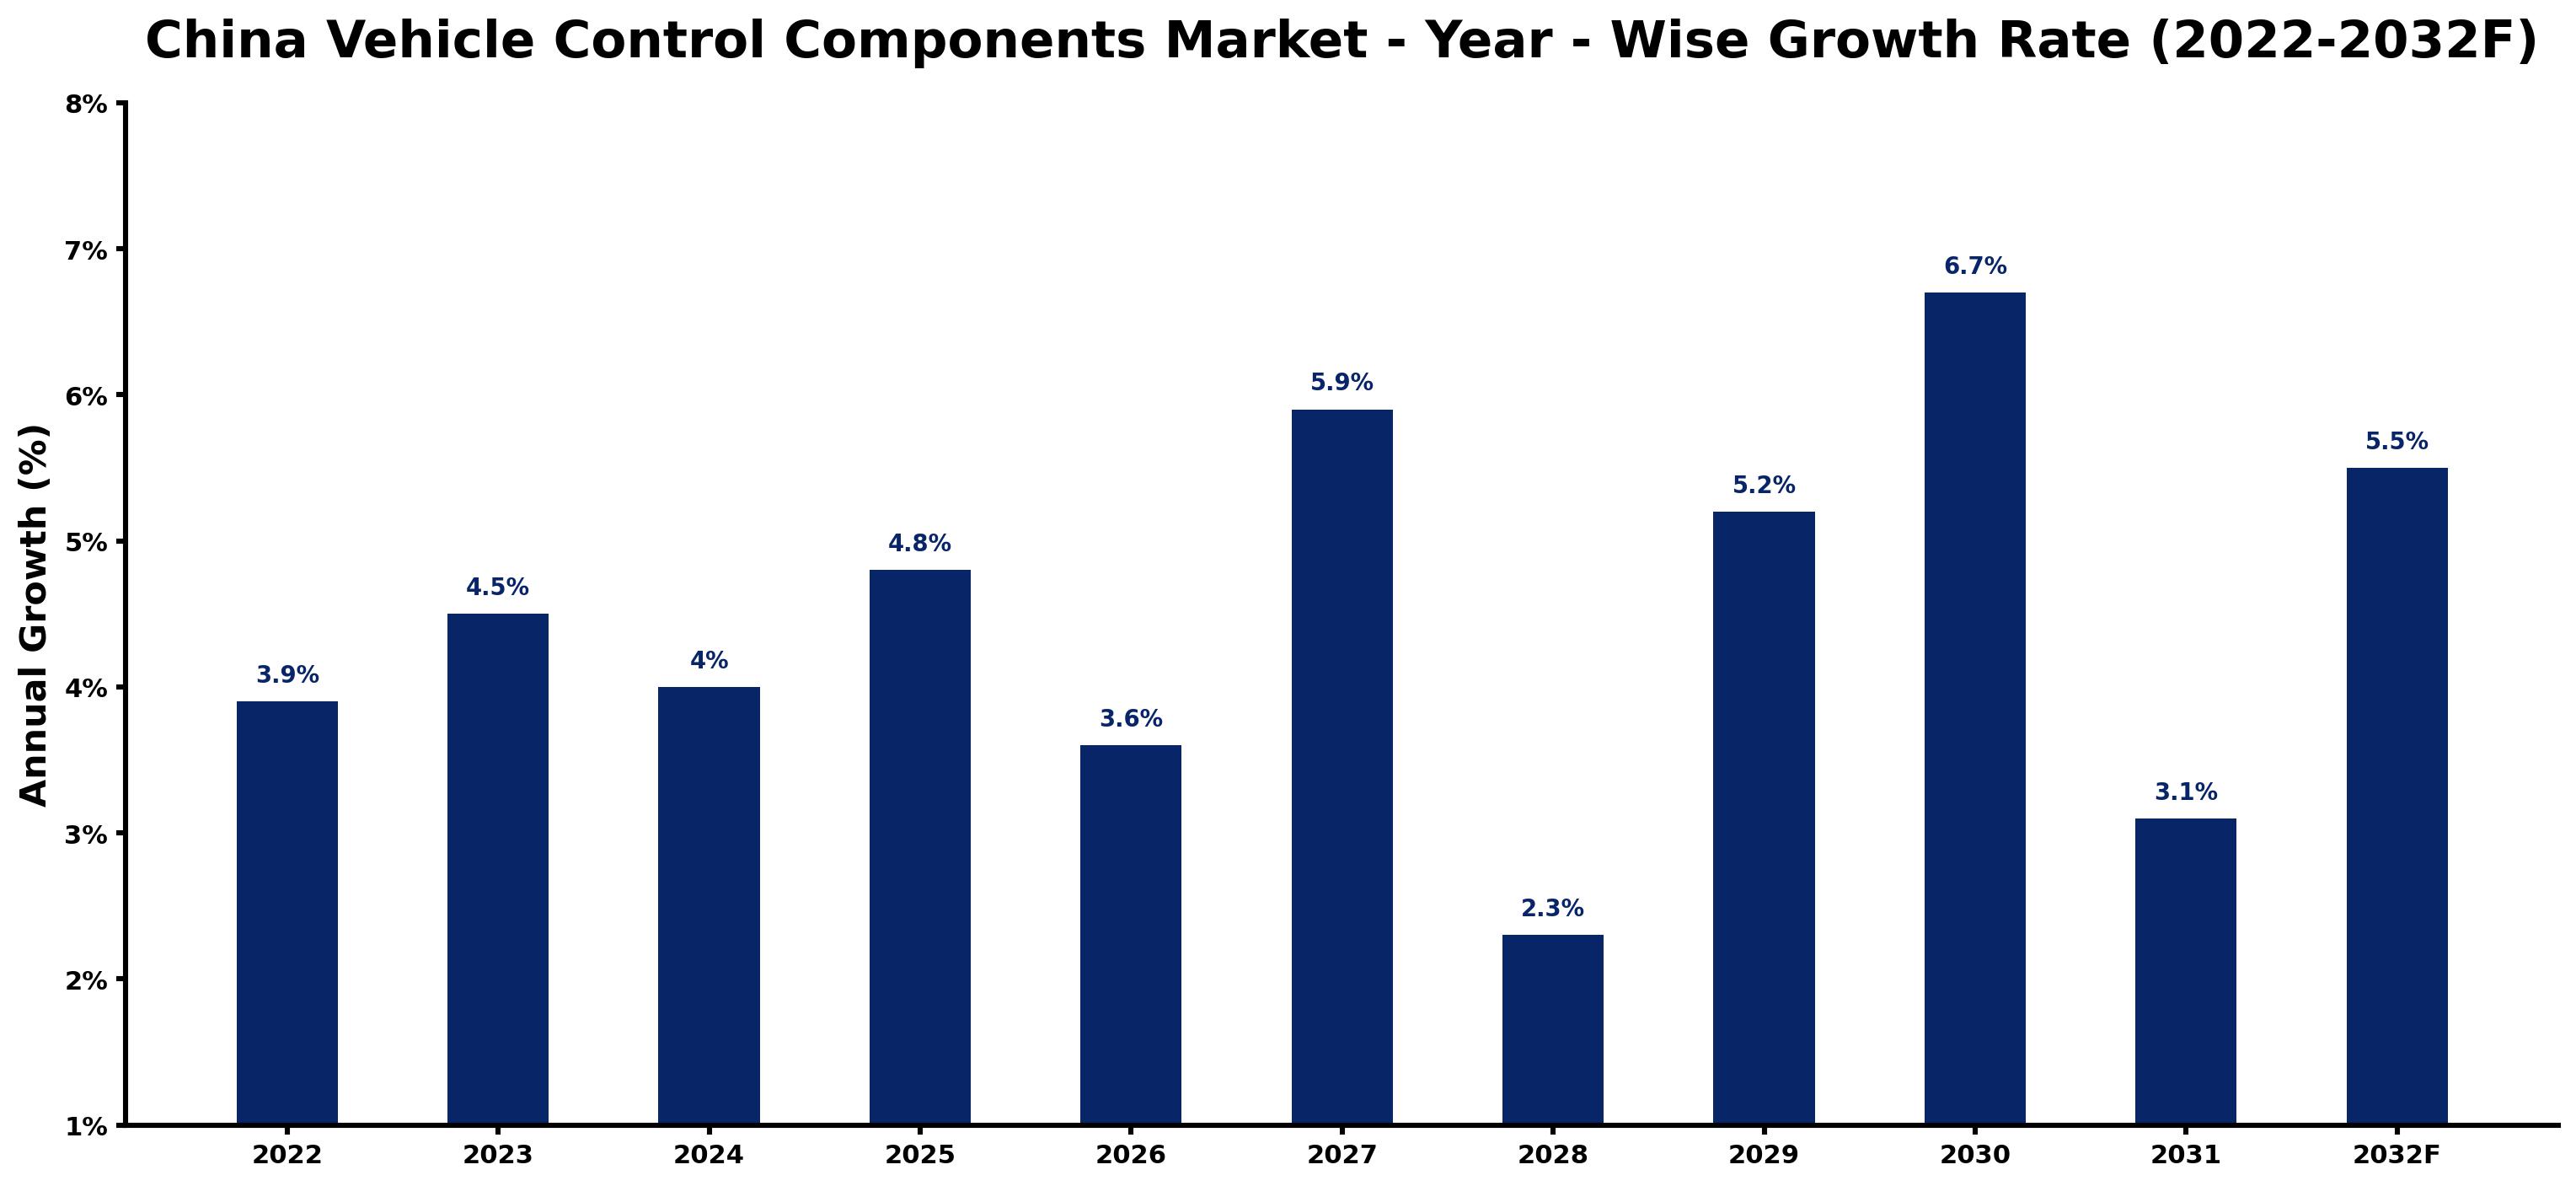
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The market experienced steady growth due to ongoing demand from domestic automotive manufacturers. |
| 2023 | 4.5 | Increased vehicle production in Guangdong province contributed to faster growth than the previous year. |
| 2024 | 4.0 | Growth slowed slightly as manufacturers adjusted to market conditions and supply chain challenges. |
| 2025 | 4.8 | The introduction of new vehicle models drove faster growth as manufacturers sought advanced control components. |
| 2026 | 3.6 | A slowdown occurred as the market faced challenges in adapting to new technologies and standards. |
| 2027 | 5.9 | Growth picked up again due to rising demand for electric vehicles and advanced driver-assistance systems. |
| 2028 | 2.3 | A slowdown was noted as the market adjusted to the evolving automotive landscape and production capabilities. |
| 2029 | 5.2 | The market grew faster as manufacturers invested in innovative vehicle control technologies and systems. |
| 2030 | 6.7 | The peak growth was driven by the increasing adoption of electric vehicles and smart vehicle technologies. |
| 2031 | 3.1 | Growth slowed as the market began to stabilise following rapid advancements in vehicle control systems. |
| 2032 | 5.5 | A rebound in growth is expected as demand for advanced control components continues to rise. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Control Components Market Synopsis
Vehicle Control Components in China include crucial parts that manage vehicle operations, improving driver control and safety. These components are crafted using precision engineering techniques and high-quality materials. The China Vehicle Control Components Market is expanding due to strong demand from automotive OEMs and a growing emphasis on electric vehicles and advanced driver-assistance systems. In 2022, China produced 25 million vehicles, further increasing the need for these components. Government initiatives, such as the 'Smart Vehicle Innovation and Development Strategy', are also driving market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising production of electric vehicles drives demand for advanced control components. | Driver | High | Pedal Assemblies |
| Increased focus on safety standards boosts the need for compliant vehicle control systems. | Driver | High | Driver Input |
| Growing investments in automotive R&D create opportunities for innovative component suppliers. | Opportunity | High | Levers & Actuators |
| The push for smart vehicle technologies opens new markets for control component manufacturers. | Opportunity | High | Footwell Area |
| Supply chain disruptions impact the availability of essential components for manufacturers. | Restraint | High | Rotary Knobs & Switches |
| High production costs limit the competitiveness of local manufacturers in the global market. | Restraint | Medium | Joysticks & Shifters |
| The need for compliance with stringent safety regulations poses challenges for component producers. | Challenge | High | Dashboard Interface |
| Technological advancements require constant updates to manufacturing processes and systems. | Challenge | Medium | Transmission Interface |
Evaluation of Drivers in China Vehicle Control Components Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing vehicle production in China increases demand for control components. | Pedal Assemblies | In 2022, China produced 25 million vehicles, necessitating more control components for assembly. |
| Rising adoption of electric vehicles drives demand for advanced control systems. | Driver Input | The installed base of electric vehicles reached 10 million units by 2023, increasing component needs. |
| Focus on safety standards drives innovation in vehicle control technologies. | Levers & Actuators | ISO 26262 is a key standard, pushing manufacturers to invest in compliant components and systems. |
| Government initiatives promote smart vehicle technologies, boosting market growth. | Footwell Area | The 'Smart Vehicle Innovation and Development Strategy' launched in 2023 supports technology advancements. |
| Increased R&D investments improve product offerings in the vehicle control sector. | Rotary Knobs & Switches | The Beijing Automotive Industry Group invested heavily in R&D for vehicle control technologies, enhancing competitiveness. |
The Vehicle Control Components market in China is growing on the back of rising vehicle production, increasing adoption of electric vehicles, and a focus on safety standards. In 2022, China produced 25 million vehicles, creating demand for control components. The installed base of electric vehicles reached 10 million units by 2023, leading to higher requirements for advanced control systems. Compliance with ISO 26262 drives innovation in vehicle control technologies, prompting manufacturers to invest in compliant components. Increased R&D investments by local automotive groups are improving product offerings, further supporting market growth.
Evaluation of Restraints in China Vehicle Control Components Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely delivery of essential components. | Rotary Knobs & Switches | Recent global supply chain issues have affected the availability of critical parts for manufacturers. |
| High production costs limit the ability of local manufacturers to compete globally. | Joysticks & Shifters | Rising material costs have increased production expenses, affecting competitiveness in international markets. |
| Compliance with stringent safety regulations increases manufacturing complexity. | Dashboard Interface | Adhering to ISO 26262 requires additional testing and certification, raising production costs significantly. |
| Technological advancements necessitate constant updates to manufacturing processes. | Transmission Interface | Keeping up with new technologies requires substantial investment in equipment and training, straining budgets. |
| Limited access to skilled labour affects production efficiency. | Levers & Actuators | The automotive industry employs over 5 million people, but skilled labour shortages persist, impacting output. |
China Vehicle Control Components Market Challenges
The China Vehicle Control Components Market still has to solve a few problems, starting with regulatory hurdles. Compliance with automotive safety standards requires extensive testing, which can delay product launches for manufacturers by up to six months. Rising production costs present another challenge; domestic producers may face a 15% increase in component costs due to escalating raw material prices. Intense competition from international suppliers pressures local companies, making it difficult to maintain market share. Additionally, rapid technological advancements mean that smaller firms may struggle to allocate sufficient R&D budgets, limiting their ability to innovate and compete effectively.
Trends in the China Vehicle Control Components Market
The trends below show where the China Vehicle Control Components Market is heading.
- Shift towards Electric Vehicles in Guangdong: Guangdong province is experiencing a notable shift towards electric vehicles, with 30% of national vehicle production occurring there. This trend is bolstered by the government's 'Electric Vehicle Promotion Plan', which aims to increase electric vehicle sales to 20% by 2025.
- Transition to Advanced Driver-Assistance Systems: The automotive industry is increasingly embracing advanced driver-assistance systems, improving vehicle safety and control. The installed base of electric vehicles reached 10 million units by 2023, driving demand for sophisticated control components.
- Emergence of Smart Vehicle Technologies: The 'Smart Vehicle Innovation and Development Strategy' launched in 2023 is promoting the development of smart vehicle technologies. This initiative aims to improve vehicle safety and user experience, driving demand for innovative control components.
- Focus on Compliance with Safety Standards: Since the update of the 'National Standard for Vehicle Control Systems' in 2021, manufacturers are prioritising compliance with safety regulations. This shift is crucial for ensuring the safety and reliability of vehicle control components.
Investment Opportunities in the China Vehicle Control Components Market
Some of the investment opportunities in the China Vehicle Control Components Market are mentioned below.
- Investment in Electric Vehicle Infrastructure: Shenzhen is emerging as a hub for automotive electronics, presenting significant investment opportunities in electric vehicle infrastructure. The government aims to increase electric vehicle sales to 20% of total sales by 2025, creating demand for control components.
- Supply of Advanced Control Components: There is a growing gap in the market for advanced control components, driven by the rise of electric vehicles. Automotive OEMs are seeking innovative solutions to improve vehicle performance and safety.
- Development of Smart Vehicle Technologies: The push for smart vehicle technologies creates opportunities for component suppliers. The 'Smart Vehicle Innovation and Development Strategy' launched in 2023 supports innovation in this area, encouraging investment.
- Expansion of R&D Facilities: The automotive sector's focus on R&D presents opportunities for investment in new facilities. The Beijing Automotive Industry Group's heavy R&D investment highlights the potential for growth in vehicle control technologies.
Government Initiatives in the China Vehicle Control Components Market
The 'Smart Vehicle Innovation and Development Strategy' launched by the Ministry of Industry and Information Technology in 2023 aims to promote advanced automotive technologies. This initiative encourages manufacturers to adopt innovative vehicle control components and improve safety standards. The strategy also supports funding for research and development in smart vehicle technologies, enhancing the overall automotive environment in China. Additionally, the 'Automotive Industry Development Plan (2021-2025)' focuses on sustainability and innovation in vehicle manufacturing, further driving demand for advanced components.
The Ministry of Industry and Information Technology oversees the implementation of the 'Electric Vehicle Promotion Plan', which provides subsidies for the development of electric vehicle control technologies. This scheme encourages automotive OEMs to invest in innovative components and technologies, ensuring compliance with safety standards. The National Development and Reform Commission also supports local component manufacturers through funding initiatives, helping to strengthen the supply chain and improve production capabilities.
Future Insight of the China Vehicle Control Components Market
Several forward-looking factors should support the China Vehicle Control Components Market over the coming years. The government's 'Smart Vehicle Innovation and Development Strategy' will drive advancements in automotive technology, enhancing safety and efficiency. By 2025, the aim to achieve a 20% share of electric vehicle sales will create substantial demand for advanced control components. Increased funding from the National Development and Reform Commission will support smart vehicle technology initiatives, while the robust automotive workforce will strengthen innovation capabilities.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Pedal Assemblies Dominated, Levers & Actuators Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, in 2025, Pedal Assemblies led the component type split with a 46% share. Pedal assemblies hold the largest market share because they are vital for vehicle operation and ensuring driver control. With the automotive sector in Guangdong province accounting for 30% of national vehicle production, the reliance on these components is evident. Levers & Actuators are projected to grow fastest, at a CAGR of 6.3% during 2026–2032. Levers and actuators are experiencing rapid growth due to their critical function in mechanical operations within vehicles. The push towards advanced driver-assistance systems, particularly with the installed base of electric vehicles reaching 10 million units by 2023, is driving this demand. This trend indicates that suppliers must prioritise the development of levers and actuators to seize emerging opportunities in the market.
By Control Function – Driver Input Dominated, Mechanic-to-Electronic Expected to Grow Fastest
Driver Input took a 35% share of control function in 2025, more than any other category. Driver input systems lead the market as they are fundamental for vehicle operation and user interaction. The installed base of electric vehicles in China reached 10 million units by 2023, highlighting the critical need for these systems. Mechanic-to-Electronic is set to record the highest CAGR in this split, 6.8% over 2026–2032. Mechanic-to-electronic systems are experiencing swift growth as they facilitate the transition to electronic systems in vehicles. This trend is propelled by government initiatives promoting smart vehicle technologies, ensuring their increasing relevance. Buyers should prioritise investments in mechanic-to-electronic systems to stay aligned with industry advancements.
By Integration Area – Footwell Area Dominated, Transmission Interface Expected to Grow Fastest
With a 41% revenue share in 2025, Footwell Area was the largest integration area category. The footwell area holds the largest market share as it is integral to the driver's control environment. Concentrated vehicle production in Guangdong province ensures a steady demand for components in this critical area. The quickest growth will come from Transmission Interface, forecast to expand at a CAGR of 6.7% between 2026 and 2032. The transmission interface is seeing rapid growth due to its necessity for efficient vehicle gear shifting. As the automotive industry progresses, the demand for advanced transmission components is expected to surge. Suppliers should innovate in transmission interface components to meet the rising demand from manufacturers.
By End User – Automotive OEMs Dominated, Sports & Utility Vehicles Expected to Grow Fastest
Automotive OEMs held a 40% share of the China Vehicle Control Components Market by end user in 2025. Automotive OEMs command the largest share as they are the primary users of vehicle control components. The employment of over 5 million people in the automotive industry highlights the scale of production and the reliance on OEMs for component sourcing. Over 2026–2032, Sports & Utility Vehicles are expected to post the fastest growth, at a CAGR of 6.6%. Sports and utility vehicles are seeing the fastest growth as they represent a specific application of components in performance vehicles. The increasing popularity of these vehicle types is driving demand for tailored control components. Manufacturers should target the sports and utility vehicle segment to maximise their market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Control Components Market Outlook
- Market Size of China Vehicle Control Components Market, 2025
- Forecast of China Vehicle Control Components Market, 2032
- Historical Data and Forecast of China Vehicle Control Components Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Control Components Market Trend Evolution
- China Vehicle Control Components Market Drivers and Challenges
- China Vehicle Control Components Price Trends
- China Vehicle Control Components Porter's Five Forces
- China Vehicle Control Components Industry Life Cycle
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Pedal Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Rotary Knobs & Switches for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Levers & Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Joysticks & Shifters for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Control Function for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Driver Input for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Dashboard Interface for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Mechanic-to-Electronic for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Directional Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Integration Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Footwell Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Instrument Panel for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Steering/Doors for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Transmission Interface for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Interior Designers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Component Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Components Market Revenues & Volume By Sports & Utility Vehicles for the Period 2022 - 2032F
- China Vehicle Control Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Control Function
- Market Opportunity Assessment By Integration Area
- Market Opportunity Assessment By End User
- China Vehicle Control Components Top Companies Market Share
- China Vehicle Control Components Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Control Components Company Profiles
- China Vehicle Control Components Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Component Type
- Pedal Assemblies
- Rotary Knobs & Switches
- Levers & Actuators
- Joysticks & Shifters
By Control Function
- Driver Input
- Dashboard Interface
- Mechanic-to-Electronic
- Directional Control
By Integration Area
- Footwell Area
- Instrument Panel
- Steering/Doors
- Transmission Interface
By End User
- Automotive OEMs
- Interior Designers
- Component Suppliers
- Sports & Utility Vehicles































