China Vehicle Control Software Market Size & Growth Rate
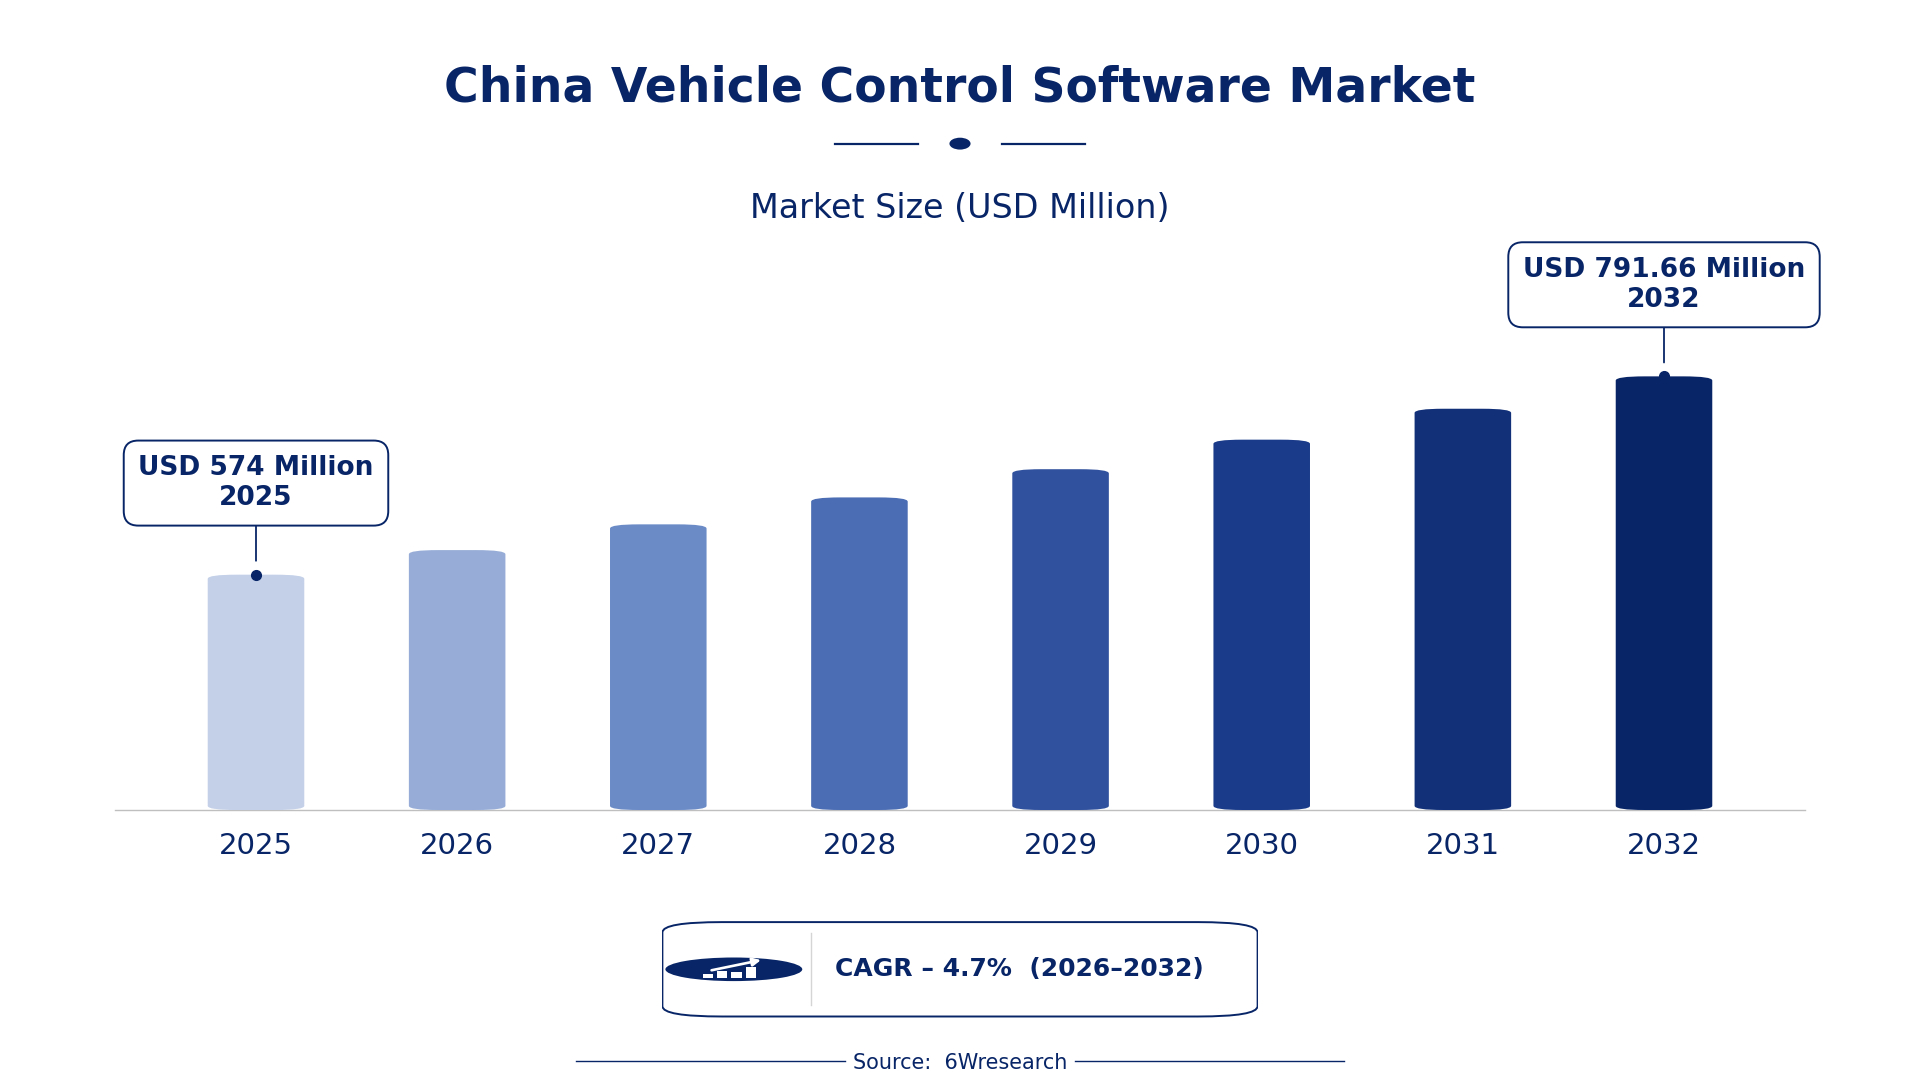
According to 6Wresearch internal database and industry insights, the China Vehicle Control Software Market was valued at USD 574.0 million in 2025 and is projected to reach USD 791.66 million by 2032, growing at a CAGR of approximately 4.7% during 2026–2032.
China Vehicle Control Software Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Control Software Market |
| Market Size 2025 | USD 574.0 million |
| Market Size 2032 | USD 791.66 million |
| Absolute Growth 2025–2032 | USD 217.66 million |
| CAGR 2026–2032 | 4.7% |
| Peak Annual Growth | 7.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | Engine Management Software (39% share) |
| Leading Control Function, 2025 | Fuel & Air Control (46% share) |
| Leading Deployment Platform, 2025 | Embedded ECU (45% share) |
| Leading End User, 2025 | ICE Car OEMs (56% share) |
| Fastest-Growing Software Type | Transmission Control Code (6.8% CAGR) |
| Fastest-Growing Control Function | Safety & Stability (6.0% CAGR) |
| Fastest-Growing Deployment Platform | TCU/ECU (6.6% CAGR) |
| Fastest-Growing End User | ADAS Companies (6.3% CAGR) |
| Growing Sector | automotive |
| Key End Users | ICE Car OEMs, ADAS Companies, Transmission System Developers, Luxury Car OEMs |
China Vehicle Control Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
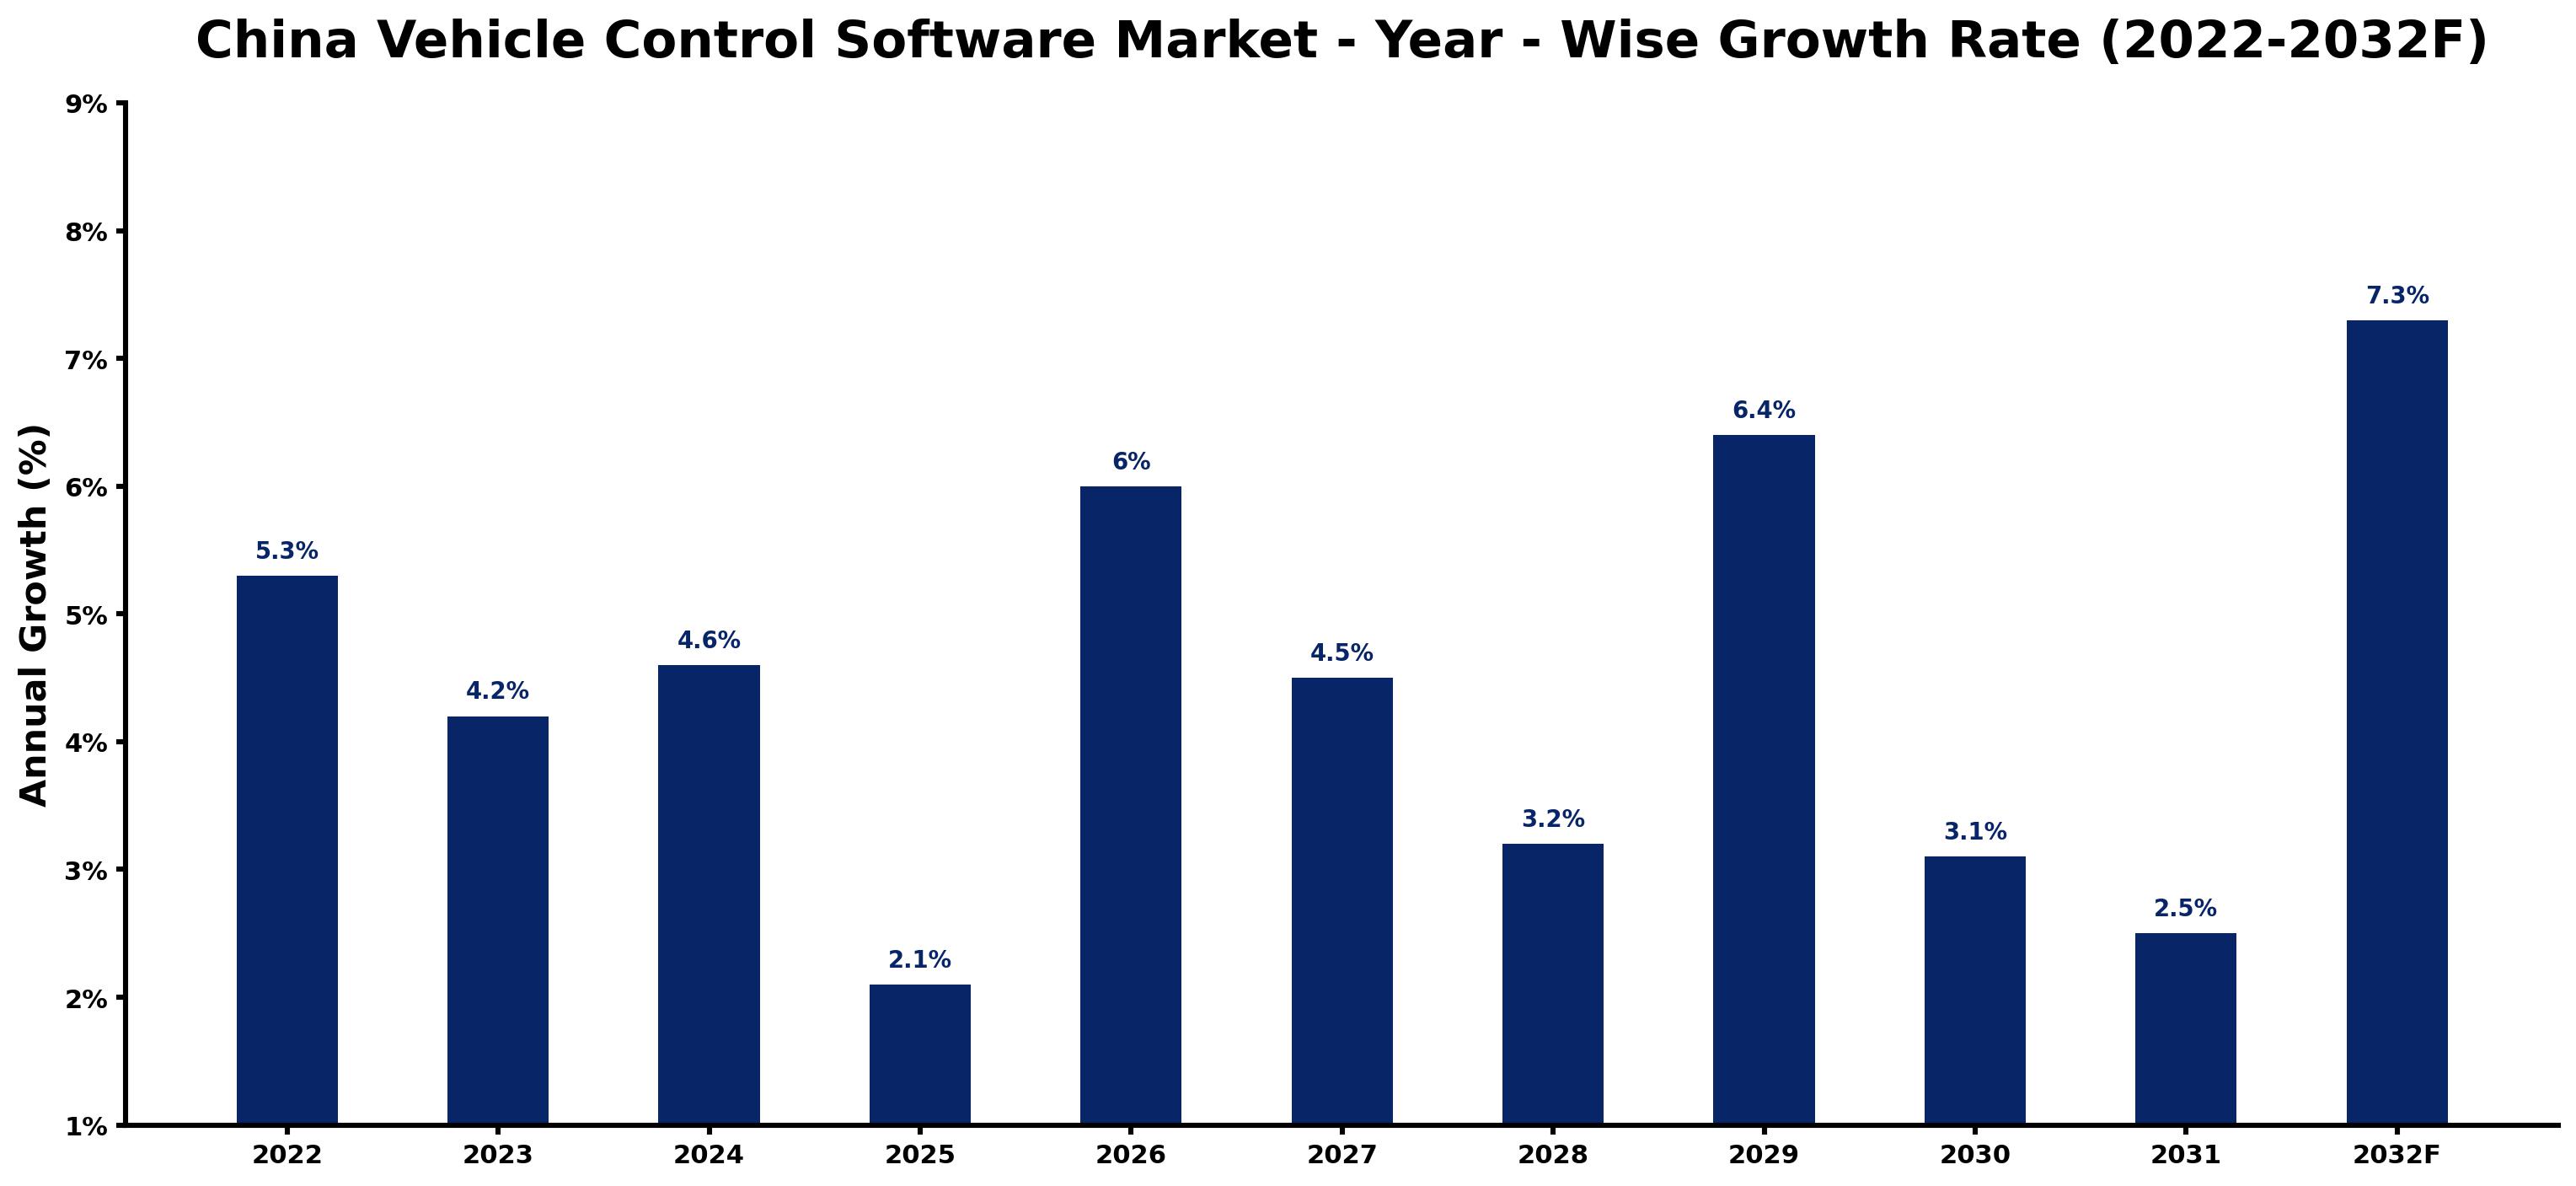
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.3 | The market experienced strong demand due to high vehicle production levels, supported by the automotive industry's expansion. |
| 2023 | 4.2 | Growth slowed as manufacturers adjusted to evolving software requirements outlined in the Smart Vehicle Innovation and Development Strategy. |
| 2024 | 4.6 | Increased investments in electric vehicles spurred higher software demand, driven by the New Energy Vehicle Industry Development Plan. |
| 2025 | 2.1 | Market growth decelerated as manufacturers focused on existing software integration and compliance with national standards. |
| 2026 | 6.0 | Rising demand for advanced driver-assistance systems boosted software adoption, aligning with industry safety regulations. |
| 2027 | 4.5 | Growth slowed as the market adjusted to new regulatory standards set by GB/T 34590.1-2017. |
| 2028 | 3.2 | Demand for safety features continued to drive software integration, albeit at a slower pace due to market adjustments. |
| 2029 | 6.4 | The market rebounded with renewed interest in electric vehicle software capabilities, supported by government initiatives. |
| 2030 | 3.1 | Growth slowed as manufacturers faced challenges in meeting evolving safety standards and technological demands. |
| 2031 | 2.5 | Demand remained steady as manufacturers focused on software updates and integration, driven by competitive pressures. |
| 2032 | 7.3 | The market is set to peak as investments in smart vehicle technologies surge, driven by the Smart Vehicle Innovation and Development Strategy. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Control Software Market Synopsis
Vehicle Control Software in China includes technologies that manage engine performance, transmission, and safety systems. This software is developed through coding and integration with hardware components, improving vehicle performance and safety. The China Vehicle Control Software Market is growing due to strong demand from domestic manufacturers and investments in electric and autonomous vehicles. In 2022, over 26 million vehicles were produced, further increasing the need for advanced software solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing vehicle production drives demand for control software integration. | Driver | High | Engine Management Software |
| Growing investments in electric vehicles create a need for advanced software solutions. | Driver | High | Transmission Control Code |
| The automotive software market is projected to reach 60 billion CNY by 2025. | Opportunity | High | Brake/Steering Software |
| The rise of smart vehicles presents opportunities for innovative software applications. | Opportunity | Medium | ADAS Companies |
| Regulatory compliance requirements can slow software development processes. | Restraint | High | Safety & Stability |
| Limited integration capabilities of existing systems may hinder market growth. | Restraint | Medium | Fuel & Air Control |
| The Vehicle Control Software market in China faces challenges due to complex regulations. | Challenge | High | Embedded ECU |
| Competition among software developers can lead to pricing pressures. | Challenge | Medium | TCU/ECU |
Evaluation of Drivers in China Vehicle Control Software Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle production levels increase the need for control software. | Engine Management Software | In 2022, China produced over 26 million vehicles, driving software demand. |
| Investments in electric vehicles necessitate advanced software solutions. | Transmission Control Code | The New Energy Vehicle Industry Development Plan aims to improve software capabilities for EVs. |
| Growing demand for safety features boosts software integration in vehicles. | Safety & Stability | The national standard GB/T 34590.1-2017 imposes strict safety requirements, ensuring compliance. |
| Increased focus on advanced driver-assistance systems drives software development. | ADAS Companies | The automotive electronics market is projected to grow, prioritising safety and efficiency. |
| The installed base of ECUs is expected to exceed 1 billion units by 2025. | Embedded ECU | This growth creates a substantial market for vehicle control software integration. |
The Vehicle Control Software market in China is expanding as rising vehicle production levels, investments in electric vehicles, and increasing demand for safety features drive software integration. In 2022, over 26 million vehicles were produced, which greatly heightened the need for advanced control software. The New Energy Vehicle Industry Development Plan aims to improve software capabilities, further supporting market growth. The installed base of ECUs is expected to exceed 1 billion units by 2025, generating substantial demand for software solutions. As manufacturers prioritise advanced driver-assistance systems, the market will continue to see increased investment and innovation in software development.
Evaluation of Restraints in China Vehicle Control Software Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Complex regulatory compliance can delay software development timelines. | Safety & Stability | The updated national standard GB/T 34590.1-2017 imposes strict safety requirements, causing delays. |
| Limited integration capabilities of existing systems may hinder software adoption. | Fuel & Air Control | Many vehicles still rely on outdated systems that are not compatible with new software solutions. |
| High development costs associated with advanced software can deter smaller firms. | Transmission Control Code | The need for skilled personnel and technology investments raises entry barriers for new entrants. |
| Market competition can lead to price wars, affecting profitability. | Embedded ECU | Numerous players are vying for market share, driving prices down and impacting margins. |
| Slow adoption of new technologies among traditional manufacturers can limit growth. | ADAS Companies | Some manufacturers are hesitant to transition to advanced software solutions, impacting overall market progress. |
China Vehicle Control Software Market Challenges
The China Vehicle Control Software Market encounters several practical problems, beginning with supply chain disruptions. These disruptions arise from reliance on specific regions for essential software components, which leads to production delays for local manufacturers. A shortage of skilled engineers presents another obstacle, as the rapid pace of technological advancement exceeds the availability of qualified talent, resulting in longer development timelines for producers. Rising development costs add to the challenges, with expenses increasing by 15% annually, straining budgets for automotive producers. Compliance with standards such as GB/T 34590.1-2017 further complicates operations, forcing companies to allocate more resources to meet regulations and delaying the launch of new products.
Trends in the China Vehicle Control Software Market
Buyers and suppliers in the China Vehicle Control Software Market are adjusting to the following trends.
- Shift Towards Advanced Driver-Assistance Systems: ICE Car OEMs are increasingly focusing on advanced driver-assistance systems, with a projected growth of 6.3% in software demand. This shift highlights the need for improved safety features in vehicles.
- Transition to Smart Vehicle Technologies: The Beijing-Tianjin-Hebei region is becoming a hub for smart vehicle technologies, with significant investments driving innovation in software development. The market is set to grow as more manufacturers adopt these technologies.
- Emergence of New Energy Vehicle Software: The New Energy Vehicle Industry Development Plan is promoting the integration of advanced software in electric vehicles. By 2025, this sector is projected to require substantial software capabilities to meet safety standards.
- Growing Importance of Software Safety Standards: The updated national standard GB/T 34590.1-2017 is reshaping software development practices. Compliance with these standards is becoming essential for manufacturers to ensure safety and reliability.
Investment Opportunities in the China Vehicle Control Software Market
Several openings in the China Vehicle Control Software Market merit attention from investors.
- Investment in Advanced Driver-Assistance Systems Software: There is a growing need for software solutions focused on advanced driver-assistance systems, with substantial demand from ICE Car OEMs. Collaborating with technology firms in Guangdong province can facilitate market entry.
- Development of Electric Vehicle Software Solutions: The New Energy Vehicle Industry Development Plan highlights a gap in software capabilities for electric vehicles, with a projected increase in demand. Partnerships with automotive technology firms can enhance market presence.
- Expansion of Safety and Stability Software: With over 200 million registered vehicles, the demand for safety and stability software is significant. Manufacturers in the Beijing-Tianjin-Hebei region can benefit from investing in this area.
- Integration of Software with Embedded ECUs: The installed base of ECUs is set to exceed 1 billion units by 2025, creating opportunities for software integration. Collaborating with automotive technology firms in Shanghai can enhance market presence.
Government Initiatives in the China Vehicle Control Software Market
The "Smart Vehicle Innovation and Development Strategy" by the Ministry of Industry and Information Technology, launched in 2021, aims to improve automotive software capabilities and innovation. This strategy supports manufacturers in developing advanced software solutions for vehicles, ensuring compliance with safety standards and promoting technological advancements. The initiative encourages collaboration between industry players and research institutions to drive innovation in the sector, ultimately leading to improved vehicle performance and safety features. By 2025, the strategy targets a significant increase in software capabilities within the automotive industry.
The "New Energy Vehicle Industry Development Plan" initiated in 2023 by the State Council promotes advancements in electric vehicle software. This plan focuses on improving safety and efficiency in electric vehicles, providing funding for research and development projects. The Ministry of Industry and Information Technology oversees the implementation of this plan, ensuring that manufacturers adhere to the outlined standards. Additionally, the plan encourages partnerships between automotive firms and technology providers to accelerate software integration in new energy vehicles.
Future Insight of the China Vehicle Control Software Market
The China Vehicle Control Software Market is projected to evolve significantly by 2032, driven by key factors. The "New Energy Vehicle Industry Development Plan" will enhance software capabilities in electric vehicles, improving overall functionality. The "Smart Vehicle Innovation and Development Strategy" will promote collaboration among local developers, fostering advancements in technology. These developments will create new opportunities for suppliers and improve the quality of offerings available to buyers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Software Type – Engine Management Software Dominated, Transmission Control Code Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Engine Management Software held a 39% share of the China Vehicle Control Software Market by software type in 2025. Engine Management Software holds the largest market share because it is essential for optimising engine performance and emissions control. The substantial production of over 26 million vehicles in China in 2022 underscores its critical role for manufacturers. Transmission Control Code is projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Transmission Control Code is experiencing rapid growth as it is crucial for managing gear shifts and enhancing transmission efficiency. The projected increase in the installed base of ECUs, expected to exceed 1 billion units by 2025, will further amplify its significance. Suppliers should focus on advancing Engine Management Software to satisfy the growing demands of the automotive sector.
By Control Function – Fuel & Air Control Dominated, Safety & Stability Expected to Grow Fastest
In 2025, Fuel & Air Control led the control function split with a 46% share. Fuel & Air Control leads the market as it is vital for maintaining engine efficiency and overall performance. With over 200 million registered vehicles in China, this function is indispensable for a large portion of the automotive industry. Safety & Stability is set to record the highest CAGR in this split, 6.0% over 2026–2032. Safety & Stability is the fastest-growing segment due to its critical role in ensuring vehicle safety and stability under diverse driving conditions. The rise in investments towards safety technologies positions this area for substantial growth. Buyers should prioritise investing in Safety & Stability features to enhance vehicle safety and comply with regulatory standards.
By Deployment Platform – Embedded ECU Dominated, TCU/ECU Expected to Grow Fastest
With a 45% revenue share in 2025, Embedded ECU was the largest deployment platform category. Embedded ECU is the leading platform for implementing vehicle control software, as it serves as the primary interface for various automotive functions. The extensive use of ECUs in over 26 million vehicles produced in 2022 underscores its dominance. Over 2026–2032, TCU/ECU is expected to post the fastest growth, at a CAGR of 6.6%. TCU/ECU is growing swiftly due to its key role in managing transmission and control functions. As the automotive industry shifts towards more sophisticated transmission systems, this segment will see increased demand. Suppliers must prioritise TCU/ECU development to capture the growing market share in advanced vehicle control systems.
By End User – ICE Car OEMs Dominated, ADAS Companies Expected to Grow Fastest
The largest end user category in 2025 was ICE Car OEMs, with a 56% share of total revenue. ICE Car OEMs dominate the market as they are the primary users of vehicle control software, which is essential for the operation of traditional combustion engine vehicles. Their high production volumes significantly drive the demand for such software in China. The quickest growth will come from ADAS Companies, forecast to expand at a CAGR of 6.3% between 2026 and 2032. ADAS Companies are the fastest-growing end users, as they are key players in developing advanced features for vehicle automation. The increasing emphasis on enhanced safety and autonomous driving capabilities fuels their rapid growth. Suppliers should target ADAS Companies to align with the automotive industry's transition towards automation and advanced safety systems.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Control Software Market Outlook
- Market Size of China Vehicle Control Software Market, 2025
- Forecast of China Vehicle Control Software Market, 2032
- Historical Data and Forecast of China Vehicle Control Software Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Control Software Market Trend Evolution
- China Vehicle Control Software Market Drivers and Challenges
- China Vehicle Control Software Price Trends
- China Vehicle Control Software Porter's Five Forces
- China Vehicle Control Software Industry Life Cycle
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Engine Management Software for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Transmission Control Code for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Brake/Steering Software for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Climate Control Algorithms for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Control Function for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Fuel & Air Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Shift Optimization for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Safety & Stability for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Thermal Regulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Deployment Platform for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Embedded ECU for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By TCU/ECU for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Integrated Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By HVAC Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By ICE Car OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Transmission System Developers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By ADAS Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Software Market Revenues & Volume By Luxury Car OEMs for the Period 2022 - 2032F
- China Vehicle Control Software Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Control Function
- Market Opportunity Assessment By Deployment Platform
- Market Opportunity Assessment By End User
- China Vehicle Control Software Top Companies Market Share
- China Vehicle Control Software Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Control Software Company Profiles
- China Vehicle Control Software Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Software Type
- Engine Management Software
- Transmission Control Code
- Brake/Steering Software
- Climate Control Algorithms
By Control Function
- Fuel & Air Control
- Shift Optimization
- Safety & Stability
- Thermal Regulation
By Deployment Platform
- Embedded ECU
- TCU/ECU
- Integrated Sensors
- HVAC Systems
By End User
- ICE Car OEMs
- Transmission System Developers
- ADAS Companies
- Luxury Car OEMs































