China Vehicle Control Systems Market Size & Growth Rate
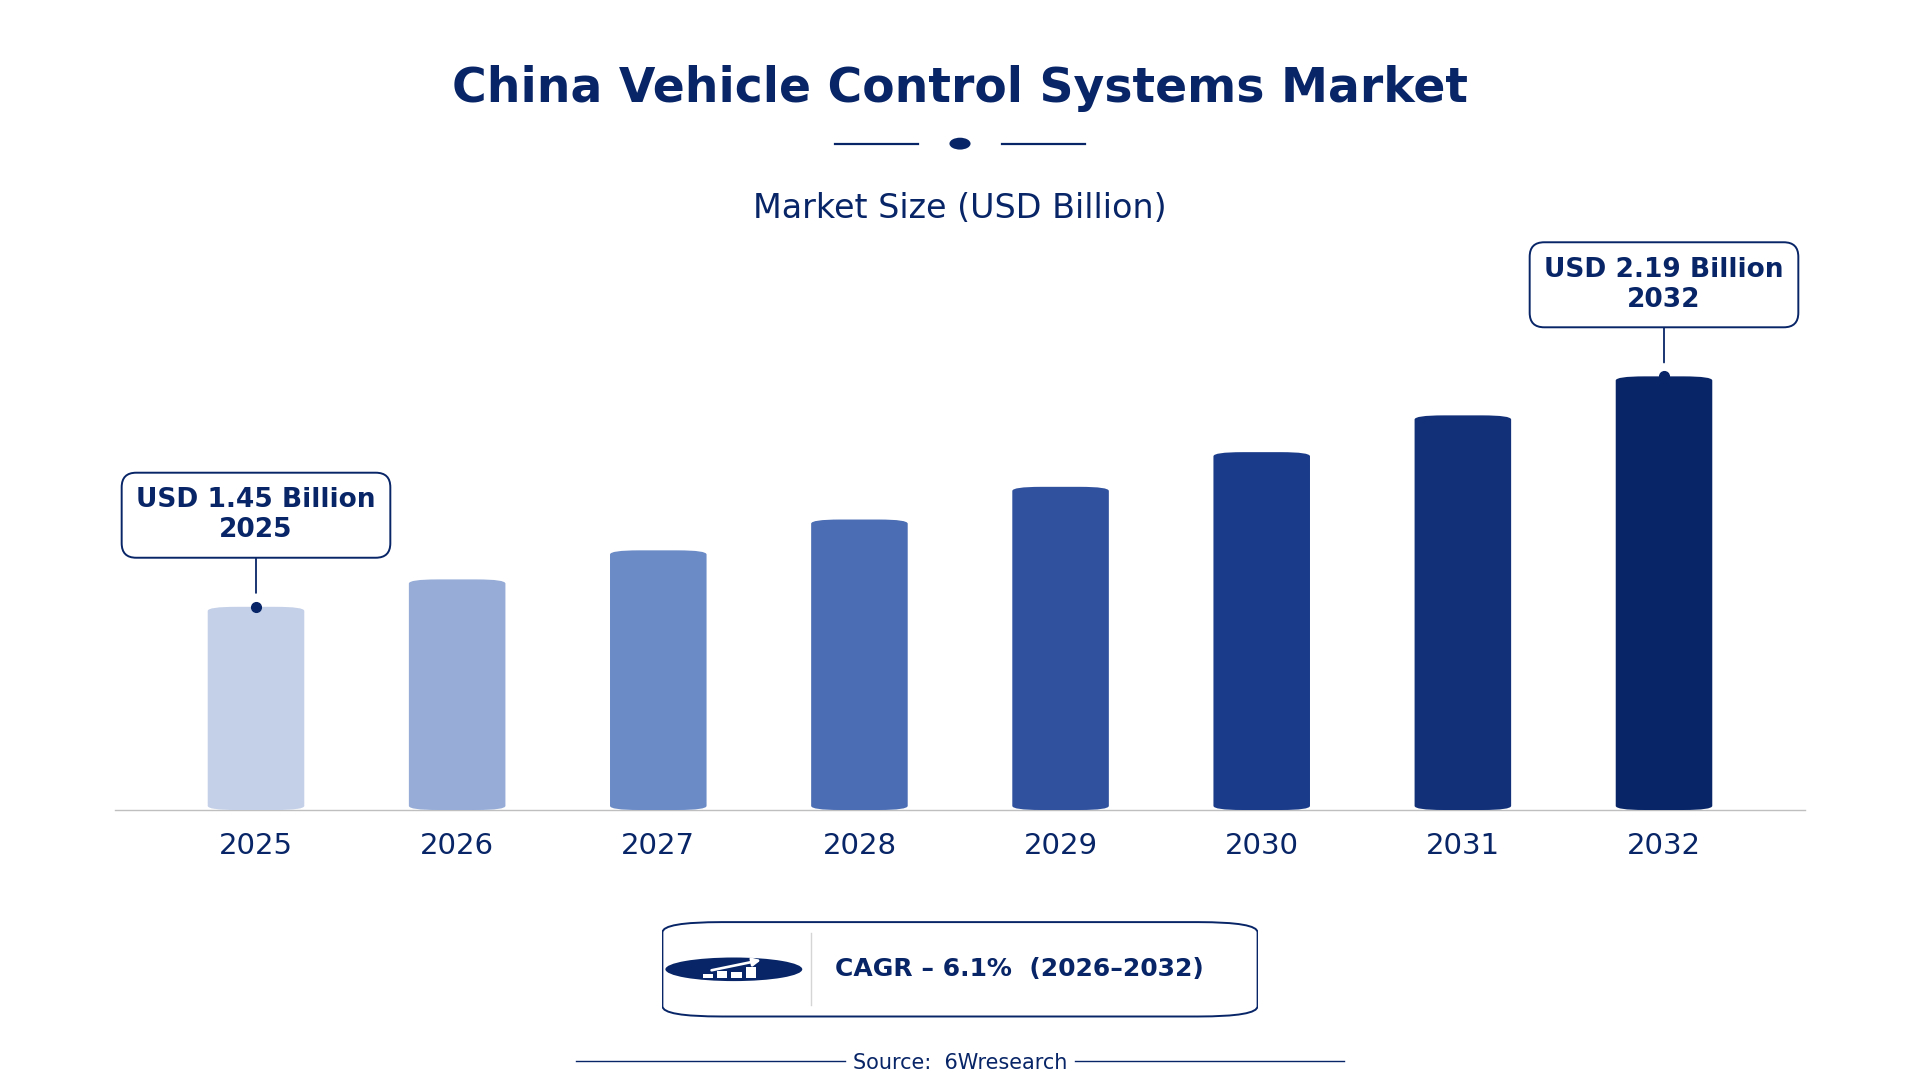
According to 6Wresearch internal database and industry insights, the China Vehicle Control Systems Market was valued at USD 1.45 billion in 2025 and is projected to reach USD 2.19 billion by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Vehicle Control Systems Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Control Systems Market |
| Market Size 2025 | USD 1.45 billion |
| Market Size 2032 | USD 2.19 billion |
| Absolute Growth 2025–2032 | USD 0.74 billion |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 7.8% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading System Type, 2025 | Powertrain Control Systems (44% share) |
| Leading Control Domain, 2025 | Engine & Transmission (37% share) |
| Leading Automation Level, 2025 | Fully Automatic (49% share) |
| Leading End User, 2025 | EV and SUV OEMs (34% share) |
| Fastest-Growing System Type | Chassis Control Systems (7.6% CAGR) |
| Fastest-Growing Control Domain | Interior Electronics (8.3% CAGR) |
| Fastest-Growing Automation Level | Level 2–3 (8.7% CAGR) |
| Fastest-Growing End User | Smart Vehicle Integrators (7.4% CAGR) |
| Growing Sector | Electric and Hybrid Vehicle Manufacturing |
| Key End Users | OEMs, automotive manufacturers, technology integrators |
China Vehicle Control Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
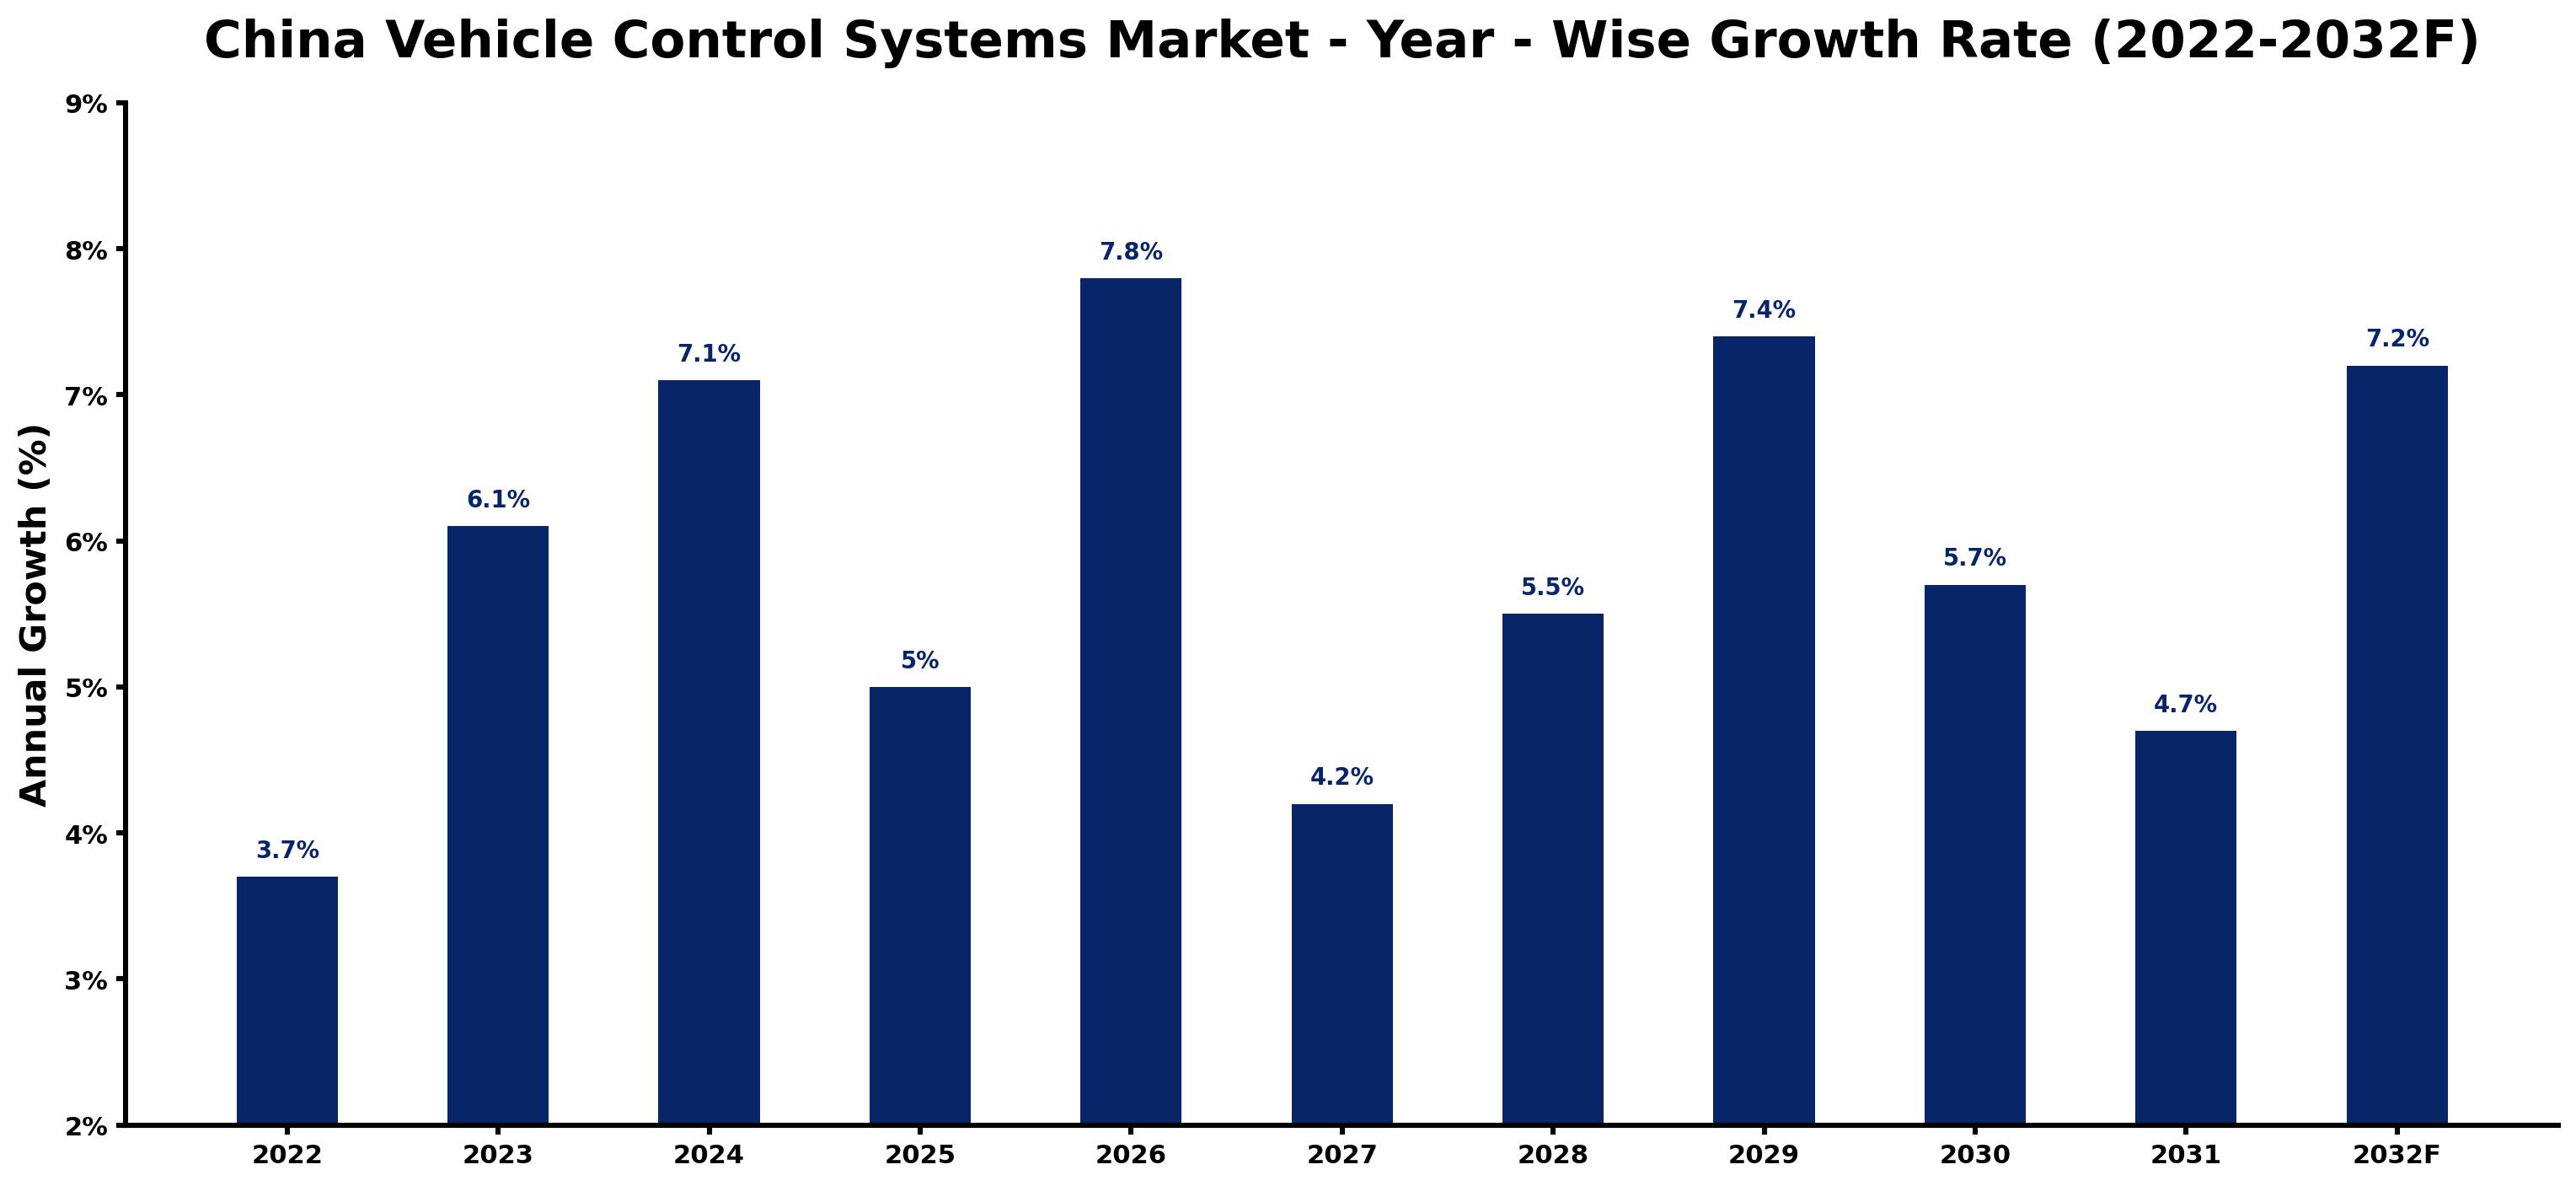
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.7 | The market experienced steady growth, driven by the ongoing demand for vehicle control systems from domestic manufacturers. |
| 2023 | 6.1 | Increased production of electric vehicles contributed to faster growth compared to the previous year, particularly among EV and SUV OEMs. |
| 2024 | 7.1 | Growth continued as manufacturers adopted advanced technologies in vehicle control systems, influenced by the updated National Standard for Vehicle Control Systems. |
| 2025 | 5.0 | The growth rate slowed as manufacturers adjusted to rapid advancements and compliance with new safety standards. |
| 2026 | 7.8 | Investment in research and development surged, resulting in a peak growth rate for the year, supported by the 'New Energy Vehicle Industry Development Plan'. |
| 2027 | 4.2 | The market is expected to see a slowdown as manufacturers face challenges in meeting the updated guidelines for intelligent and connected vehicle development. |
| 2028 | 5.5 | Demand for smart vehicle technologies is projected to increase, driving growth faster than the previous year, particularly among Smart Vehicle Integrators. |
| 2029 | 7.4 | The introduction of new regulations is expected to boost growth as manufacturers upgrade their systems to comply with safety standards. |
| 2030 | 5.7 | Growth is projected to slow again as the market adjusts to the new regulatory environment and increased competition. |
| 2031 | 4.7 | The market will continue to grow but at a slower pace due to heightened competition and evolving consumer preferences. |
| 2032 | 7.2 | A resurgence in demand for electric vehicles is expected to drive growth faster than the previous year, aligning with government targets. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Control Systems Market Synopsis
The China Vehicle Control Systems Market includes sophisticated electronic systems that oversee various vehicle functions, such as powertrain, chassis, and body operations. These systems enhance performance, safety, and comfort through intricate software and hardware. The market is expanding due to growing demand from local manufacturers and an increase in imports, especially in electric and hybrid vehicles. In 2023, the government initiated the 'New Energy Vehicle Industry Development Plan', targeting 20% of all vehicles to be NEVs by 2025. This initiative is driving new demand within the market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investment in R&D for vehicle automation technologies | Driver | High | Powertrain Control Systems |
| Increasing demand for electric vehicles and hybrids | Driver | High | EV and SUV OEMs |
| Investment opportunities in smart vehicle technologies | Opportunity | High | Smart Vehicle Integrators |
| Expansion of manufacturing facilities in key regions | Opportunity | High | Powertrain Control Systems |
| Stricter emissions standards impacting design requirements | Restraint | High | Chassis Control Systems |
| Compliance costs associated with new safety standards | Restraint | Medium | Brake Control Systems |
| Supply chain disruptions affecting component availability | Challenge | High | Body Control Systems |
| Competition from international manufacturers in the market | Challenge | Medium | Engine & Transmission |
Evaluation of Drivers in China Vehicle Control Systems Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in R&D for vehicle control systems | Powertrain Control Systems | Over 100 billion yuan allocated for R&D by 2025 is driving innovation and demand for advanced technologies. |
| Rising production of electric vehicles in China | EV and SUV OEMs | The installed base of electric vehicles reached 10 million units in 2022, boosting demand from manufacturers and suppliers. |
| Growing adoption of advanced driver assistance systems | Chassis Control Systems | 30% of new vehicles are equipped with these systems, increasing demand for control technologies among manufacturers. |
| Expansion of smart vehicle technologies | Smart Vehicle Integrators | The National Development and Reform Commission's strategy promotes advanced vehicle technologies, driving demand for innovative solutions. |
| Increased consumer demand for safety features in vehicles | Brake Control Systems | New safety regulations are pushing manufacturers to improve braking technologies, responding to consumer preferences. |
Growth in the Vehicle Control Systems market in China is rooted in heightened investment in R&D, increased production of electric vehicles, and a rise in the adoption of advanced driver assistance systems. Substantial funding for R&D is spurring advancements in vehicle control technologies. The installed base of electric vehicles reached 10 million units in 2022, which has boosted demand from manufacturers. In addition, 30% of new vehicles are now equipped with advanced driver assistance systems, creating a greater need for control technologies. The National Development and Reform Commission's strategy encourages the development of advanced vehicle technologies, further propelling market growth.
Evaluation of Restraints in China Vehicle Control Systems Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter emissions standards affecting design and compliance | Chassis Control Systems | The Ministry of Ecology and Environment's regulations are increasing design complexity and costs for manufacturers, impacting their profitability. |
| Compliance costs associated with new safety standards | Brake Control Systems | The implementation of new safety regulations is raising production costs for manufacturers, affecting pricing strategies and market competitiveness. |
| Supply chain disruptions impacting component availability | Body Control Systems | Global supply chain issues are delaying production timelines and increasing costs for manufacturers, affecting delivery schedules and customer satisfaction. |
| Competition from international manufacturers | Engine & Transmission | Local manufacturers face challenges in competing with established global brands, impacting market share and pricing strategies. |
| Rapid technological advancements leading to obsolescence | Powertrain Control Systems | The fast pace of innovation is making existing technologies outdated quickly, necessitating continuous investment in R&D to remain competitive. |
China Vehicle Control Systems Market Challenges
Buyers in the China Vehicle Control Systems market encounter intense competition as domestic and international producers vie for market share, which drives prices down and reduces profit margins. High research and development expenses, with over 100 billion yuan allocated for R&D by 2025, burden manufacturers and limit their ability to invest in new technologies. A shortage of skilled engineers familiar with ISO 26262 standards creates recruitment challenges, causing project delays and escalating hiring costs for producers. Supply chain disruptions, especially in Shandong province, lead to production holdups, inflating costs for manufacturers and delaying product availability for buyers.
Trends in the China Vehicle Control Systems Market
Four trends stand out in the China Vehicle Control Systems Market.
- Shift towards Smart Vehicle Technologies: China is increasingly adopting smart vehicle technologies, driven by consumer demand for connectivity and automation. In 2022, the installed base of electric vehicles reached 10 million units, indicating a shift towards more advanced vehicle systems.
- Transition from Conventional to Electric Vehicles: The shift began in 2023 with the launch of the 'New Energy Vehicle Industry Development Plan'. By 2025, it aims for 20% of all vehicles to be NEVs, reflecting changing consumer preferences and regulatory support.
- Emergence of Advanced Driver Assistance Systems: The adoption of advanced driver assistance systems has surged, with 30% of new vehicles equipped with these features in 2023. This trend is reshaping the vehicle control systems market in response to safety demands.
- Prioritisation of Safety Features in Vehicle Design: In 2021, updated safety regulations prompted manufacturers to improve safety features. Compliance with these regulations is driving demand for advanced braking and control systems, ensuring vehicles meet new standards.
Investment Opportunities in the China Vehicle Control Systems Market
Below are the investment opportunities with the strongest case in the China Vehicle Control Systems Market.
- Entry through Joint Ventures in Key Regions: Investing in joint ventures in Shandong province, a manufacturing hub for vehicle control systems, is timely as the market is projected to grow with substantial funding for R&D by 2025.
- Focus on Smart Vehicle Integrators: Smart Vehicle Integrators are increasingly seeking advanced vehicle control systems. With the market expanding, suppliers can enter through partnerships and collaborations with local manufacturers to meet this demand.
- Investment in Electric Vehicle Production Facilities: With the installed base of electric vehicles reaching 10 million units, there is a pressing need for production facilities. Investing in these facilities will address the rising demand from EV manufacturers.
- Approval for Advanced Driver Assistance Systems: Manufacturers should focus on obtaining certifications for advanced driver assistance systems, as 30% of new vehicles are now equipped with these technologies, creating a substantial market opportunity.
Government Initiatives in the China Vehicle Control Systems Market
In 2023, the Ministry of Industry and Information Technology launched the 'New Energy Vehicle Industry Development Plan', aiming for 20% of all vehicles to be NEVs by 2025. This plan builds on the '14th Five-Year Plan for the Automotive Industry' and emphasises innovation and sustainability in vehicle control systems. The updated guidelines are expected to drive compliance and advancements in the industry, ensuring manufacturers focus on developing advanced technologies while adhering to environmental standards.
The Ministry of Transport oversees the implementation of updated guidelines for intelligent and connected vehicle development. This agency funds initiatives aimed at improving vehicle control systems and ensuring compliance with safety standards. In 2023, the ministry reported that 30% of new vehicles are equipped with advanced driver assistance systems, highlighting the importance of these regulations in shaping the market and encouraging manufacturers to innovate.
Future Insight of the China Vehicle Control Systems Market
The China Vehicle Control Systems market will undergo substantial changes by 2032, driven by the New Energy Vehicle Industry Development Plan, which aims for 20% of all vehicles to be NEVs by 2025. Increased investment in smart vehicle technologies will improve safety and performance features, offering clear benefits for both buyers and suppliers. By 2025, 30% of new vehicles are expected to include advanced driver assistance systems, setting new industry standards. Stricter emissions regulations will compel manufacturers to innovate, aligning product offerings with evolving consumer demands.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By System Type – Powertrain Control Systems Dominated, Chassis Control Systems Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, in 2025, Powertrain Control Systems led the system type split with a 44% share. Powertrain Control Systems dominate the market share as they are essential for optimising engine performance and efficiency. Their critical role is highlighted by the production of over 25 million vehicles in China in 2022, making them indispensable for both electric and conventional vehicles. Chassis Control Systems are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Chassis Control Systems are experiencing rapid growth due to their crucial role in vehicle stability and handling, especially with advanced driver assistance systems now found in 30% of new vehicles. This trend indicates a rising consumer demand for improved safety and performance features in vehicles, which will further solidify the lead of powertrain systems. Suppliers should prioritise advancements in chassis technologies to align with the increasing safety and performance expectations of manufacturers.
By Control Domain – Engine & Transmission Dominated, Interior Electronics Expected to Grow Fastest
With a 37% revenue share in 2025, Engine & Transmission was the largest control domain category. Engine & Transmission systems capture the largest market share as they are vital for effective power management in vehicles, ensuring optimal performance. The production of over 25 million vehicles in 2022 underscores the essential nature of these systems in the automotive sector. The quickest growth will come from Interior Electronics, forecast to expand at a CAGR of 8.3% between 2026 and 2032. Interior Electronics are projected for the fastest growth, driven by the rising demand for user interface and connectivity features in vehicles. This shift towards smart vehicles is prompting manufacturers to enhance technological integration, which will likely widen the gap with engine and transmission systems. Manufacturers must invest in innovative interior electronics to meet the evolving preferences of tech-savvy consumers.
By Automation Level – Fully Automatic Dominated, Level 2–3 Expected to Grow Fastest
Fully Automatic accounted for a 49% market share by automation level in 2025. Fully Automatic systems currently dominate the market share, although their applications are limited, representing emerging technologies in vehicle automation. Their potential for future development is considerable, particularly as the automotive industry moves towards more advanced automation solutions. Over 2026–2032, Level 2–3 is expected to post the fastest growth, at a CAGR of 8.7%. Level 2–3 automation is the fastest-growing segment, widely adopted in modern vehicles for semi-autonomous features. This growth is fuelled by consumer interest in advanced driving assistance technologies, which are becoming standard in new vehicle models. Suppliers should prioritise the development of Level 2–3 automation technologies to align with market trends and consumer expectations.
By End User – EV and SUV OEMs Dominated, Smart Vehicle Integrators Expected to Grow Fastest
EV and SUV OEMs held a 34% share of the China Vehicle Control Systems Market by end user in 2025. EV and SUV OEMs hold the largest market share, reflecting a significant consumer shift towards electric and sport utility vehicles. This trend is reinforced by government initiatives aiming for 20% of all vehicles to be new energy vehicles by 2025, driving demand in this segment. Smart Vehicle Integrators are set to record the highest CAGR in this split, 7.4% over 2026–2032. Smart Vehicle Integrators are witnessing the fastest growth due to the increasing interest in smart vehicle technologies that enhance connectivity and user experience. This segment's expansion aligns with the broader transition within the automotive industry towards integrating advanced technologies into vehicles, further benefiting EV and SUV OEMs. Suppliers should collaborate with smart vehicle integrators to develop cutting-edge solutions that cater to modern consumer demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Control Systems Market Outlook
- Market Size of China Vehicle Control Systems Market, 2025
- Forecast of China Vehicle Control Systems Market, 2032
- Historical Data and Forecast of China Vehicle Control Systems Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Control Systems Market Trend Evolution
- China Vehicle Control Systems Market Drivers and Challenges
- China Vehicle Control Systems Price Trends
- China Vehicle Control Systems Porter's Five Forces
- China Vehicle Control Systems Industry Life Cycle
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By System Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Powertrain Control Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Chassis Control Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Brake Control Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Body Control Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Control Domain for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Engine & Transmission for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Suspension/Steering for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Regenerative/Conventional for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Interior Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Automation Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Partial Automation for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Level 2 3 for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Level 1 2 for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Fully Automatic for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Hybrid Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By EV and SUV OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Passenger Car OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Control Systems Market Revenues & Volume By Smart Vehicle Integrators for the Period 2022 - 2032F
- China Vehicle Control Systems Import Export Trade Statistics
- Market Opportunity Assessment By System Type
- Market Opportunity Assessment By Control Domain
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By End User
- China Vehicle Control Systems Top Companies Market Share
- China Vehicle Control Systems Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Control Systems Company Profiles
- China Vehicle Control Systems Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By System Type
- Powertrain Control Systems
- Chassis Control Systems
- Brake Control Systems
- Body Control Systems
By Control Domain
- Engine & Transmission
- Suspension/Steering
- Regenerative/Conventional
- Interior Electronics
By Automation Level
- Partial Automation
- Level 2–3
- Level 1–2
- Fully Automatic
By End User
- Hybrid Vehicle OEMs
- EV and SUV OEMs
- Passenger Car OEMs
- Smart Vehicle Integrators































