India Hydroforming Technology Market Size & Growth Rate
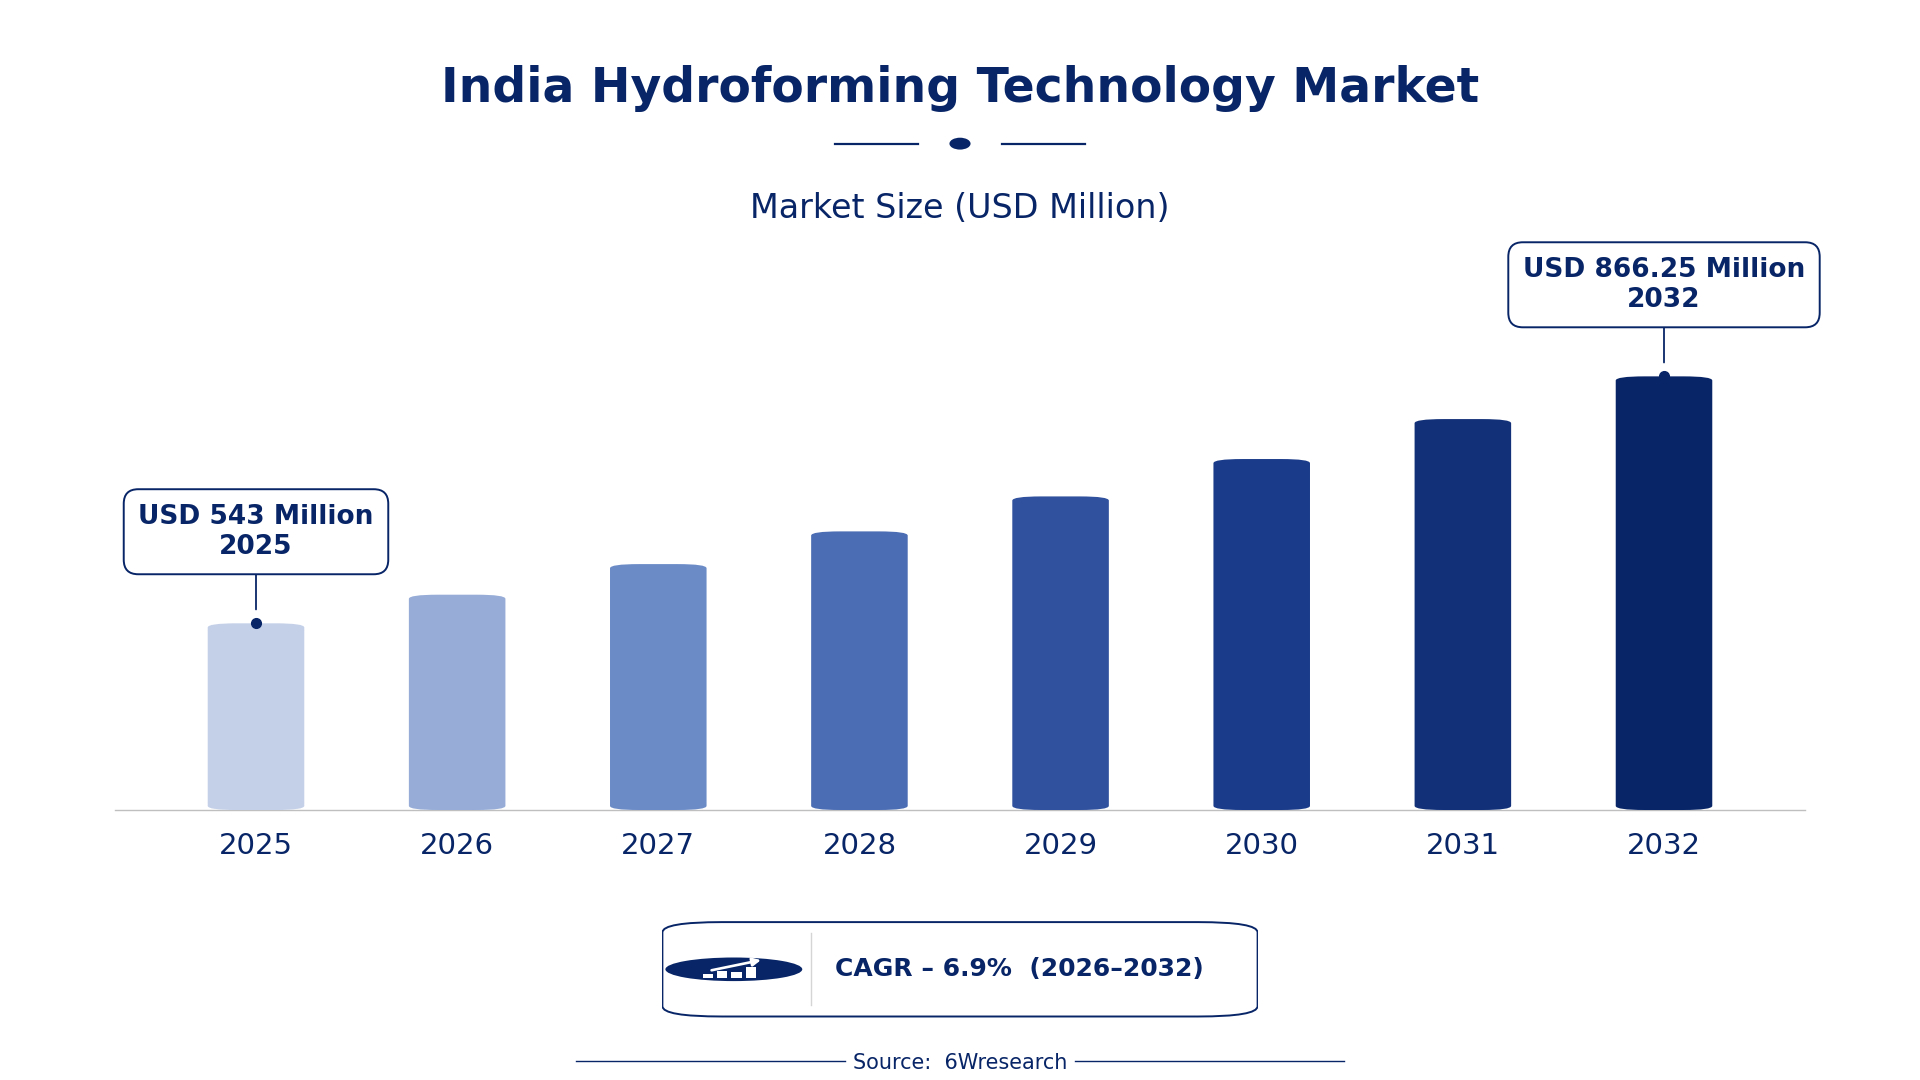
According to 6Wresearch internal database and industry insights, the India Hydroforming Technology Market was valued at USD 543.0 million in 2025 and is projected to reach USD 866.25 million by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
India Hydroforming Technology Market Highlights
| Report Metric | Details |
| Report Name | India Hydroforming Technology Market |
| Market Size 2025 | USD 543.0 million |
| Market Size 2032 | USD 866.25 million |
| Absolute Growth 2025–2032 | USD 323.25 million |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 8.6% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology Type, 2025 | Tube Hydroforming (41% share) |
| Leading Process Type, 2025 | Internal Pressure Forming (39% share) |
| Leading Material Handled, 2025 | Steel/Aluminum Tubes (47% share) |
| Leading End User, 2025 | Automotive Manufacturers (51% share) |
| Fastest-Growing Technology Type | Sheet Hydroforming (8.2% CAGR) |
| Fastest-Growing Process Type | High-Pressure Forming (9.0% CAGR) |
| Fastest-Growing Material Handled | Thin Metal Sheets (8.1% CAGR) |
| Fastest-Growing End User | Aerospace OEMs (8.5% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Automotive Manufacturers, Aerospace OEMs, Metal Forming Industries, Industrial Fabricators |
India Hydroforming Technology Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
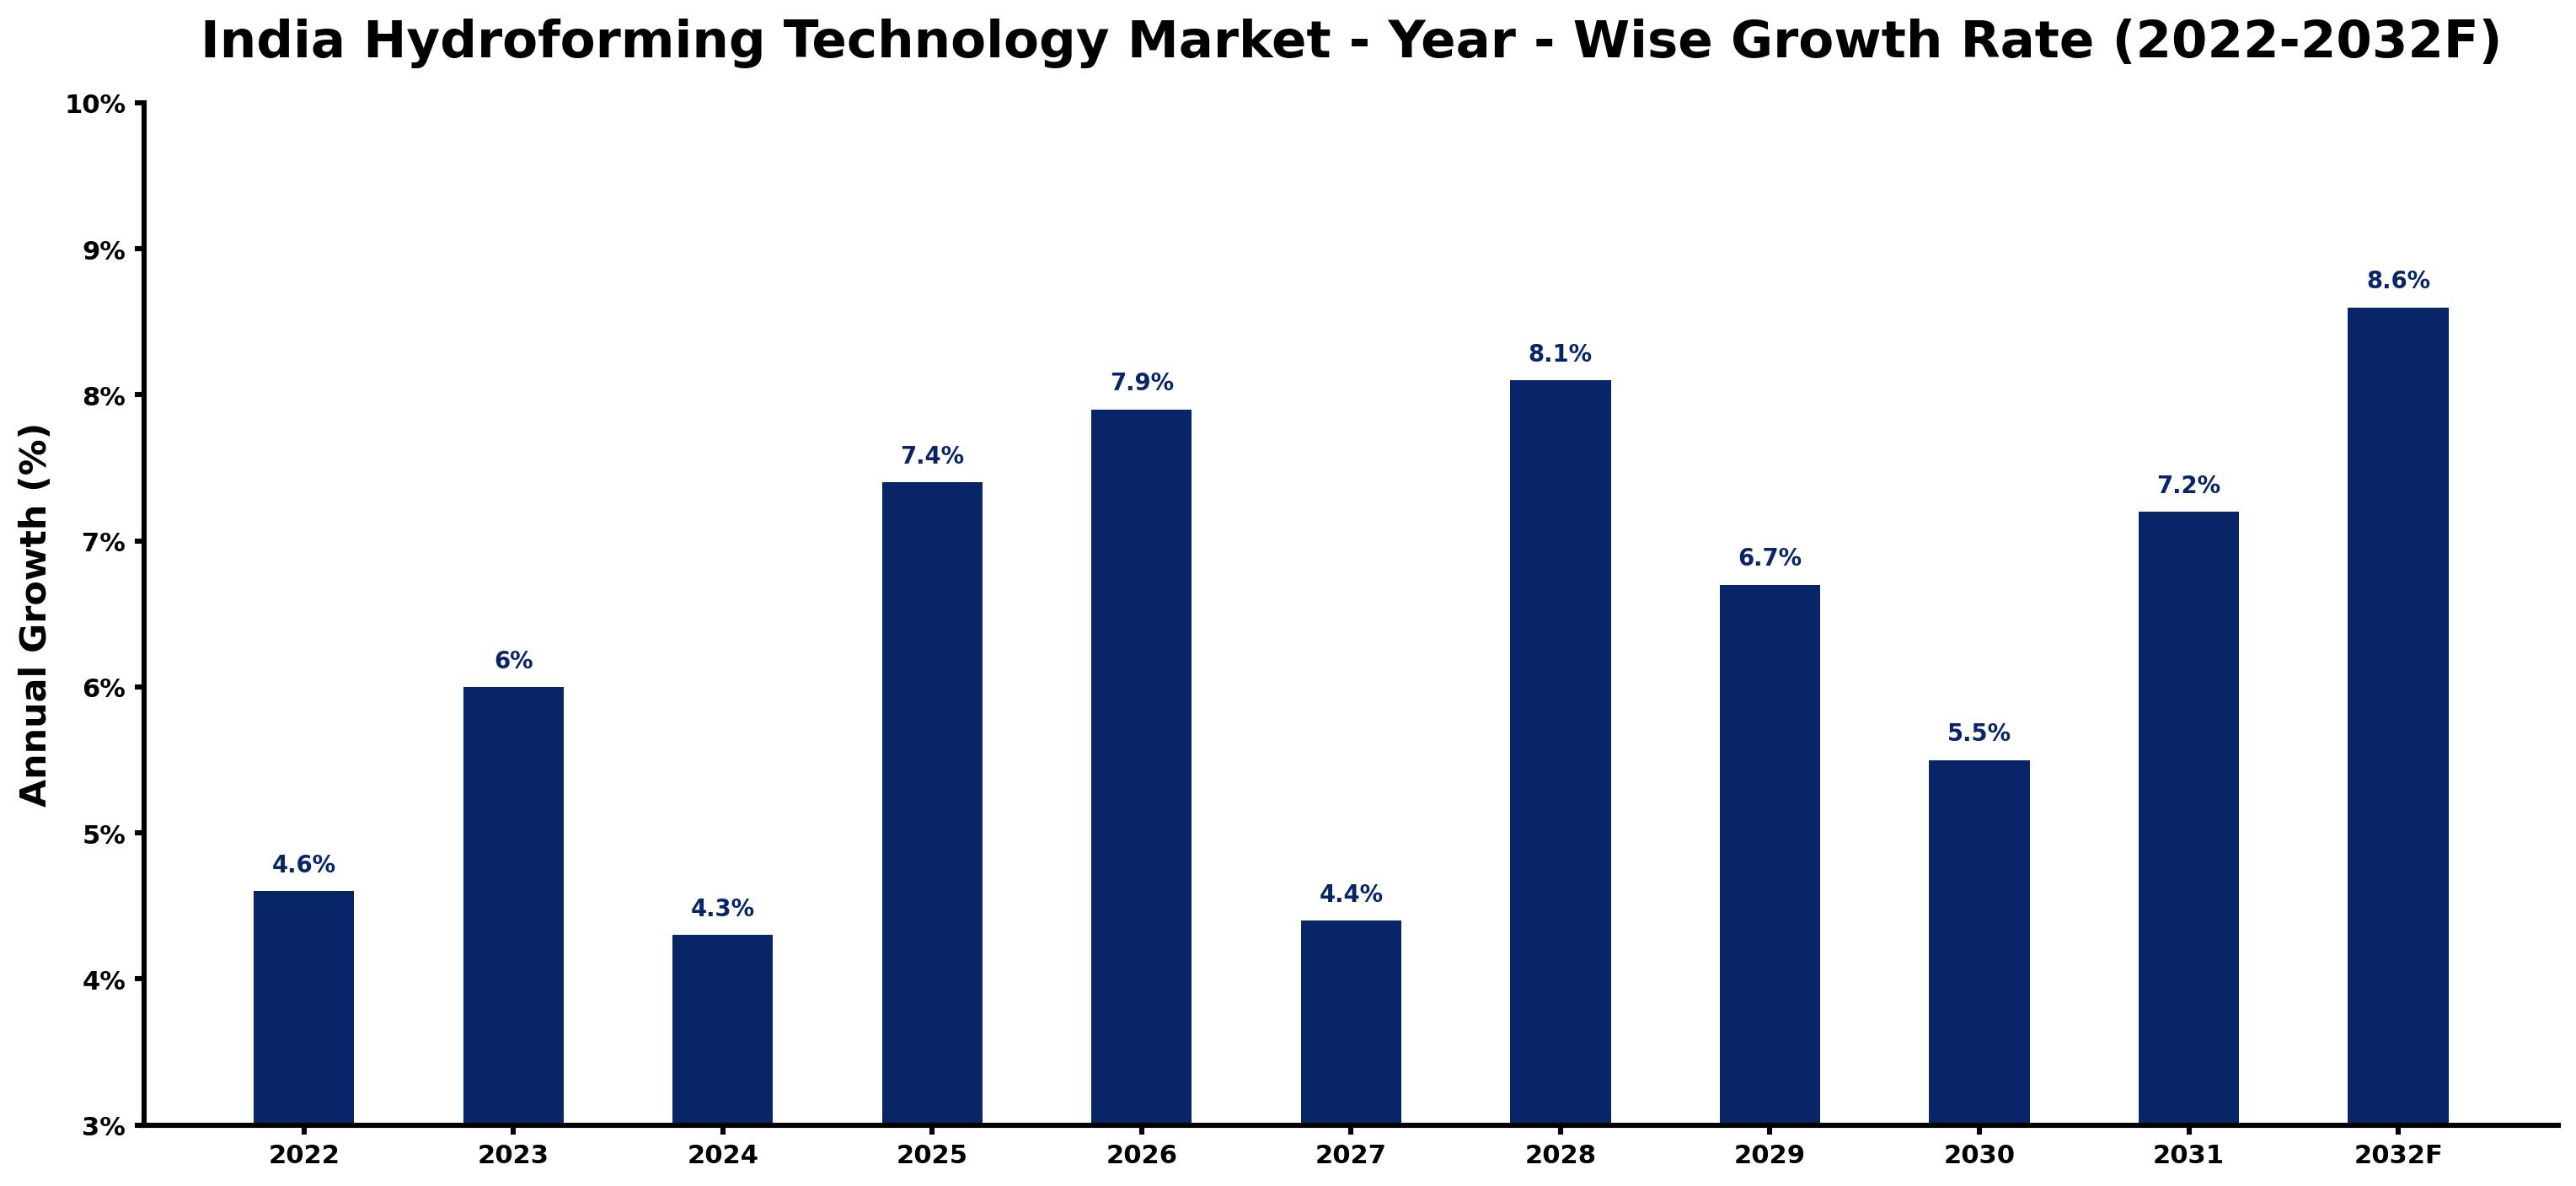
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.6 | The market experienced steady growth due to ongoing demand from automotive manufacturers. |
| 2023 | 6.0 | Growth accelerated as domestic production increased, supported by the Make in India initiative. |
| 2024 | 4.3 | Growth slowed slightly as manufacturers adjusted to market dynamics and demand patterns. |
| 2025 | 7.4 | The market rebounded with higher growth driven by the Automotive Mission Plan 2026. |
| 2026 | 7.9 | Growth continued as investments in advanced manufacturing technologies gained momentum. |
| 2027 | 4.4 | A slowdown occurred as the market adjusted to new production standards and capacities. |
| 2028 | 8.1 | Growth picked up again, driven by rising aerospace sector demands and innovations. |
| 2029 | 6.7 | The market experienced a slowdown as competition intensified among manufacturers. |
| 2030 | 5.5 | Growth slowed further as manufacturers faced challenges in meeting evolving standards. |
| 2031 | 7.2 | The market rebounded with renewed investments and demand from automotive manufacturers. |
| 2032 | 8.6 | Growth peaked as the aerospace sector expanded, increasing the need for hydroforming technology. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Hydroforming Technology Market Synopsis
This method is predominantly applied in the automotive and aerospace sectors to create lightweight components that improve structural integrity. The India Hydroforming Technology Market is expanding due to increasing domestic production demands and initiatives like the Automotive Mission Plan 2026, which aims for a production of 50 million vehicles. Furthermore, the aerospace industry is set for notable growth, further elevating the need for advanced manufacturing techniques. With ongoing investments in technology and infrastructure, the market is well-positioned for significant growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic production demands from automotive manufacturers drive the need for advanced manufacturing techniques. | Driver | High | Internal Pressure Forming |
| Increasing aerospace sector growth necessitates lightweight components, boosting hydroforming technology adoption. | Driver | High | Sheet Hydroforming |
| The Indian government allocated $1.5 billion for aerospace and defense development, enhancing manufacturing capabilities. | Opportunity | High | Aerospace OEMs |
| The ongoing Make in India initiative encourages local production of automotive components, creating demand. | Opportunity | High | Automotive Manufacturers |
| Manufacturers face challenges in meeting ISO 9001:2015 certification requirements, affecting operational efficiency. | Restraint | Medium | Metal Forming Industries |
| Limited awareness of hydroforming technology among smaller manufacturers restricts market penetration. | Restraint | Medium | Industrial Fabricators |
| High initial investment costs for advanced hydroforming equipment can deter new entrants into the market. | Challenge | High | Aerospace OEMs |
| Supply chain disruptions can delay the availability of critical materials for hydroforming processes. | Challenge | Medium | Automotive Manufacturers |
Evaluation of Drivers in India Hydroforming Technology Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in advanced manufacturing technologies are driving demand for hydroforming processes. | Internal Pressure Forming | The Automotive Mission Plan 2026 targets a production of 50 million vehicles, increasing the need for efficient manufacturing processes. |
| Growing demand for lightweight components in the aerospace sector is boosting hydroforming technology. | Sheet Hydroforming | The aerospace industry in India is projected to grow at a CAGR of 15% from 2021 to 2026, increasing the need for advanced manufacturing techniques. |
| The Make in India initiative is encouraging local production, boosting the hydroforming market. | Automotive Manufacturers | This initiative supports the development of domestic manufacturing capabilities, leading to increased adoption of hydroforming. |
| The National Automotive Testing and R&D Infrastructure Project supports advanced manufacturing processes. | High-Pressure Forming | By funding research and development, this project improves the capabilities of manufacturers in the automotive sector. |
| The National Aerospace and Defense Policy aims to strengthen domestic manufacturing capabilities. | Aerospace OEMs | This policy promotes indigenous production, increasing demand for hydroforming methods. |
Growth in the Hydroforming Technology market in India comes from increased investments in advanced manufacturing technologies, rising domestic production demands, and the growth of the aerospace sector. The automotive industry employs over 37 million people, creating substantial demand for efficient manufacturing processes. Additionally, the National Automotive Testing and R&D Infrastructure Project funds research to improve manufacturing capabilities, enhancing overall market potential.
Evaluation of Restraints in India Hydroforming Technology Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs for advanced hydroforming equipment limit market entry. | Aerospace OEMs | New entrants may struggle to afford the necessary technology, impacting competition. |
| Limited awareness of hydroforming technology among smaller manufacturers restricts market penetration. | Industrial Fabricators | This lack of knowledge prevents potential buyers from adopting advanced manufacturing techniques. |
| Manufacturers face challenges in meeting ISO 9001:2015 certification requirements, affecting operational efficiency. | Metal Forming Industries | Compliance costs can hinder smaller firms from competing effectively in the market. |
| Supply chain disruptions can delay the availability of critical materials for hydroforming processes. | Automotive Manufacturers | These delays can lead to production bottlenecks and increased costs for manufacturers. |
| Competition from alternative manufacturing methods may limit hydroforming's market share. | Sheet Hydroforming | Other technologies can offer similar benefits at potentially lower costs, attracting buyers. |
India Hydroforming Technology Market Challenges
The rising costs of hydroforming technology in India pose a considerable challenge for automotive manufacturers, with raw material prices inflating production costs by up to 20%. Supply chain disruptions result in delays in acquiring essential components, extending production schedules for manufacturers by 15%. A shortage of skilled workers in advanced manufacturing techniques hampers producers' ability to effectively implement hydroforming technology, potentially reducing operational efficiency by 30%. Increased competition from imported components compels local producers to lower prices, which can diminish profit margins by around 10%.
Trends in the India Hydroforming Technology Market
The trends below show where the India Hydroforming Technology Market is heading.
- Shift from Traditional to Advanced Manufacturing Techniques: Since 2023, the Indian government has promoted advanced manufacturing technologies through the National Automotive Testing and R&D Infrastructure Project, which aims to increase adoption of hydroforming. This shift aims to improve production efficiency and product quality.
- Emergence of Lightweight Materials in Automotive Manufacturing: The Make in India initiative has accelerated the use of lightweight materials in automotive manufacturing, with a focus on hydroforming technology. This trend aligns with the target of producing 50 million vehicles by 2026.
- Increased Focus on Aerospace Component Production: The National Aerospace and Defense Policy, launched in 2020, has driven the demand for hydroforming in aerospace applications, with the sector projected to grow at a CAGR of 15% through 2026.
- Rise in Research and Development for Hydroforming Techniques: In 2023, the Indian Institute of Technology initiated research to improve hydroforming techniques, aiming for better efficiency and material use, which is essential for meeting industry demands.
Investment Opportunities in the India Hydroforming Technology Market
The following opportunities in the India Hydroforming Technology Market pair current demand with a clear way in.
- Timing for Investment in Hydroforming Technology: With the aerospace sector projected to grow at a CAGR of 15% through 2026, now presents an opportune moment to invest in hydroforming technology. This growth generates demand for advanced manufacturing techniques.
- Gap in Advanced Manufacturing Capabilities: The Indian government allocated $1.5 billion for aerospace and defense development, highlighting a gap in advanced manufacturing capabilities. Suppliers can enter by collaborating with local manufacturers to address this demand.
- Growing Demand from Automotive Manufacturers: The Automotive Mission Plan 2026 aims for a production of 50 million vehicles, creating opportunities for hydroforming technology suppliers. Engaging directly with automotive manufacturers can facilitate market entry.
- Expansion of Aerospace OEMs: The increasing emphasis on indigenous production of aerospace components offers an opportunity for hydroforming technology. Suppliers can partner with aerospace OEMs to deliver tailored solutions.
Government Initiatives in the India Hydroforming Technology Market
The National Automotive Policy, launched by the Ministry of Heavy Industries in 2021, aims to enhance manufacturing capabilities in the automotive sector, including hydroforming technology. This policy encourages manufacturers to adopt advanced techniques, improving product quality and efficiency. By promoting local production, it supports the growth of the hydroforming market, aligning with national manufacturing goals. The policy also incentivises investments in technology and infrastructure, creating a favourable environment for innovation. Additionally, the Indian government allocated $1.5 billion for the development of the aerospace and defense sector in 2021, impacting manufacturing technologies.
The Ministry of Heavy Industries oversees the implementation of the Production Linked Incentive Scheme for the automotive sector, updated in 2022. This scheme incentivises manufacturers to adopt advanced technologies like hydroforming, enhancing competitiveness. Furthermore, the Aerospace and Defense Manufacturing Policy, introduced in 2020, promotes indigenous production of components, increasing demand for hydroforming methods. These initiatives aim to strengthen the domestic manufacturing base and encourage technological advancements in production processes.
Future Insight of the India Hydroforming Technology Market
By 2032, buyers and suppliers in the India hydroforming technology market can expect considerable advancements driven by government initiatives and technological improvements. The National Aerospace and Defense Policy aims to boost domestic manufacturing capabilities, while the Automotive Mission Plan 2026 targets a production of 50 million vehicles, creating robust demand for hydroforming applications. Research initiatives from the Indian Institute of Technology will focus on enhancing efficiency and material use in hydroforming processes. The Ministry of Heavy Industries' new programme will promote advanced manufacturing technologies, supporting market expansion.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Technology Type – Tube Hydroforming Dominated, Sheet Hydroforming Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, with a 41% revenue share in 2025, Tube Hydroforming was the largest technology type category. Tube hydroforming holds the largest market share in India as it is essential for producing lightweight components in the automotive sector. The ambitious Automotive Mission Plan 2026, which targets a production of 50 million vehicles, underscores the ongoing demand for this technology. Sheet Hydroforming is set to record the highest CAGR in this split, 8.2% over 2026–2032. Sheet hydroforming is experiencing rapid growth, driven by the aerospace industry's projected CAGR of 15% from 2021 to 2026. This surge in demand for complex shapes in aerospace applications will significantly increase the adoption of sheet hydroforming techniques. Suppliers should focus on enhancing their sheet hydroforming capabilities to capitalise on the growth opportunities within the aerospace sector.
By Process Type – Internal Pressure Forming Dominated, High-Pressure Forming Expected to Grow Fastest
Internal Pressure Forming accounted for a 39% market share by process type in 2025. Internal pressure forming dominates the market due to its widespread use in automotive parts manufacturing, which is crucial for the industry's growth. With over 37 million people employed in the automotive sector, there is a consistent demand for this process. High-Pressure Forming is projected to grow fastest, at a CAGR of 9.0% during 2026–2032. High-pressure forming is the fastest-growing segment, vital for producing high-strength components across various industries. The increasing focus on advanced manufacturing techniques will drive its adoption beyond just automotive applications. Buyers should consider investing in high-pressure forming technologies to meet the rising demand for durable components across multiple sectors.
By Material Handled – Steel/Aluminum Tubes Dominated, Thin Metal Sheets Expected to Grow Fastest
The largest material handled category in 2025 was Steel/Aluminum Tubes, with a 47% share of total revenue. Steel and aluminum tubes are the predominant materials handled in hydroforming, widely used in various applications, particularly in the automotive sector. Their lightweight characteristics are in line with industry trends favouring efficiency and sustainability. Over 2026–2032, Thin Metal Sheets are expected to post the fastest growth, at a CAGR of 8.1%. Thin metal sheets are rapidly gaining traction as they are frequently used for lightweight structures, especially within the aerospace sector. The push for advanced manufacturing techniques will further solidify their market position. Suppliers need to adjust their strategies to incorporate thin metal sheets to meet the growing demands of lightweight manufacturing.
By End User – Automotive Manufacturers Dominated, Aerospace OEMs Expected to Grow Fastest
Automotive Manufacturers held a 51% share of the India Hydroforming Technology Market by end user in 2025. Automotive manufacturers are the leading end-users of hydroforming technology in India, capturing the largest market share. The sector's ambitious production goals and substantial workforce ensure a steady demand for hydroformed components. The quickest growth will come from Aerospace OEMs, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Aerospace OEMs are the fastest-growing end-user segment, fuelled by the need for lightweight and strong components in the expanding aerospace industry. Government initiatives aimed at enhancing aerospace manufacturing capabilities will further accelerate this growth. Suppliers should tailor their products to meet the specific needs of aerospace OEMs in order to take advantage of this rapidly expanding market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Hydroforming Technology Market Outlook
- Market Size of India Hydroforming Technology Market, 2025
- Forecast of India Hydroforming Technology Market, 2032
- Historical Data and Forecast of India Hydroforming Technology Revenues & Volume for the Period 2022 - 2032F
- India Hydroforming Technology Market Trend Evolution
- India Hydroforming Technology Market Drivers and Challenges
- India Hydroforming Technology Price Trends
- India Hydroforming Technology Porter's Five Forces
- India Hydroforming Technology Industry Life Cycle
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Tube Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Sheet Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Warm Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Dual Chamber Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Internal Pressure Forming for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By High-Pressure Forming for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Thermal Assisted for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Integrated Flow for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Material Handled for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Steel/Aluminum Tubes for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Thin Metal Sheets for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By High-Strength Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Complex Geometries for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Automotive Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Metal Forming Industries for the Period 2022 - 2032F
- Historical Data and Forecast of India Hydroforming Technology Market Revenues & Volume By Industrial Fabricators for the Period 2022 - 2032F
- India Hydroforming Technology Import Export Trade Statistics
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By Material Handled
- Market Opportunity Assessment By End User
- India Hydroforming Technology Top Companies Market Share
- India Hydroforming Technology Competitive Benchmarking By Technical and Operational Parameters
- India Hydroforming Technology Company Profiles
- India Hydroforming Technology Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Technology Type
- Tube Hydroforming
- Sheet Hydroforming
- Warm Hydroforming
- Dual Chamber Systems
By Process Type
- Internal Pressure Forming
- High-Pressure Forming
- Thermal Assisted
- Integrated Flow
By Material Handled
- Steel/Aluminum Tubes
- Thin Metal Sheets
- High-Strength Alloys
- Complex Geometries
By End User
- Automotive Manufacturers
- Aerospace OEMs
- Metal Forming Industries
- Industrial Fabricators































