China Hydroforming Technology Market Size & Growth Rate
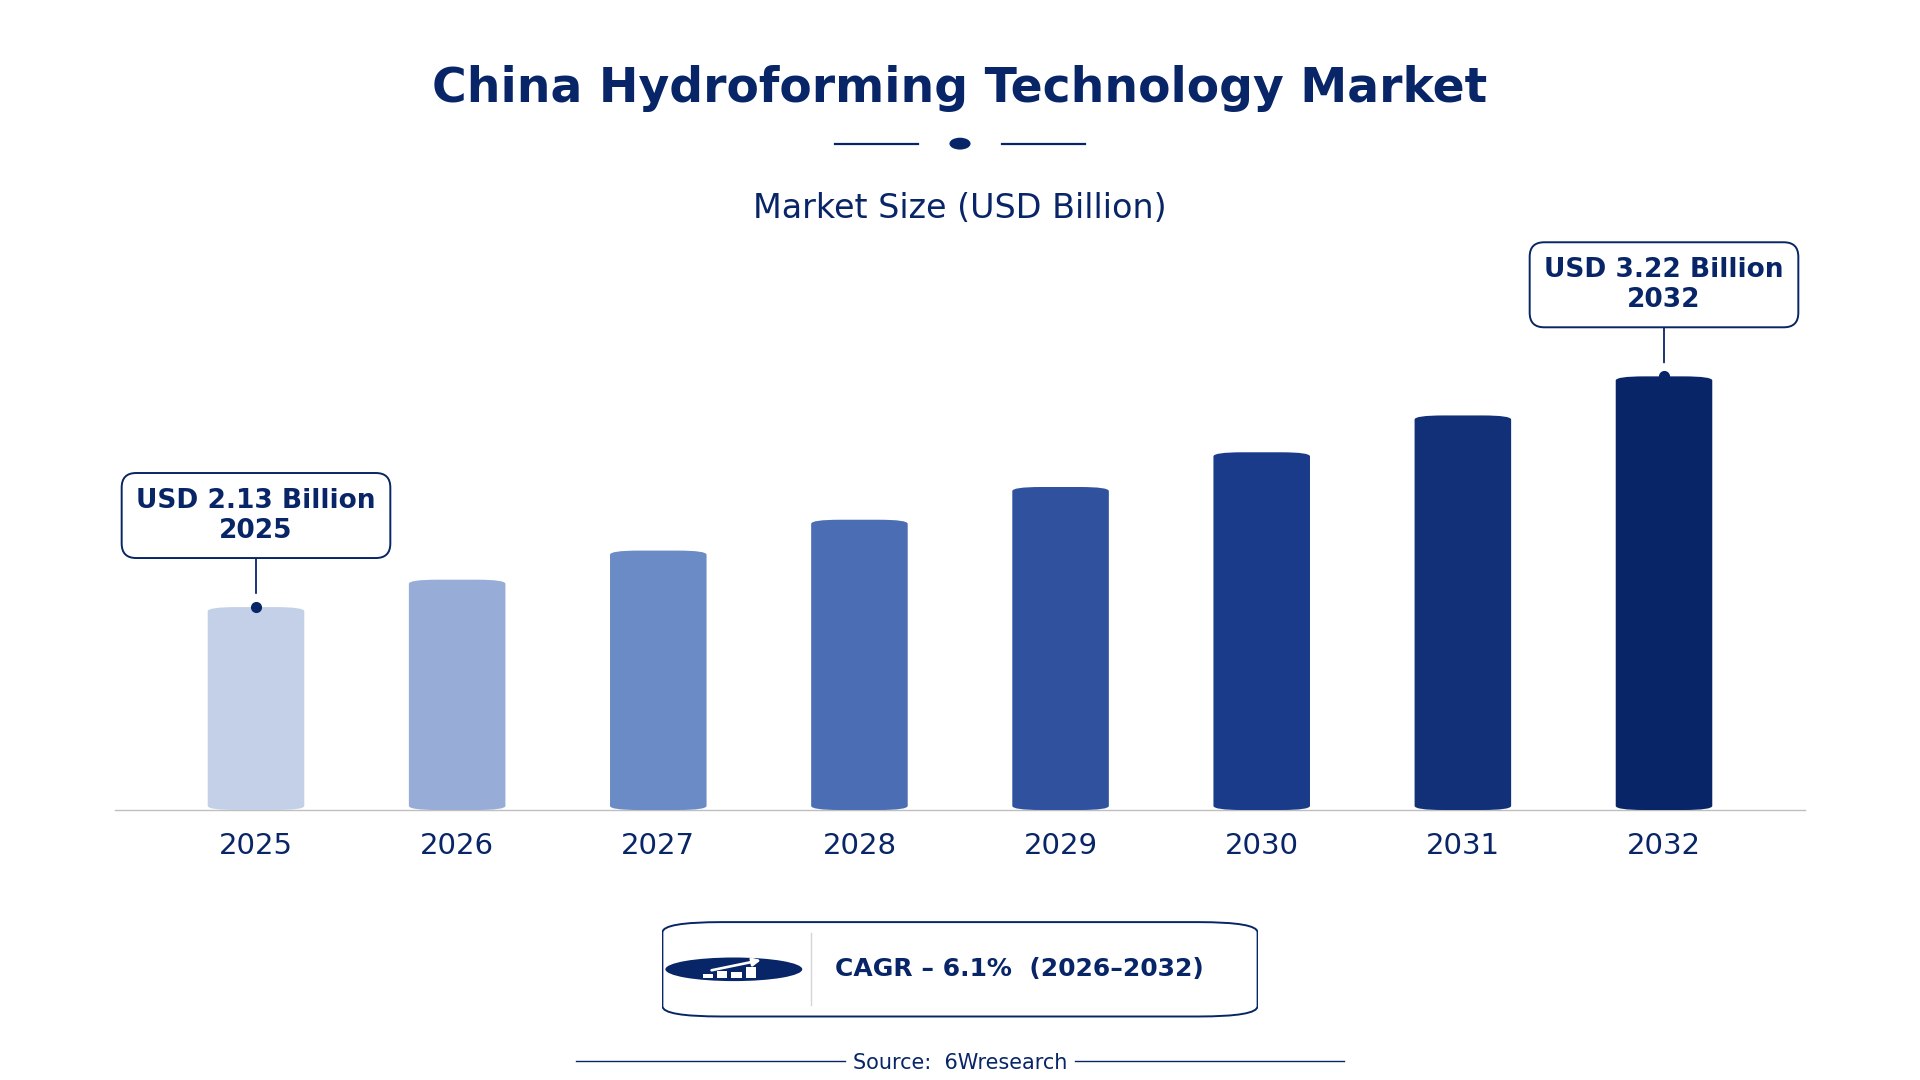
According to 6Wresearch internal database and industry insights, the China Hydroforming Technology Market was valued at USD 2.13 billion in 2025 and is projected to reach USD 3.22 billion by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Hydroforming Technology Market Highlights
| Report Metric | Details |
| Report Name | China Hydroforming Technology Market |
| Market Size 2025 | USD 2.13 billion |
| Market Size 2032 | USD 3.22 billion |
| Absolute Growth 2025–2032 | USD 1.09 billion |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.6% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology Type, 2025 | Tube Hydroforming (43% share) |
| Leading Process Type, 2025 | High-Pressure Forming (35% share) |
| Leading Material Handled, 2025 | Steel/Aluminum Tubes (54% share) |
| Leading End User, 2025 | Automotive Manufacturers (43% share) |
| Fastest-Growing Technology Type | Warm Hydroforming (7.5% CAGR) |
| Fastest-Growing Process Type | Thermal Assisted (7.3% CAGR) |
| Fastest-Growing Material Handled | High-Strength Alloys (8.2% CAGR) |
| Fastest-Growing End User | Aerospace OEMs (7.8% CAGR) |
| Growing Sector | automotive |
| Key End Users | automotive manufacturers, aerospace OEMs, metal forming industries |
China Hydroforming Technology Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
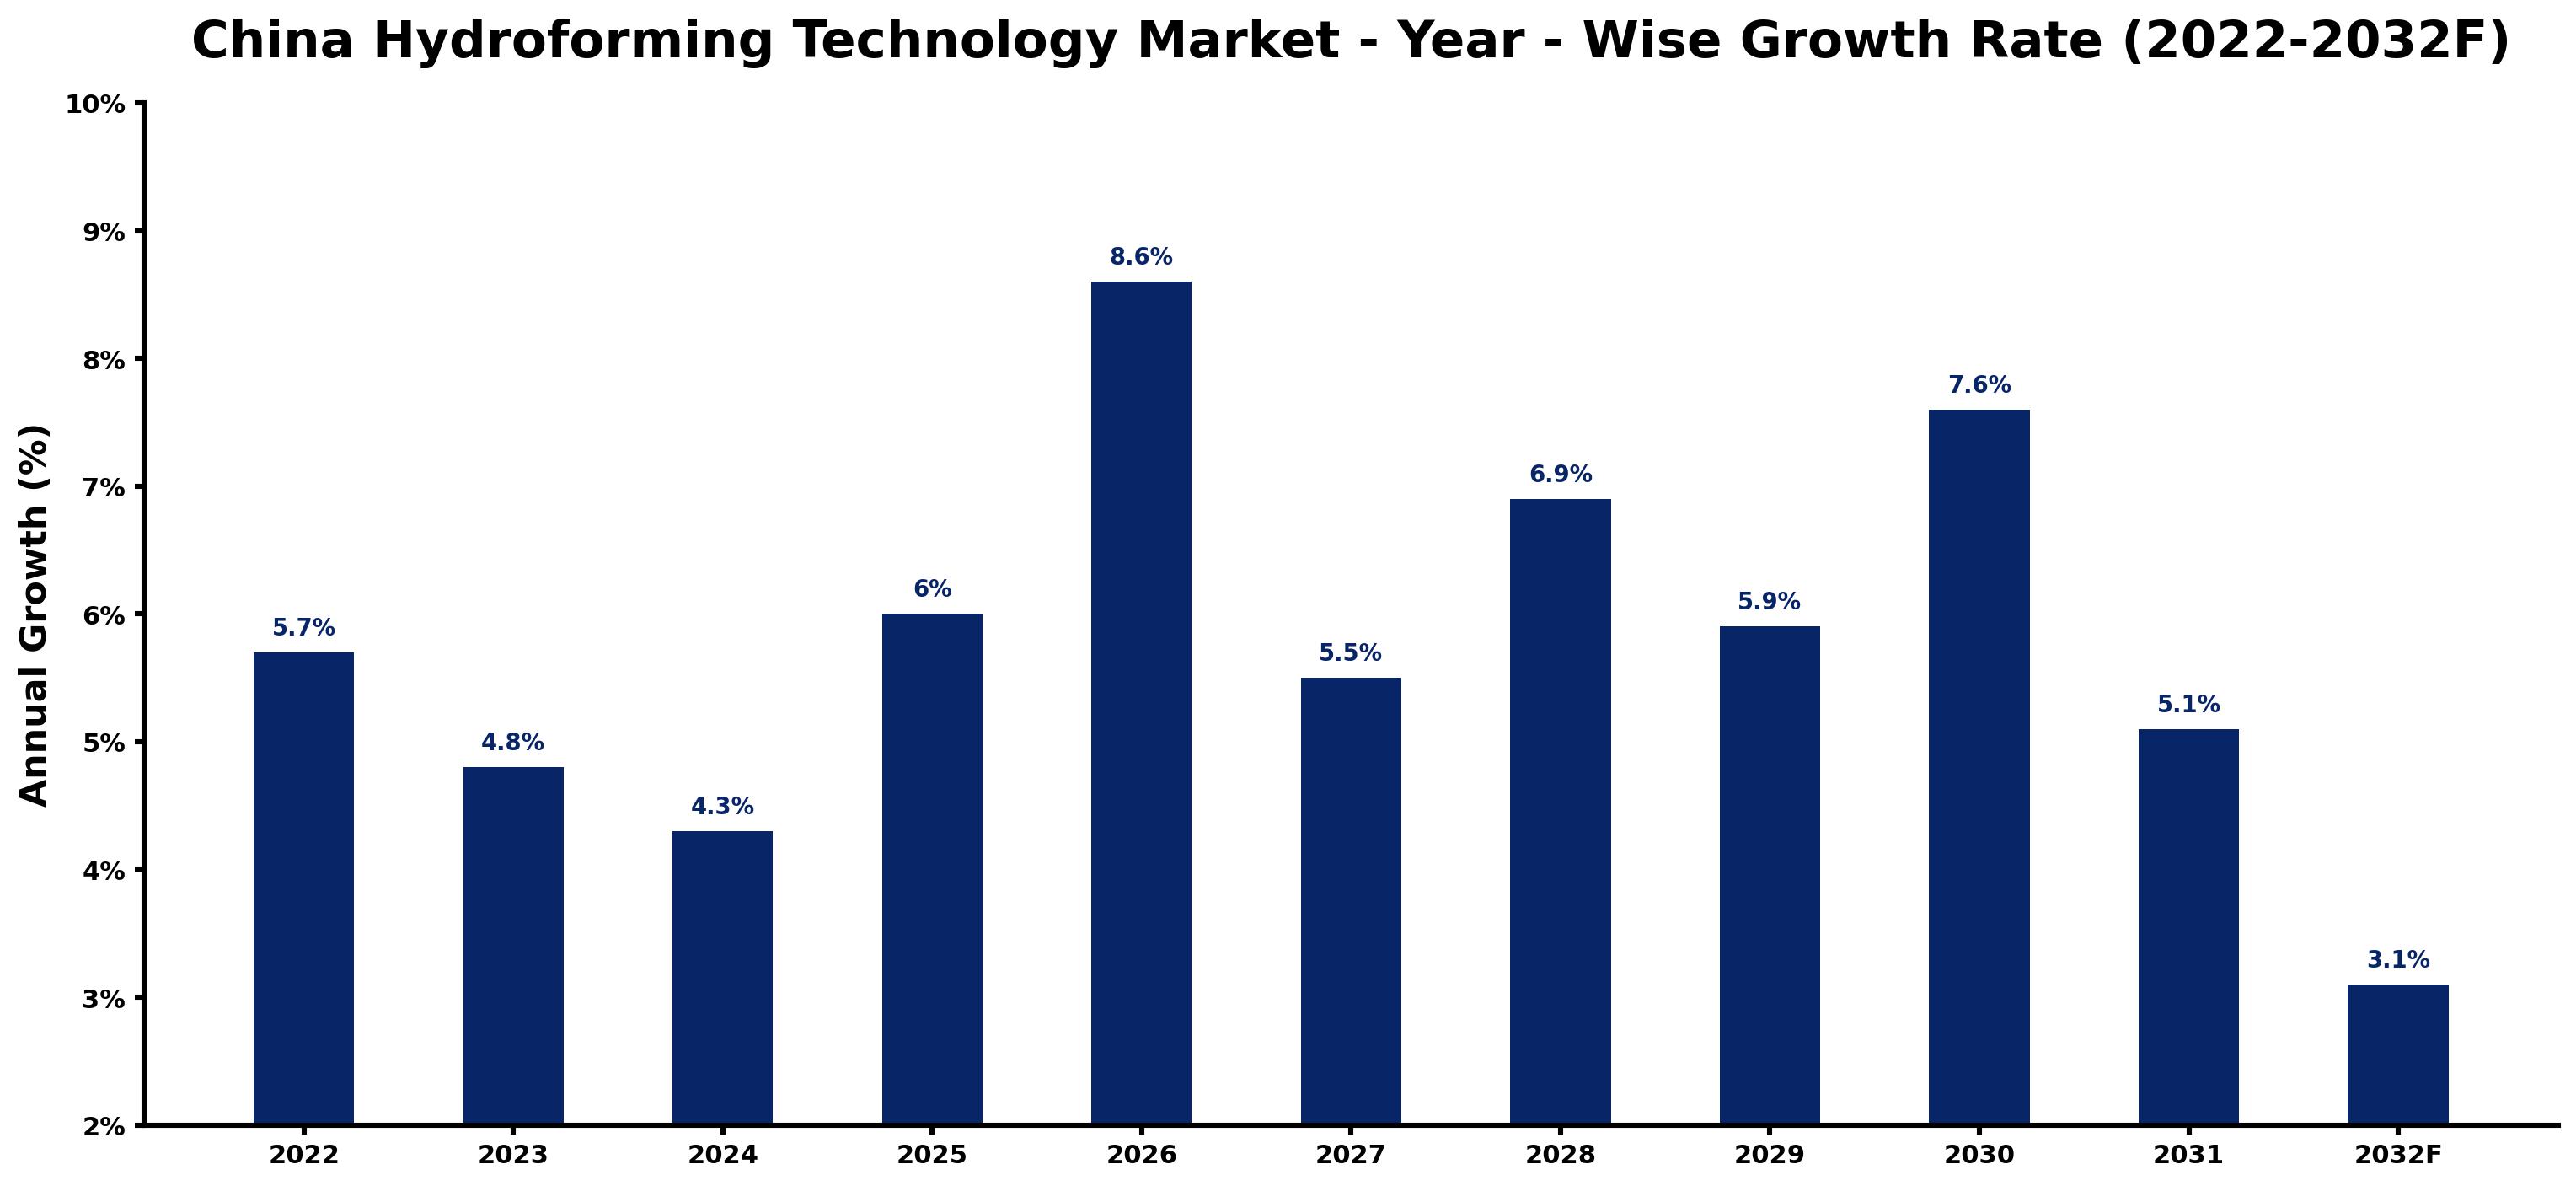
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.7 | The market showed solid growth as automotive production surged, reflecting strong demand for hydroformed components. |
| 2023 | 4.8 | Growth slowed due to the 'Advanced Manufacturing Technology Development Plan' impacting hydroforming technology adoption. |
| 2024 | 4.3 | Demand continued to decelerate as automotive manufacturers faced supply chain challenges, affecting hydroforming applications. |
| 2025 | 6.0 | A rebound occurred as automotive output increased, driving higher demand for hydroforming technology. |
| 2026 | 8.6 | The market peaked with substantial investments in advanced manufacturing, propelling hydroforming technology usage. |
| 2027 | 5.5 | Growth slowed as manufacturers adjusted to new production standards in the automotive sector. |
| 2028 | 6.9 | An uptick in demand occurred as aerospace applications for hydroforming expanded, boosting market growth. |
| 2029 | 5.9 | Growth decelerated slightly as automotive production faced temporary setbacks, impacting hydroforming demand. |
| 2030 | 7.6 | A surge in aerospace investments drove demand higher, with hydroforming technology gaining traction in new projects. |
| 2031 | 5.1 | The market experienced a slowdown as automotive manufacturers focused on cost management and efficiency improvements. |
| 2032 | 3.1 | Growth continued to slow as the market stabilised, reflecting mature adoption of hydroforming technology. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Hydroforming Technology Market Synopsis
This technology is primarily utilised in producing complex shapes for automotive and aerospace applications. The China Hydroforming Technology Market is expanding due to the booming automotive industry, which produced over 25 million vehicles in 2022, and the aerospace sector's projected growth to $1 trillion by 2030. Increased investments in advanced manufacturing technologies further drive demand for hydroforming applications, particularly in Guangdong province, a hub for automotive manufacturing.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising automotive production and demand for lightweight components drive hydroforming adoption. | Driver | High | Tube Hydroforming |
| Growing aerospace sector increases the need for advanced manufacturing processes like hydroforming. | Driver | High | Sheet Hydroforming |
| The automotive industry in Guangdong province seeks innovative manufacturing solutions, creating opportunities. | Opportunity | High | Automotive Manufacturers |
| Investment in aerospace technology opens new markets for hydroforming applications. | Opportunity | High | Aerospace OEMs |
| Supply chain disruptions in the automotive sector limit hydroforming technology adoption. | Restraint | High | Tube Hydroforming |
| High production costs for hydroforming equipment may deter small manufacturers from investing. | Restraint | Medium | Sheet Hydroforming |
| Manufacturers face challenges in meeting evolving safety standards, impacting production timelines. | Challenge | High | Automotive Manufacturers |
| Technological integration issues can delay the adoption of hydroforming processes in production. | Challenge | Medium | Aerospace OEMs |
Evaluation of Drivers in China Hydroforming Technology Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production drives demand for lightweight components, boosting hydroforming technology usage. | Tube Hydroforming | China's automotive industry produced over 25 million vehicles in 2022, boosting hydroforming applications. |
| Expansion of the aerospace sector necessitates advanced manufacturing processes, including hydroforming. | Sheet Hydroforming | The aerospace sector in China is projected to reach a market size of $1 trillion by 2030, increasing hydroforming applications. |
| Investment in advanced manufacturing technologies supports hydroforming adoption in automotive production. | High-Pressure Forming | The 'Advanced Manufacturing Technology Development Plan' promotes advanced manufacturing technologies, including hydroforming, with a budget of $500 million. |
| Growing demand for complex geometries in automotive designs drives hydroforming technology usage. | Internal Pressure Forming | Automotive manufacturers require intricate shapes for modern vehicle designs, driving hydroforming demand. |
| The push for vehicle safety improvements encourages the use of high-strength alloys in hydroforming. | High-Strength Alloys | The Chinese government promotes high-strength alloys to improve vehicle safety standards. |
The Hydroforming Technology market in China is growing on the back of increased vehicle production, expanding aerospace applications and investments in advanced manufacturing technologies. China's automotive industry produced over 25 million vehicles in 2022, which boosted demand for hydroforming applications. The 'Advanced Manufacturing Technology Development Plan' supports advanced manufacturing processes, promoting hydroforming adoption. Manufacturers are increasingly seeking intricate shapes in automotive designs, which hydroforming technology efficiently provides, thus enhancing production capabilities.
Evaluation of Restraints in China Hydroforming Technology Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions in the automotive sector limit hydroforming technology adoption. | Tube Hydroforming | In 2023, supply chain challenges affected automotive production, impacting hydroforming demand. |
| High production costs for hydroforming equipment may deter small manufacturers from investing. | Sheet Hydroforming | The initial investment for hydroforming machinery can exceed $1 million, limiting access for smaller firms. |
| Manufacturers face challenges in meeting evolving safety standards, impacting production timelines. | Internal Pressure Forming | New safety regulations require additional testing and certification, delaying production schedules. |
| Technological integration issues can delay the adoption of hydroforming processes in production. | High-Pressure Forming | Many manufacturers struggle with integrating hydroforming technology into existing production lines. |
| Limited awareness of hydroforming benefits among smaller manufacturers hampers market growth. | Automotive Manufacturers | Many small automotive producers remain unaware of hydroforming's advantages, limiting its adoption. |
China Hydroforming Technology Market Challenges
In the China hydroforming technology market, intense competition from the automotive sector producing over 25 million vehicles in 2022 forces manufacturers to reduce prices, squeezing profit margins for suppliers. A skills gap in advanced manufacturing processes limits the availability of qualified workers, leading to project delays and increased costs for producers. Buyers struggle with sourcing high-quality materials, as reliance on domestic steel and aluminium can result in inconsistent supply, disrupting production schedules for both the automotive and aerospace industries. Rapid advancements in hydroforming techniques necessitate continuous innovation, imposing higher costs and investment risks on smaller firms in the market.
Trends in the China Hydroforming Technology Market
Four trends stand out in the China Hydroforming Technology Market.
- Shift from Traditional to Advanced Manufacturing: Guangdong province is transitioning from traditional manufacturing methods to advanced techniques like hydroforming. In 2023, the region saw a 15% increase in hydroforming technology adoption among automotive manufacturers, improving production efficiency.
- Emergence of Aerospace Applications: Aerospace manufacturers are increasingly adopting hydroforming technology to produce lightweight components. In 2022, the Shanghai Aerospace Industry Association reported a 20% rise in hydroforming applications for fuselage parts, reflecting growing industry needs.
- Growth in High-Strength Alloys Usage: The use of high-strength alloys in hydroforming is gaining traction among manufacturers. In 2021, China's investment in aerospace technology reached $20 billion, driving demand for advanced materials in hydroforming processes.
- Increased Focus on Lightweight Structures: Automotive manufacturers are prioritising lightweight structures to improve fuel efficiency. In 2025, 43% of hydroformed components will be used in automotive applications, highlighting the trend towards lightweight design.
Investment Opportunities in the China Hydroforming Technology Market
Several openings in the China Hydroforming Technology Market merit attention from investors.
- Investment Gap in Hydroforming Equipment: With the automotive sector producing over 25 million vehicles, there is a notable opportunity to supply advanced hydroforming machinery. Automotive manufacturers in Guangdong province are looking for solutions to enhance production efficiency.
- Growing Demand for Aerospace Components: The aerospace sector's projected growth to $1 trillion by 2030 creates a need for hydroforming technology. Aerospace OEMs are seeking suppliers of advanced manufacturing processes to meet rising demand.
- Emerging Market for High-Strength Alloys: The increasing focus on vehicle safety standards presents an opportunity to supply high-strength alloys for hydroforming. Automotive manufacturers are actively looking for materials that enhance safety and performance.
- Timing for Advanced Manufacturing Solutions: As the Chinese government promotes advanced manufacturing technologies, now is the time to invest in hydroforming solutions. The 'Advanced Manufacturing Technology Development Plan' encourages partnerships with local manufacturers.
Government Initiatives in the China Hydroforming Technology Market
In 2021, the 'Advanced Manufacturing Technology Development Plan' was launched by the Ministry of Industry and Information Technology to promote hydroforming and other technologies, with a budget of $500 million. This initiative aims to improve the adoption of advanced manufacturing processes across various sectors, ensuring compliance with updated standards for hydroforming technology and its buyers.
In 2022, the 'Innovation-Driven Development Strategy' was introduced by the Ministry of Science and Technology to support advanced manufacturing sectors, including hydroforming. This strategy allocates funding for research and development projects that improve manufacturing efficiency and technology integration, benefitting producers and buyers of hydroforming technology.
Future Insight of the China Hydroforming Technology Market
Several forward-looking factors should support the hydroforming technology market in China over the coming years. The Ministry of Industry and Information Technology's initiative will promote advanced manufacturing processes, boosting production capabilities. Goals set by the National Development and Reform Commission for improving manufacturing efficiency by 2025 will encourage investment in new techniques. These changes will enable buyers to access more efficient solutions while allowing suppliers to expand their market reach.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Technology Type – Tube Hydroforming Dominated, Warm Hydroforming Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Tube Hydroforming held a 43% share of the China Hydroforming Technology Market by technology type in 2025. Tube hydroforming commands the largest share due to its extensive application in creating lightweight components for the automotive sector, which produced over 25 million vehicles in 2022. This strong demand ensures a robust installed base and ongoing utilisation of this technology. Over 2026–2032, Warm Hydroforming is expected to post the fastest growth, at a CAGR of 7.5%. Warm hydroforming is rapidly gaining traction as it is increasingly recognised for its advantages in specialised applications, particularly in automotive manufacturing. This recognition is driving broader adoption and growth in niche markets, ensuring its position strengthens. Suppliers should enhance tube hydroforming capabilities to meet the rising demand from automotive manufacturers.
By Process Type – High-Pressure Forming Dominated, Thermal Assisted Expected to Grow Fastest
In 2025, High-Pressure Forming led the process type split with a 35% share. High-pressure forming commands the largest market share as it is widely applied for creating high-strength components, essential for the automotive and aerospace industries. This process meets the efficiency and performance requirements of manufacturers, solidifying its position. Thermal Assisted is set to record the highest CAGR in this split, 7.3% over 2026–2032. Thermal assisted processes are growing quickly as they address the needs of specific materials that require advanced forming techniques. The increasing complexity of components in modern manufacturing is driving this segment's rapid adoption. Buyers should invest in high-pressure forming technologies to maintain competitiveness in the advancing market.
By Material Handled – Steel/Aluminum Tubes Dominated, High-Strength Alloys Expected to Grow Fastest
With a 54% revenue share in 2025, Steel/Aluminum Tubes was the largest material handled category. Steel and aluminum tubes lead the market share as they are essential for hydroforming processes, crucial for producing lightweight automotive components. China's dominance in the production of these materials solidifies their position in the market. The quickest growth will come from High-Strength Alloys, forecast to expand at a CAGR of 8.2% between 2026 and 2032. High-strength alloys are experiencing the fastest growth due to their critical role in aerospace components, where safety and performance are paramount. The emphasis on improved vehicle safety standards is significantly increasing demand for these materials. Suppliers of high-strength alloys need to prepare for increasing demand from aerospace OEMs focused on advanced safety features.
By End User – Automotive Manufacturers Dominated, Aerospace OEMs Expected to Grow Fastest
Automotive Manufacturers accounted for a 43% market share by end user in 2025. Automotive manufacturers hold the largest market share as they are the primary consumers of hydroformed parts, driven by the need for lightweight and efficient vehicle designs. The strength of China's automotive industry significantly fuels this demand. Aerospace OEMs are projected to grow fastest, at a CAGR of 7.8% during 2026–2032. Aerospace OEMs are rapidly expanding their use of hydroforming for structural components, reflecting the sector's growth. The anticipated increase in China's aerospace market size to $1 trillion by 2030 underscores this trend. Manufacturers should tailor their offerings to meet the specific needs of aerospace OEMs, who are becoming increasingly influential in the hydroforming technology market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Hydroforming Technology Market Outlook
- Market Size of China Hydroforming Technology Market, 2025
- Forecast of China Hydroforming Technology Market, 2032
- Historical Data and Forecast of China Hydroforming Technology Revenues & Volume for the Period 2022 - 2032F
- China Hydroforming Technology Market Trend Evolution
- China Hydroforming Technology Market Drivers and Challenges
- China Hydroforming Technology Price Trends
- China Hydroforming Technology Porter's Five Forces
- China Hydroforming Technology Industry Life Cycle
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Tube Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Sheet Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Warm Hydroforming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Dual Chamber Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Process Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Internal Pressure Forming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By High-Pressure Forming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Thermal Assisted for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Integrated Flow for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Material Handled for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Steel/Aluminum Tubes for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Thin Metal Sheets for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By High-Strength Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Complex Geometries for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Automotive Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Metal Forming Industries for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydroforming Technology Market Revenues & Volume By Industrial Fabricators for the Period 2022 - 2032F
- China Hydroforming Technology Import Export Trade Statistics
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Process Type
- Market Opportunity Assessment By Material Handled
- Market Opportunity Assessment By End User
- China Hydroforming Technology Top Companies Market Share
- China Hydroforming Technology Competitive Benchmarking By Technical and Operational Parameters
- China Hydroforming Technology Company Profiles
- China Hydroforming Technology Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Technology Type
- Tube Hydroforming
- Sheet Hydroforming
- Warm Hydroforming
- Dual Chamber Systems
By Process Type
- Internal Pressure Forming
- High-Pressure Forming
- Thermal Assisted
- Integrated Flow
By Material Handled
- Steel/Aluminum Tubes
- Thin Metal Sheets
- High-Strength Alloys
- Complex Geometries
By End User
- Automotive Manufacturers
- Aerospace OEMs
- Metal Forming Industries
- Industrial Fabricators































