India IC Substrate Market Size & Growth Rate
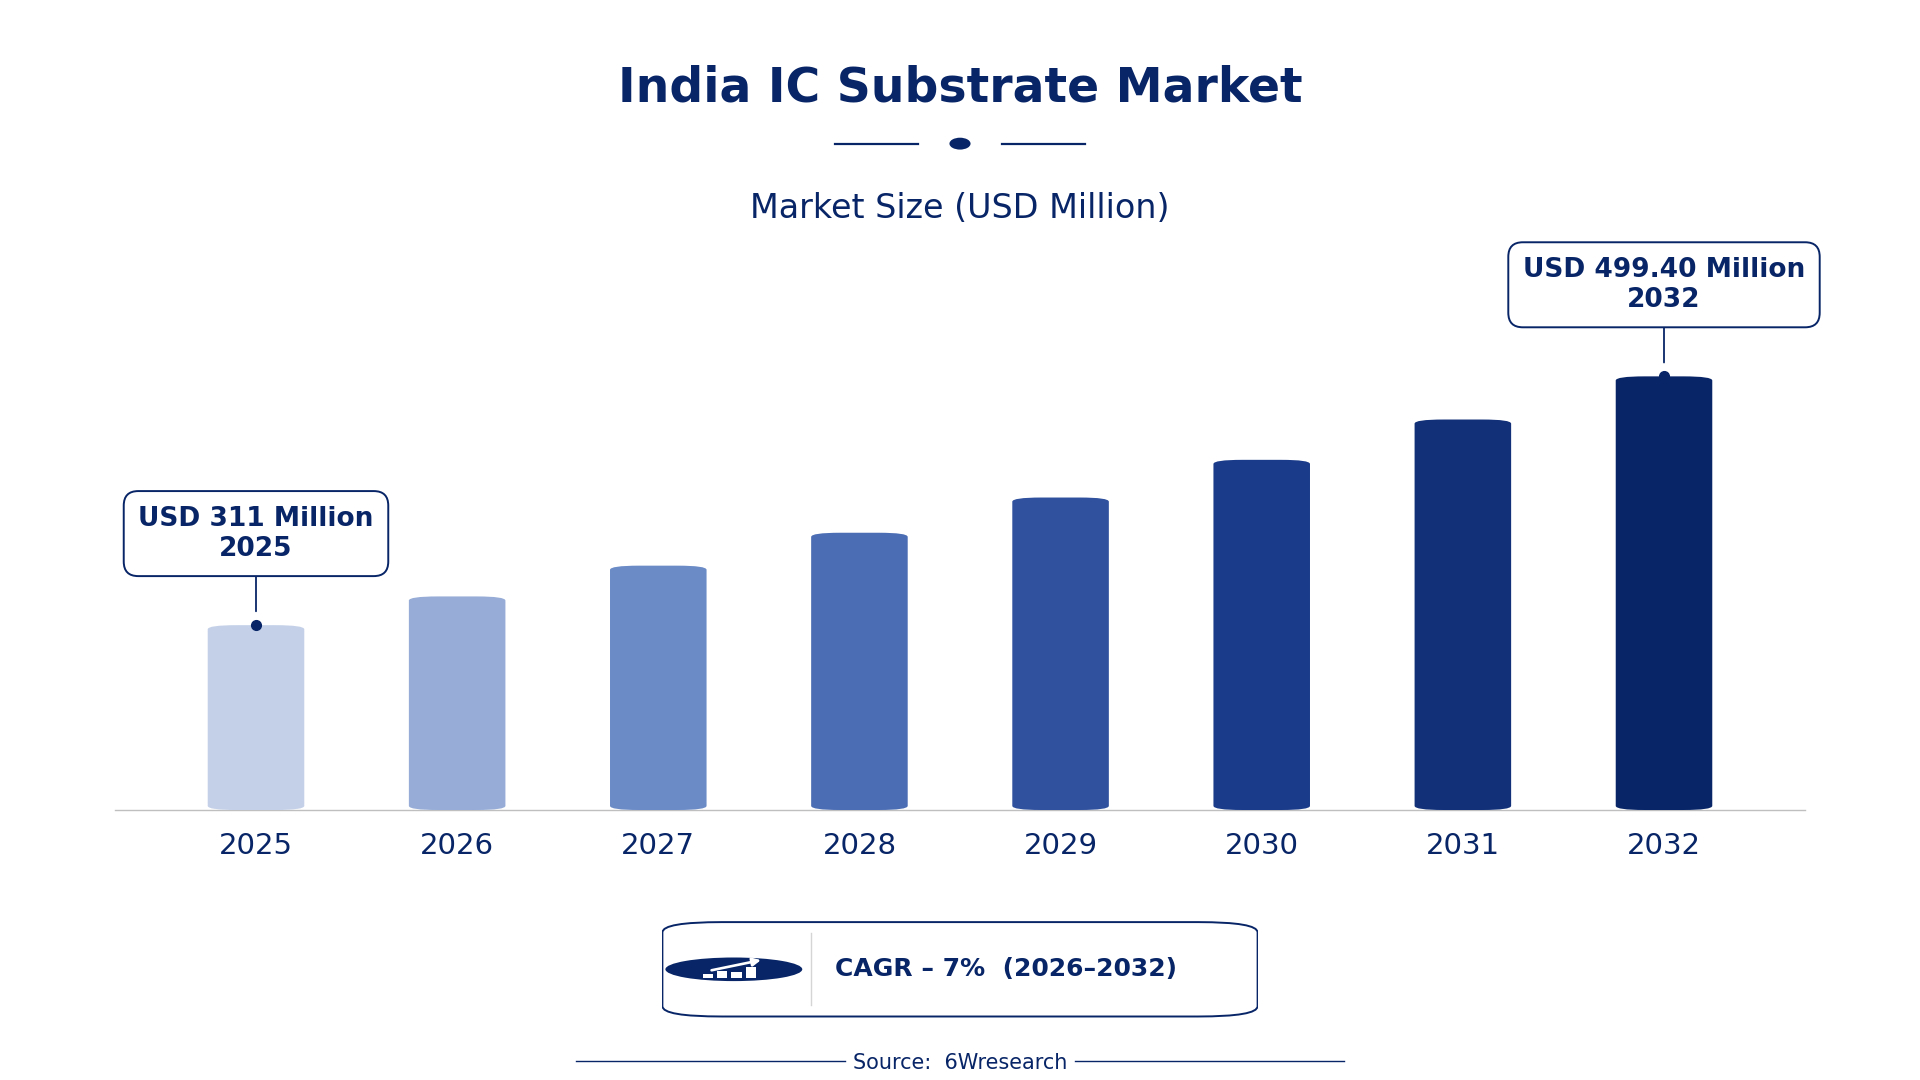
According to 6Wresearch internal database and industry insights, the India IC Substrate Market was valued at USD 311.0 million in 2025 and is projected to reach USD 499.40 million by 2032, growing at a CAGR of approximately 7% during 2026–2032.
India IC Substrate Market Highlights
| Report Metric | Details |
| Report Name | India IC Substrate Market |
| Market Size 2025 | USD 311.0 million |
| Market Size 2032 | USD 499.40 million |
| Absolute Growth 2025–2032 | USD 188.40 million |
| CAGR 2026–2032 | 7% |
| Peak Annual Growth | 9.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Substrate Type, 2025 | Rigid Substrates (37% share) |
| Leading Layer Structure, 2025 | Multilayer PCBs (49% share) |
| Leading Application Segment, 2025 | CPUs/GPUs (38% share) |
| Leading End User, 2025 | Processor Manufacturers (43% share) |
| Fastest-Growing Substrate Type | Flexible Substrates (8.0% CAGR) |
| Fastest-Growing Layer Structure | Polyimide-Based (9.2% CAGR) |
| Fastest-Growing Application Segment | Mobile & Wearables (9.6% CAGR) |
| Fastest-Growing End User | Flexible Electronics Firms (9.3% CAGR) |
| Growing Sector | Semiconductor Manufacturing |
| Key End Users | Processor Manufacturers, Flexible Electronics Firms, Semiconductor OEMs |
India IC Substrate Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
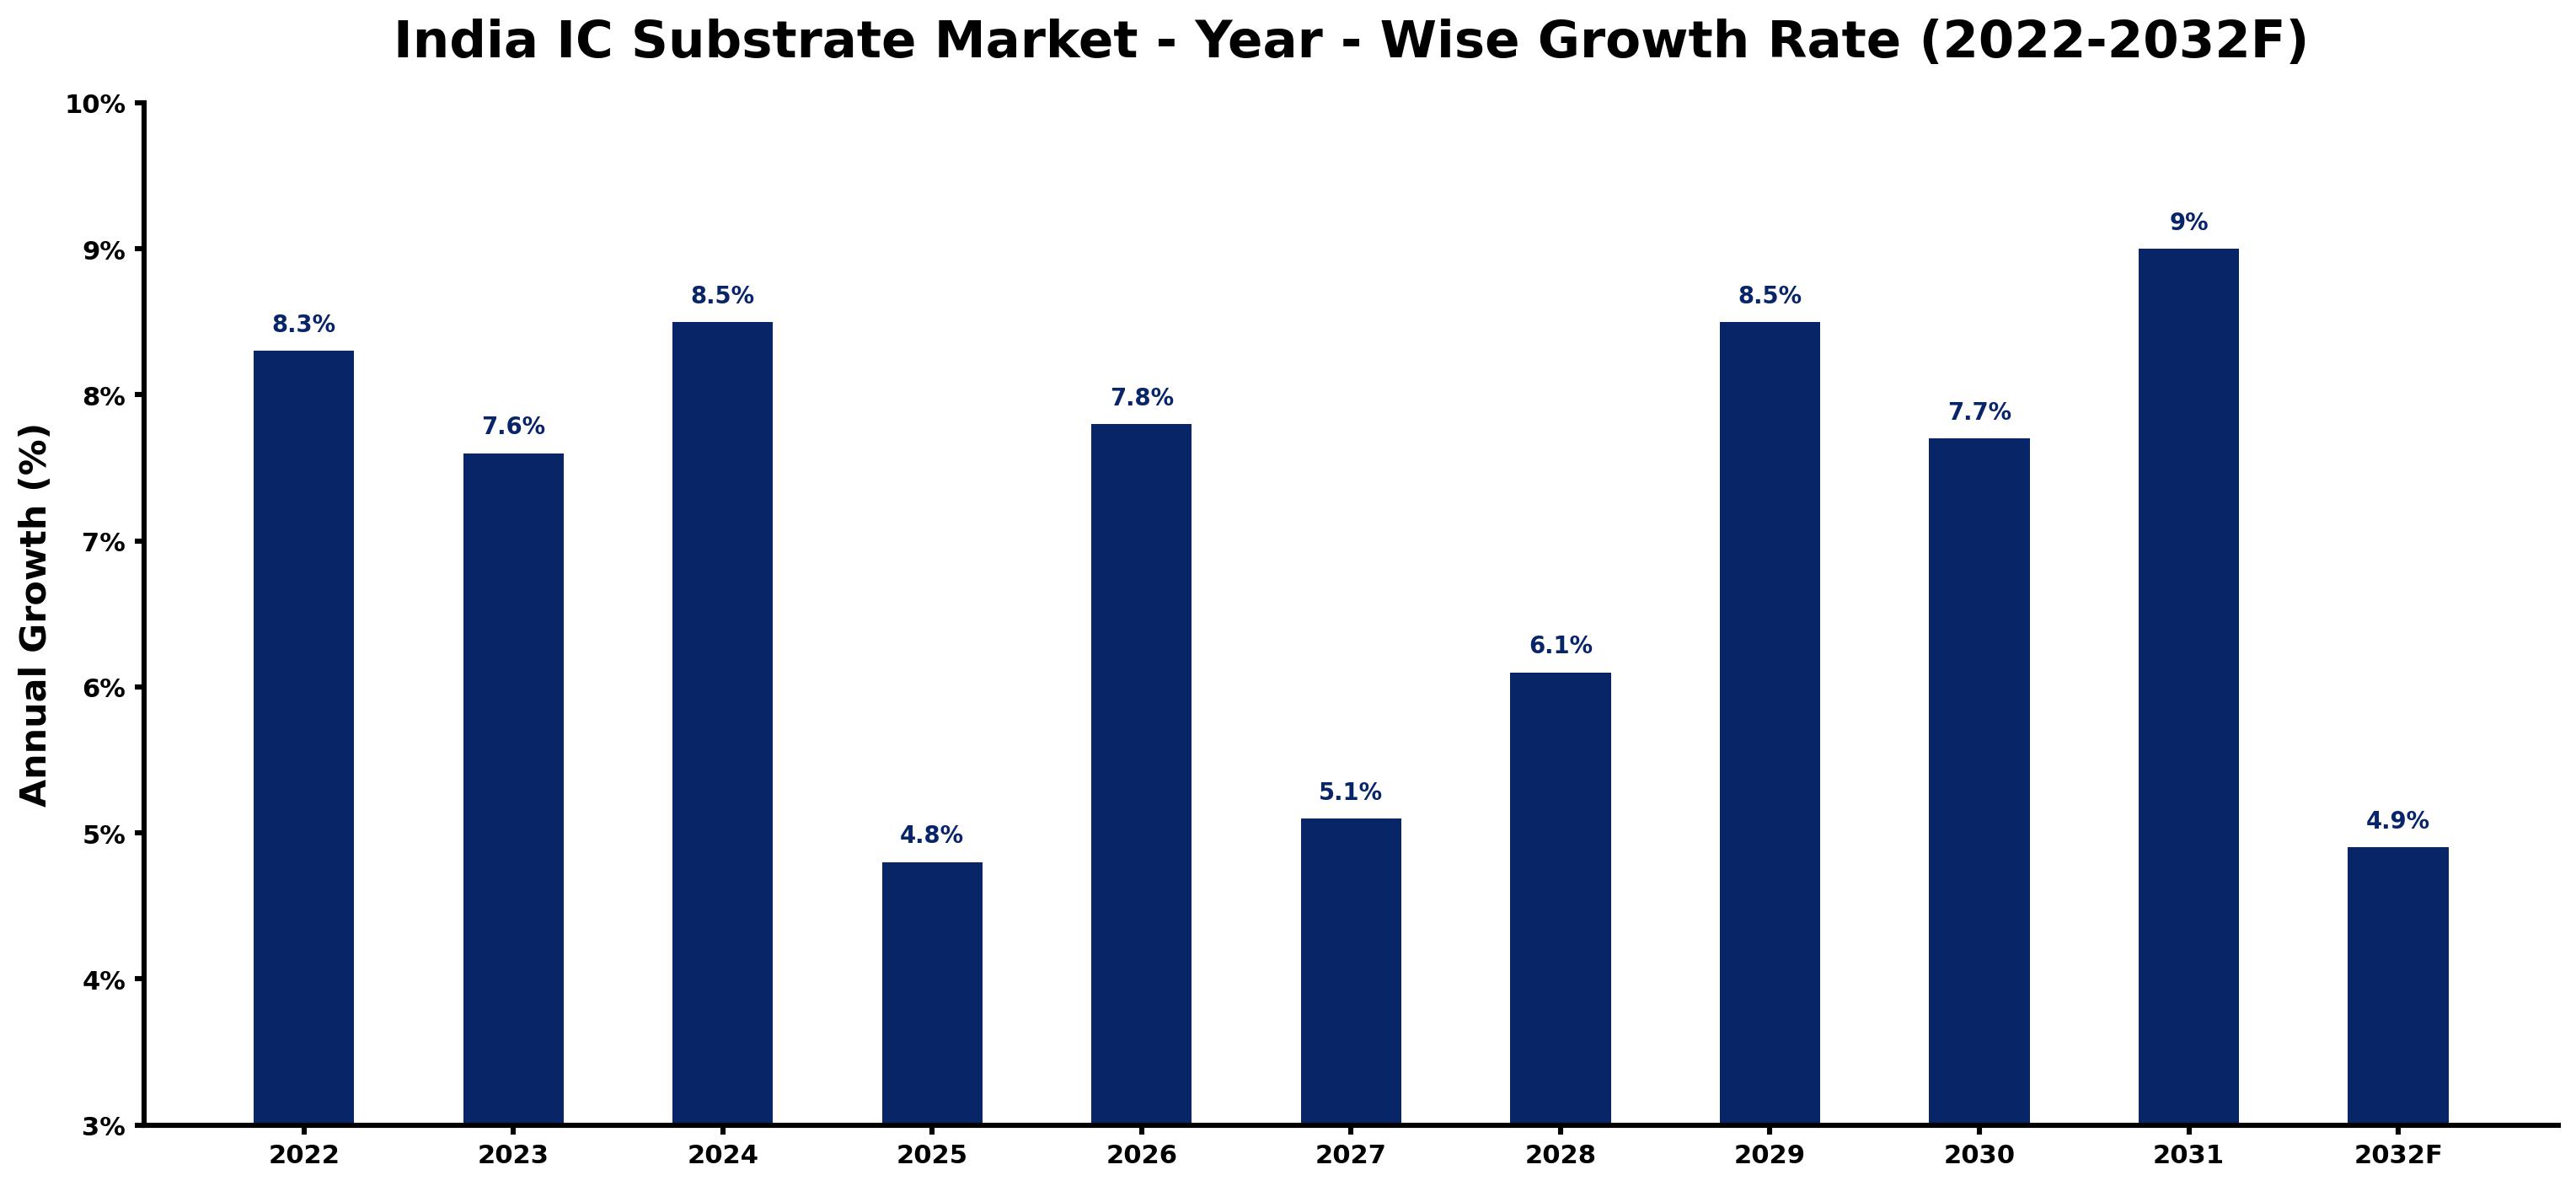
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.3 | The market experienced strong demand from local manufacturers and mobile device production. |
| 2023 | 7.6 | Growth slowed due to supply chain challenges affecting semiconductor production. |
| 2024 | 8.5 | Increased investments in semiconductor facilities led to faster growth rates. |
| 2025 | 4.8 | Growth slowed as the Production Linked Incentive scheme began attracting investments. |
| 2026 | 7.8 | Rising demand for mobile and wearable devices is expected to boost substrate needs. |
| 2027 | 5.1 | A slowdown is projected as the market adjusts to new manufacturing capacities. |
| 2028 | 6.1 | Growth is anticipated to pick up again due to increased production of high-speed devices. |
| 2029 | 8.5 | Demand is expected to surge with the expansion of mobile and wearable applications. |
| 2030 | 7.7 | Growth will slow as the market adjusts after rapid expansions. |
| 2031 | 9.0 | The market is projected to peak due to substantial investments in semiconductor technology. |
| 2032 | 4.9 | Growth will slow as the market reaches a more stable phase. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India IC Substrate Market Synopsis
IC Substrate in India is a key component for electronic devices, primarily made from epoxy resin and polyimide. It supports semiconductor chips, ensuring electrical connectivity in applications like CPUs and GPUs. The India IC Substrate Market is growing due to high domestic demand driven by local manufacturers and the increasing production of mobile devices. The Electronics Policy 2020 aims to boost semiconductor manufacturing, further increasing substrate demand. With over 1.3 billion mobile subscribers, the market is positioned for continued growth in the coming years.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased local manufacturing initiatives are driving demand for IC substrates. | Driver | High | Rigid Substrates |
| The rise in mobile device production is creating a significant market for substrates. | Driver | High | Flexible Substrates |
| The growing semiconductor sector presents opportunities for investment in substrate production. | Opportunity | High | Multilayer PCBs |
| The establishment of new semiconductor facilities is a key opportunity for suppliers. | Opportunity | High | Polyimide-Based |
| Limited supply chain capabilities can restrict substrate availability. | Restraint | Medium | Embedded Substrates |
| High production costs may deter new entrants in the substrate market. | Restraint | Medium | Organic Substrates |
| Buyers face delays due to fluctuating raw material prices affecting production. | Challenge | High | CPUs/GPUs |
| Suppliers encounter challenges in meeting high-quality standards for advanced substrates. | Challenge | Medium | High-Speed Devices |
Evaluation of Drivers in India IC Substrate Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in semiconductor manufacturing facilities drive demand for IC substrates. | Rigid Substrates | The Indian government aims to attract $10 billion in investments through the Production Linked Incentive scheme. |
| Growing mobile device production increases the need for flexible substrates. | Flexible Substrates | India produced 1.5 billion mobile devices in 2021, boosting substrate requirements significantly. |
| Rising demand for high-speed devices necessitates advanced substrate solutions. | High-Speed Devices | The need for faster processing speeds in electronics drives the need for high-quality substrates. |
| Expansion of the semiconductor sector creates opportunities for multilayer PCB applications. | Multilayer PCBs | The National Policy on Electronics aims for a $400 billion electronics sector by 2025, enhancing market prospects. |
| The increasing complexity of electronic circuits boosts demand for advanced substrates. | Polyimide-Based | The need for high-performance applications in electronics drives substrate innovation. |
Growth in the IC Substrate market in India comes from increased investments in semiconductor manufacturing, expanding capacity and infrastructure, and rising end-use demand for mobile devices. The Production Linked Incentive scheme aims to attract $10 billion in investments, boosting local production capabilities. In 2021, the country produced 1.5 billion mobile devices, which increased substrate demand. The growing complexity of electronic circuits drives demand for advanced substrates, particularly in high-speed devices and multilayer PCBs. The expansion of the semiconductor sector is expected to create new opportunities for suppliers in this market.
Evaluation of Restraints in India IC Substrate Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited supply chain capabilities restrict the availability of IC substrates. | Embedded Substrates | Supply chain disruptions have delayed production timelines for manufacturers, impacting their ability to meet demand. |
| High production costs may deter new entrants in the substrate market. | Organic Substrates | The cost of advanced materials can limit competitiveness for new suppliers, making market entry challenging. |
| Fluctuating raw material prices create uncertainty for buyers and suppliers. | CPUs/GPUs | Price volatility impacts budgeting and forecasting for electronic manufacturers, complicating financial planning. |
| Quality compliance challenges can hinder market entry for new suppliers. | High-Speed Devices | Meeting stringent standards set by the Bureau of Indian Standards can be costly and time-consuming for new entrants. |
| Technological advancements require continuous investment, posing a barrier for some firms. | Flexible Substrates | Companies may struggle to keep pace with rapid innovation in substrate technology, limiting their market participation. |
India IC Substrate Market Challenges
Buyers and suppliers in the India IC Substrate market face high compliance costs due to stringent regulations from the Bureau of Indian Standards, inflating production expenses by 15% for local manufacturers. Domestic suppliers encounter fierce competition from imported substrates, which often undercut prices, forcing them to reduce margins and risking quality. Buyers experience fluctuating demand linked to the rapid increase in mobile device production, resulting in potential shortages that can delay projects by several weeks. Supply chain disruptions in sourcing essential materials like epoxy resin can cause delays of up to three months for producers, hindering their ability to meet market requirements.
Trends in the India IC Substrate Market
Several trends are reshaping the India IC Substrate Market; the most important are set out below.
- Shift towards High-Performance Substrates: Processor manufacturers are increasingly opting for high-performance substrates to meet evolving technology demands. The rise in mobile device production, with 1.5 billion units produced in 2021, underscores this shift.
- Transition to Multilayer PCB Designs: The demand for complex circuit designs is driving a transition towards multilayer PCBs. This is reflected in multilayer PCBs holding a 49% market share in 2025, highlighting their importance in modern electronics.
- Emergence of Flexible Substrates: Flexible substrates are becoming crucial for mobile and wearable devices, driven by consumer demand. This segment is projected to grow at a CAGR of 8.0% from 2026 to 2032, indicating its significance.
- Increased Focus on Local Manufacturing: The Indian government’s Electronics Policy 2020 promotes local manufacturing, aiming for a $400 billion sector by 2025. This initiative is expected to considerably boost the domestic substrate market.
Investment Opportunities in the India IC Substrate Market
The following opportunities in the India IC Substrate Market pair current demand with a clear way in.
- Timing for Investment in Semiconductor Facilities: With the Indian government aiming to attract $10 billion in semiconductor investments, now is an optimal time to invest in manufacturing facilities. Processor manufacturers are key buyers in this sector.
- Bangalore as a Semiconductor Hub: Bangalore serves as a major hub for semiconductor manufacturing, offering opportunities for suppliers. The city’s established infrastructure supports new entrants looking to set up operations.
- Supply of Advanced Substrate Solutions: The increasing complexity of electronic devices generates demand for advanced substrate solutions. Flexible electronics firms are seeking innovative products to enhance their offerings.
- Entry through Joint Ventures: Entering the market through joint ventures with local firms can facilitate access to the growing IC substrate sector. This approach allows for shared resources and expertise.
Government Initiatives in the India IC Substrate Market
The Electronics Manufacturing Cluster scheme, initiated in 2020, provides financial support for establishing semiconductor manufacturing units, aiming to boost local production capabilities. This initiative complements the Production Linked Incentive (PLI) scheme, which targets attracting $10 billion in investments. Together, these measures create a supportive environment for domestic producers and suppliers, driving growth in the semiconductor market. The National Policy on Electronics 2019 also backs these efforts, aiming for a $400 billion electronics sector by 2025, which will greatly impact IC substrate demand.
Processor manufacturers benefit from the Electronics Manufacturing Cluster scheme, which offers financial support for establishing semiconductor manufacturing units. This initiative, launched in 2020, aims to strengthen local production capabilities. The Ministry of Electronics and Information Technology oversees these efforts, ensuring effective allocation of funds to support the growth of the semiconductor industry. In 2021, the ministry approved several projects aimed at enhancing semiconductor research and development, which will further assist local producers.
Future Insight of the India IC Substrate Market
The India IC Substrate market is set for considerable growth by 2032, driven by the Electronics Policy 2020 which aims to boost local semiconductor manufacturing. The Production Linked Incentive scheme will attract investments, facilitating the establishment of new semiconductor facilities nationwide. By 2025, the electronics manufacturing sector targets reaching $400 billion, creating expanded opportunities for local suppliers. Training initiatives from the National Institute of Electronics and Information Technology will ensure a skilled workforce, addressing the industry's need for qualified professionals.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Substrate Type – Rigid Substrates Dominated, Flexible Substrates Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, with a 37% revenue share in 2025, Rigid Substrates was the largest substrate type category. Rigid substrates hold the largest share in the India IC substrate market due to their essential function in traditional PCB applications, especially for processor manufacturers. Their widespread usage is reinforced by the country's vast base of over 1.3 billion mobile subscribers, showcasing their significance in electronic devices. Flexible Substrates are set to record the highest CAGR in this split, 8.0% over 2026–2032. Flexible substrates are experiencing rapid growth, primarily driven by the increasing demand for mobile and wearable devices that require lightweight and adaptable materials. The production of 1.5 billion mobile devices in 2021 highlights this shift towards more flexible designs, suggesting a continued expansion in this segment. Suppliers should prioritise the development of flexible substrate solutions to capture the growing market share associated with mobile and wearable technology.
By Layer Structure – Multilayer PCBs Dominated, Polyimide-Based Expected to Grow Fastest
Multilayer PCBs took a 49% share of layer structure in 2025, more than any other category. Multilayer PCBs dominate the market as they are critical for complex circuit designs, which are essential in high-performance electronics. Their established use in various applications solidifies their position among processor manufacturers and other key players. The quickest growth will come from Polyimide-Based, forecast to expand at a CAGR of 9.2% between 2026 and 2032. Polyimide-based substrates are the fastest-growing segment, largely due to their importance in high-performance applications that demand superior thermal and electrical properties. The push for advanced electronics in the Indian market is likely to accelerate their adoption further. Buyers should consider investing in polyimide-based substrates to stay competitive in high-performance electronics applications.
By Application Segment – CPUs/GPUs Dominated, Mobile & Wearables Expected to Grow Fastest
CPUs/GPUs held a 38% share of the India IC Substrate Market by application segment in 2025. CPUs and GPUs represent the largest application segment for IC substrates, as they are fundamental components in computing devices. The increasing complexity of these processors drives demand for reliable substrate solutions across the electronics industry. Over 2026–2032, Mobile & Wearables are expected to post the fastest growth, at a CAGR of 9.6%. The mobile and wearables segment is growing the fastest, propelled by the surge in device usage and consumer demand for portable technology. This trend is expected to continue as more users adopt smart devices in their daily lives. Suppliers must align their product development with the needs of the mobile and wearables market to capture emerging opportunities.
By End User – Processor Manufacturers Dominated, Flexible Electronics Firms Expected to Grow Fastest
In 2025, Processor Manufacturers led the end user split with a 43% share. Processor manufacturers dominate the end-user segment of the IC substrate market, as they depend on reliable materials for their high-performance semiconductor chips. The robust investments in semiconductor manufacturing in India further reinforce their leading market share. Flexible Electronics Firms are projected to grow fastest, at a CAGR of 9.3% during 2026–2032. Flexible electronics firms are the fastest-growing end-user segment, spurred by the rising demand for flexible substrates across various applications. The introduction of innovative consumer electronics is likely to accelerate this growth trajectory in the coming years. Suppliers should target flexible electronics firms to capitalise on the expanding market share related to flexible IC substrates.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India IC Substrate Market Outlook
- Market Size of India IC Substrate Market, 2025
- Forecast of India IC Substrate Market, 2032
- Historical Data and Forecast of India IC Substrate Revenues & Volume for the Period 2022 - 2032F
- India IC Substrate Market Trend Evolution
- India IC Substrate Market Drivers and Challenges
- India IC Substrate Price Trends
- India IC Substrate Porter's Five Forces
- India IC Substrate Industry Life Cycle
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Substrate Type for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Rigid Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Flexible Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Embedded Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Organic Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Layer Structure for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Multilayer PCBs for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Polyimide-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Component-in-Substrate for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By BT/FR-4 Materials for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Application Segment for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By CPUs/GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Mobile & Wearables for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By High-Speed Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Memory ICs for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Processor Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Flexible Electronics Firms for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By Semiconductor OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India IC Substrate Market Revenues & Volume By DRAM/Flash Makers for the Period 2022 - 2032F
- India IC Substrate Import Export Trade Statistics
- Market Opportunity Assessment By Substrate Type
- Market Opportunity Assessment By Layer Structure
- Market Opportunity Assessment By Application Segment
- Market Opportunity Assessment By End User
- India IC Substrate Top Companies Market Share
- India IC Substrate Competitive Benchmarking By Technical and Operational Parameters
- India IC Substrate Company Profiles
- India IC Substrate Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Substrate Type
- Rigid Substrates
- Flexible Substrates
- Embedded Substrates
- Organic Substrates
By Layer Structure
- Multilayer PCBs
- Polyimide-Based
- Component-in-Substrate
- BT/FR-4 Materials
By Application Segment
- CPUs/GPUs
- Mobile & Wearables
- High-Speed Devices
- Memory ICs
By End User
- Processor Manufacturers
- Flexible Electronics Firms
- Semiconductor OEMs
- DRAM/Flash Makers































