China IC Substrate Market Size & Growth Rate
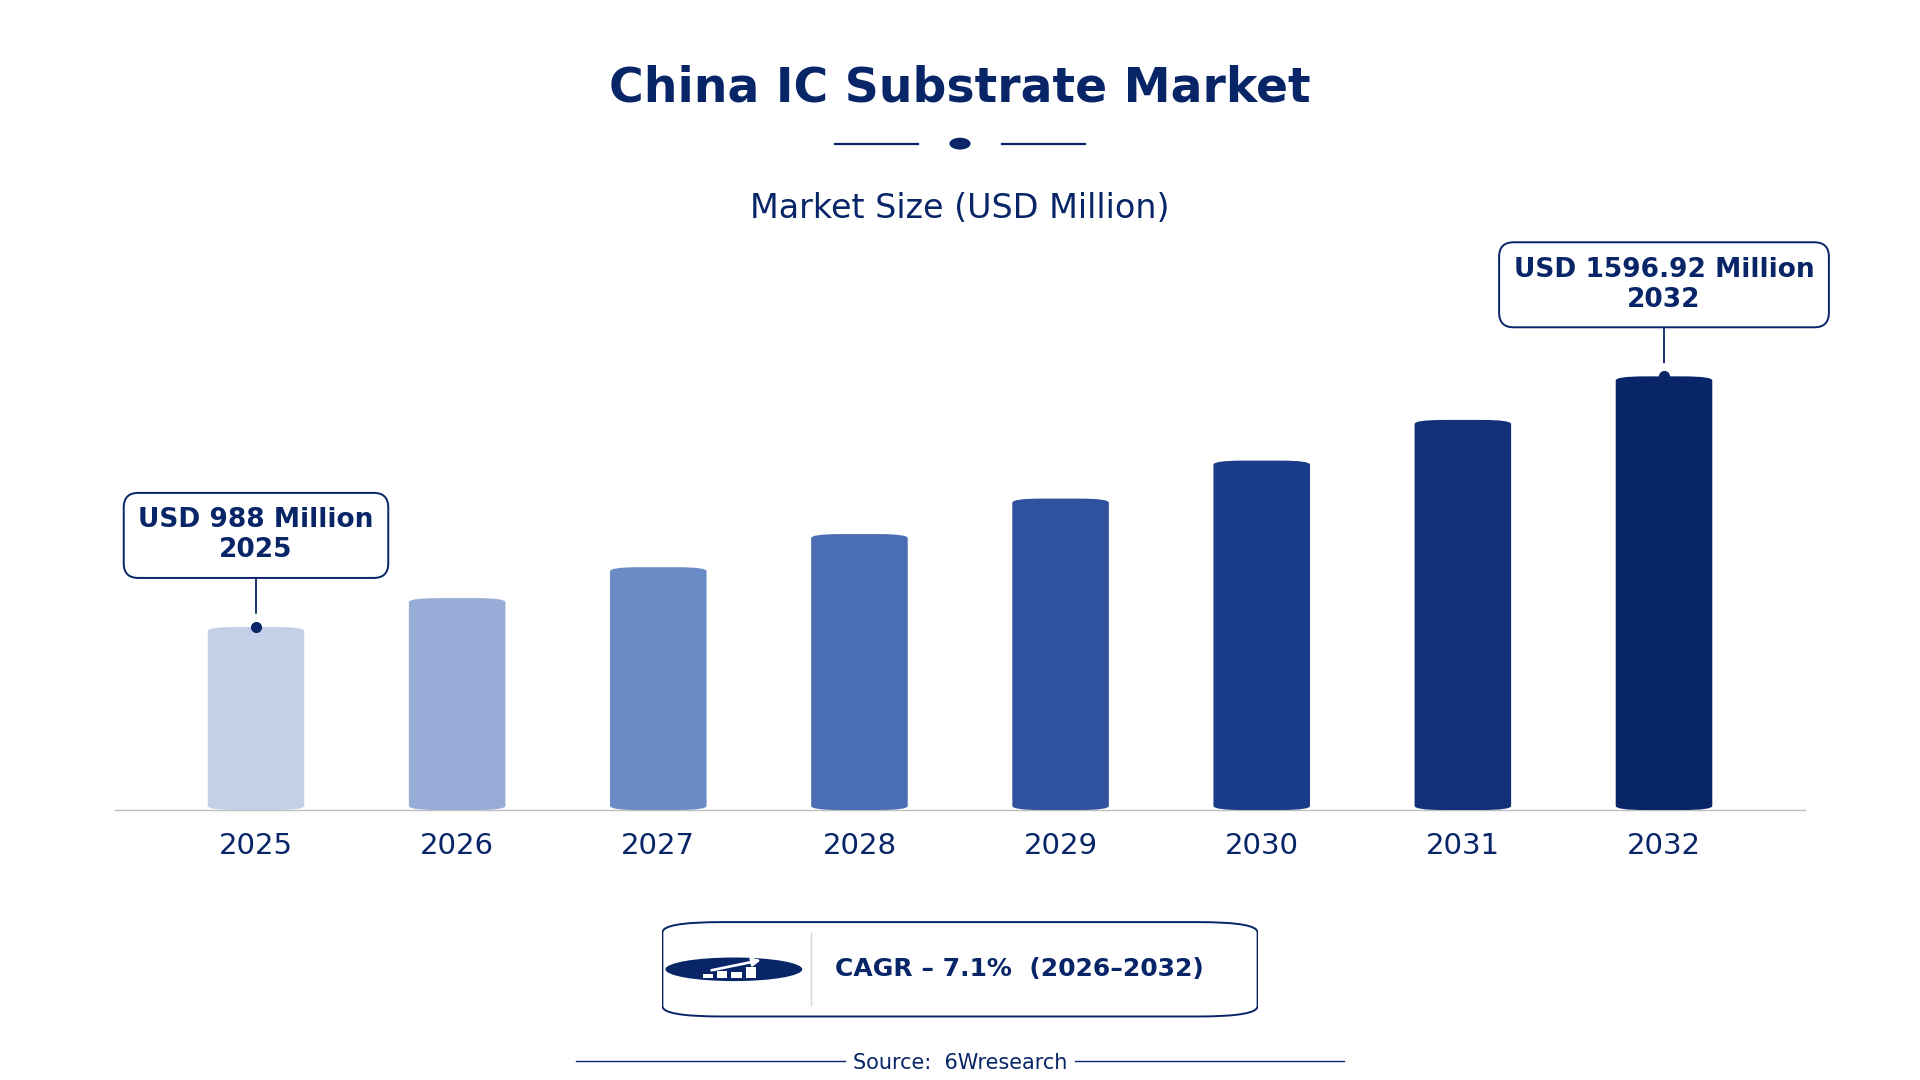
According to 6Wresearch internal database and industry insights, the China IC Substrate Market was valued at USD 988.0 million in 2025 and is projected to reach USD 1,596.92 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China IC Substrate Market Highlights
| Report Metric | Details |
| Report Name | China IC Substrate Market |
| Market Size 2025 | USD 988.0 million |
| Market Size 2032 | USD 1,596.92 million |
| Absolute Growth 2025–2032 | USD 608.92 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 8.8% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Substrate Type, 2025 | Rigid Substrates (48% share) |
| Leading Layer Structure, 2025 | Multilayer PCBs (41% share) |
| Leading Application Segment, 2025 | CPUs/GPUs (47% share) |
| Leading End User, 2025 | Semiconductor OEMs (44% share) |
| Fastest-Growing Substrate Type | Flexible Substrates (8.5% CAGR) |
| Fastest-Growing Layer Structure | Polyimide-Based (9.6% CAGR) |
| Fastest-Growing Application Segment | Mobile & Wearables (9.5% CAGR) |
| Fastest-Growing End User | Flexible Electronics Firms (8.4% CAGR) |
| Growing Sector | Semiconductor Manufacturing |
| Key End Users | Semiconductor OEMs, Processor Manufacturers, Flexible Electronics Firms, DRAM/Flash Makers |
China IC Substrate Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
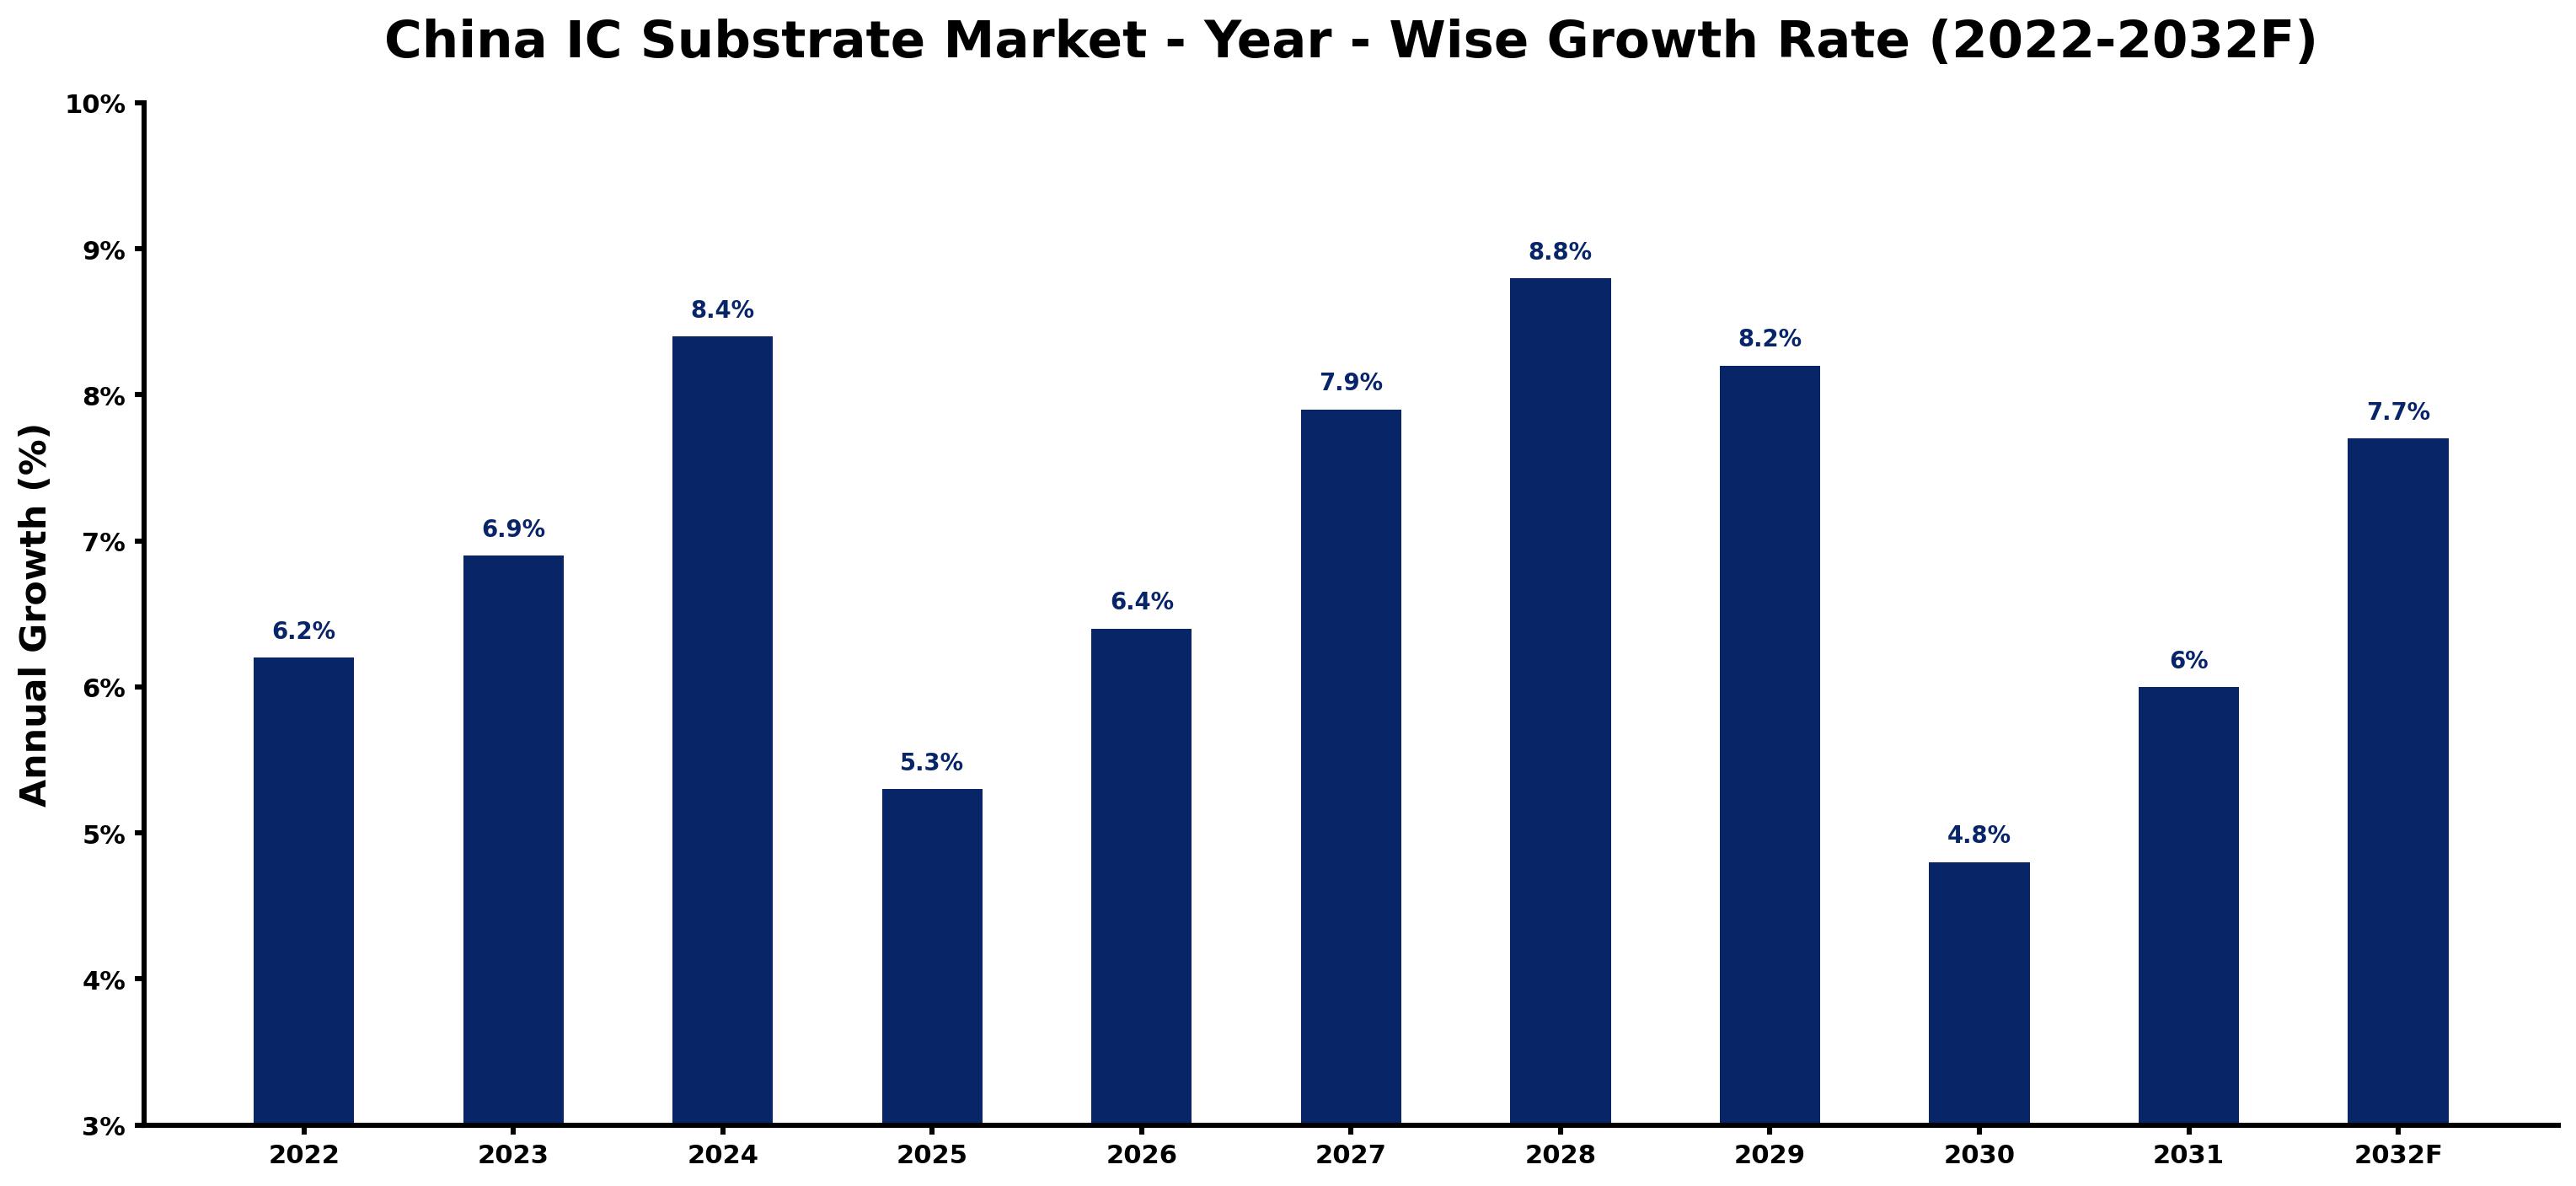
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The market experienced steady growth, supported by rising domestic demand for consumer electronics. |
| 2023 | 6.9 | Growth accelerated due to increased investments in semiconductor manufacturing capabilities, particularly in the Yangtze River Delta. |
| 2024 | 8.4 | A surge in demand for CPUs and GPUs drove higher production rates, reflecting the industry's expansion. |
| 2025 | 5.3 | Growth slowed as the market adjusted to previous rapid expansions, influenced by the '14th Five-Year Plan'. |
| 2026 | 6.4 | New projects commenced under national initiatives, leading to recovery in growth as production capacity increased. |
| 2027 | 7.9 | Investment in high-performance electronics spurred demand for IC substrates, particularly from semiconductor OEMs. |
| 2028 | 8.8 | The peak growth year is expected to be reached, driven by innovations in semiconductor technology and production. |
| 2029 | 8.2 | Growth is projected to slow slightly as the market begins to stabilise post-peak, influenced by regulatory changes. |
| 2030 | 4.8 | A further slowdown is anticipated as the market adjusts to new production capacities and evolving standards. |
| 2031 | 6.0 | Growth will rebound as demand from semiconductor OEMs increases, supported by advancements in technology. |
| 2032 | 7.7 | The market is expected to grow steadily as self-sufficiency targets are pursued under the 'Made in China 2025' initiative. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China IC Substrate Market Synopsis
IC Substrate in China is a vital component used in electronics, particularly for mounting semiconductor devices. Made from materials like epoxy and polyimide, it is essential for CPUs, GPUs, and high-performance electronics. The China IC Substrate Market is expanding due to strong domestic demand and significant investments in semiconductor manufacturing. The semiconductor industry, valued at $143 billion in 2022, continues to grow, supported by initiatives like the 'Made in China 2025' programme. With a population of 1.4 billion, consumer electronics demand remains a key driver.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic demand for consumer electronics drives the need for IC substrates. | Driver | High | CPUs/GPUs |
| Increased investments in semiconductor manufacturing enhance production capabilities. | Driver | High | Multilayer PCBs |
| Growing demand for high-performance electronics presents opportunities for suppliers. | Opportunity | High | Flexible Substrates |
| Expansion of semiconductor manufacturing facilities in the Yangtze River Delta creates new market prospects. | Opportunity | High | Rigid Substrates |
| High production costs limit profit margins for manufacturers. | Restraint | Medium | Embedded Substrates |
| Supply chain disruptions can affect timely delivery of materials. | Restraint | Medium | Organic Substrates |
| IC Substrate Market in China faces challenges from fluctuating raw material prices. | Challenge | High | Component-in-Substrate |
| Technological advancements require continuous investment, posing a financial burden. | Challenge | Medium | BT/FR-4 Materials |
Evaluation of Drivers in China IC Substrate Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased domestic production capacity is driving demand for IC substrates. | Rigid Substrates | China produced 20 million units of IC substrates in 2022, meeting rising local demand for electronics. |
| Growing consumer electronics market fuels the need for high-performance substrates. | CPUs/GPUs | The semiconductor industry in China was valued at $143 billion in 2022, increasing substrate purchases significantly. |
| Investment in semiconductor innovation is boosting substrate manufacturing capabilities. | Multilayer PCBs | The 'Made in China 2025' initiative aims to advance semiconductor technology and production, enhancing local capabilities. |
| The rise of mobile devices increases demand for flexible substrates. | Flexible Substrates | Mobile & Wearables are projected to grow at a rate of 9.5%, driving substrate requirements for these applications. |
| Technological advancements in IC substrate production improve efficiency. | Polyimide-Based | ISO 9001 standards are widely adopted, ensuring production quality and reliability across the industry. |
Market growth for IC Substrate in China is underpinned by increased domestic production capacity, which is driving demand for substrates. In 2022, China produced 20 million units of IC substrates, fulfilling the rising local demand for electronics. The semiconductor industry, valued at $143 billion, fuels the need for high-performance substrates, particularly for CPUs and GPUs. The rise of mobile devices is increasing demand for flexible substrates, as consumer preferences shift towards portable technology and high-performance applications. This dynamic environment supports a strong market for IC substrates, creating opportunities for growth and investment.
Evaluation of Restraints in China IC Substrate Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs limit profit margins for manufacturers. | Rigid Substrates | The average cost of IC substrate production has risen by 15% due to material price increases. |
| Supply chain disruptions can affect timely delivery of materials. | Flexible Substrates | Recent global supply chain issues have delayed shipments, impacting production schedules. |
| Fluctuating raw material prices create uncertainty for producers. | Embedded Substrates | Raw material costs have increased by 10% in the last year, affecting pricing strategies. |
| Technological advancements require continuous investment, posing a financial burden. | Organic Substrates | Manufacturers need to invest heavily in R&D to keep up with industry standards and innovations. |
| Regulatory compliance can increase operational costs. | CPUs/GPUs | Compliance with ISO 9001 standards requires additional investments in quality control and testing. |
China IC Substrate Market Challenges
The China IC Substrate market encounters several practical challenges, starting with buyers facing high input costs due to limited domestic raw material availability. This scarcity compels manufacturers to rely on imports, which can elevate production costs by up to 20%. Skills shortages in semiconductor technology pose difficulties, as the industry lacks over 200,000 qualified engineers, delaying product development timelines for producers. Supply chain disruptions in the Yangtze River Delta can lead to production halts, affecting delivery schedules for buyers. Regulatory hurdles, such as compliance with ISO 9001 standards, add complexity and can prolong the certification process by several months for new entrants.
Trends in the China IC Substrate Market
Buyers and suppliers in the China IC Substrate Market are adjusting to the following trends.
- Shift from Rigid to Flexible Substrates: Since 2022, flexible substrates have gained traction due to the rise of mobile devices. The demand for flexible electronics has surged, with a projected growth rate of 9.5% for Mobile & Wearables, indicating a shift in manufacturing focus.
- Transition to Advanced Packaging Solutions: In 2021, the introduction of new packaging standards has led to increased adoption of embedded substrates. This shift supports the integration of advanced technology in semiconductor devices, improving performance and efficiency.
- Emergence of Eco-Friendly Materials: Beginning in 2023, there is a growing emphasis on sustainable materials in IC substrate production. The adoption of eco-friendly options is expected to rise, aligning with global environmental goals and consumer preferences.
- Prioritisation of High-Performance Applications: In 2022, the focus on high-performance applications has intensified, particularly for CPUs/GPUs. This trend reflects the rising need for advanced computing capabilities across various sectors.
Investment Opportunities in the China IC Substrate Market
Several openings in the China IC Substrate Market merit attention from investors.
- Investment in Semiconductor Manufacturing Facilities: The Yangtze River Delta is a key region for semiconductor production, with a budget of $29 billion allocated for new facilities. This presents an opportunity for suppliers to establish partnerships and expand their market presence.
- Growing Demand from Semiconductor OEMs: Semiconductor OEMs are increasingly seeking advanced IC substrates to improve their product offerings. With a projected market size of $1,596.92 million by 2032, suppliers can target this buyer group for growth.
- Expansion of Mobile Device Production: Flexible electronics firms are ramping up production to meet rising consumer demand for smartphones. Suppliers can invest in flexible substrates to cater to this growing market segment.
- Collaboration with Local Manufacturers: Entering joint ventures with local manufacturers can facilitate market entry in China. This approach allows for shared resources and compliance with local regulations, boosting competitiveness.
Government Initiatives in the China IC Substrate Market
The 'National Integrated Circuit Industry Investment Fund' established in 2021 by the Ministry of Industry and Information Technology allocates $29 billion to support semiconductor projects. This funding is essential for improving production capabilities and driving innovation in the IC substrate sector. Additionally, the '14th Five-Year Plan for Economic and Social Development' launched in 2021 focuses on increasing domestic semiconductor production, further strengthening the market framework. These measures aim to boost local manufacturing and reduce reliance on foreign technology, ensuring a more self-sufficient industry.
The semiconductor industry benefits from various schemes, including the 'Made in China 2025' initiative, which promotes advancements in semiconductor technology. This initiative encourages local manufacturers to innovate and improve their production processes. The Ministry of Industry and Information Technology oversees the implementation of these strategies, ensuring that funding is directed towards projects that strengthen the semiconductor supply chain. Furthermore, the 'Semiconductor Industry Development Promotion Plan' issued in 2020 aims to boost local manufacturing and innovation, providing additional support to buyers and producers in the IC substrate market.
Future Insight of the China IC Substrate Market
The China IC Substrate market will undergo significant changes by 2032, primarily driven by advancements in semiconductor technology. The 'Made in China 2025' initiative will enhance local production capabilities, aiming for 70% self-sufficiency by 2025. Increased investments from the '14th Five-Year Plan' will support innovation, benefiting suppliers and buyers alike. By 2025, the semiconductor market in China is expected to reach a valuation of $143 billion, creating new opportunities for manufacturers to meet the rising demand from China's 1.4 billion population for consumer electronics.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Substrate Type – Rigid Substrates Dominated, Flexible Substrates Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, with a 48% revenue share in 2025, Rigid Substrates was the largest substrate type category. Rigid substrates dominate the China IC substrate market due to their extensive application in traditional electronics manufacturing, particularly for CPUs and GPUs. This established usage ensures a robust installed base and consistent demand from manufacturers across the country. Flexible Substrates are projected to grow fastest, at a CAGR of 8.5% during 2026–2032. The rapid growth of flexible substrates is driven by the increasing demand for mobile devices and wearables that require flexible components. As the consumer electronics market continues to expand, this segment is set for remarkable growth in the coming years. Suppliers must focus on developing flexible substrate solutions to meet the rising demand in mobile and wearable technology.
By Layer Structure – Multilayer PCBs Dominated, Polyimide-Based Expected to Grow Fastest
In 2025, Multilayer PCBs led the layer structure split with a 41% share. Multilayer PCBs hold the largest market share as they are essential for complex electronic circuits used in various applications, including consumer electronics and automotive systems. Their versatility and reliability make them a staple in the IC substrate market. The quickest growth will come from Polyimide-Based, forecast to expand at a CAGR of 9.6% between 2026 and 2032. Polyimide-based substrates are growing quickly due to their importance in high-temperature and flexible applications, which are increasingly required in advanced electronics. This segment's growth reflects the industry's shift towards more adaptable materials. Buyers should consider investing in polyimide-based solutions to stay competitive in high-performance electronics applications.
By Application Segment – CPUs/GPUs Dominated, Mobile & Wearables Expected to Grow Fastest
The largest application segment category in 2025 was CPUs/GPUs, with a 47% share of total revenue. CPUs and GPUs represent the largest share of the application segment, as they are fundamental for processing units in computers and devices. The continuous demand for high-performance computing drives the need for reliable IC substrates in this category. Over 2026–2032, Mobile & Wearables are expected to post the fastest growth, at a CAGR of 9.5%. The mobile and wearables segment is the fastest-growing application area, fueled by the proliferation of smartphones and wearable technology that rely on advanced substrates. This trend indicates a shift towards more portable and flexible electronics. Suppliers must adapt their offerings to cater to the increasing needs of the mobile and wearables market to capture emerging opportunities.
By End User – Semiconductor OEMs Dominated, Flexible Electronics Firms Expected to Grow Fastest
Semiconductor OEMs accounted for a 44% market share by end user in 2025. Semiconductor OEMs dominate the end-user segment as they depend heavily on IC substrates for assembling various semiconductor devices. Their critical role in the supply chain guarantees a steady demand for these substrates across the industry. Flexible Electronics Firms are set to record the highest CAGR in this split, 8.4% over 2026–2032. Flexible electronics firms are growing at the fastest rate, propelled by the rising popularity of flexible devices that require specialised substrates. This trend underscores the potential for advancements in the flexible electronics sector. Suppliers should align their offerings with the requirements of flexible electronics firms to seize emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China IC Substrate Market Outlook
- Market Size of China IC Substrate Market, 2025
- Forecast of China IC Substrate Market, 2032
- Historical Data and Forecast of China IC Substrate Revenues & Volume for the Period 2022 - 2032F
- China IC Substrate Market Trend Evolution
- China IC Substrate Market Drivers and Challenges
- China IC Substrate Price Trends
- China IC Substrate Porter's Five Forces
- China IC Substrate Industry Life Cycle
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Substrate Type for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Rigid Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Flexible Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Embedded Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Organic Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Layer Structure for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Multilayer PCBs for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Polyimide-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Component-in-Substrate for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By BT/FR-4 Materials for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Application Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By CPUs/GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Mobile & Wearables for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By High-Speed Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Memory ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Processor Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Flexible Electronics Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By Semiconductor OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China IC Substrate Market Revenues & Volume By DRAM/Flash Makers for the Period 2022 - 2032F
- China IC Substrate Import Export Trade Statistics
- Market Opportunity Assessment By Substrate Type
- Market Opportunity Assessment By Layer Structure
- Market Opportunity Assessment By Application Segment
- Market Opportunity Assessment By End User
- China IC Substrate Top Companies Market Share
- China IC Substrate Competitive Benchmarking By Technical and Operational Parameters
- China IC Substrate Company Profiles
- China IC Substrate Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Substrate Type
- Rigid Substrates
- Flexible Substrates
- Embedded Substrates
- Organic Substrates
By Layer Structure
- Multilayer PCBs
- Polyimide-Based
- Component-in-Substrate
- BT/FR-4 Materials
By Application Segment
- CPUs/GPUs
- Mobile & Wearables
- High-Speed Devices
- Memory ICs
By End User
- Processor Manufacturers
- Flexible Electronics Firms
- Semiconductor OEMs
- DRAM/Flash Makers































